Investor | AI infrastructure, semis & growth software | Deep dives on what I own. Largest: $ZETA $NBIS $APP $IREN | Long-term holder | Not financial advice
Thanks, appreciate the follow.
The gap is the share count. The 456M in the post is the basic count by end of 2028. The targets use fully diluted shares at end of 2027, ~580M:
• ~436M basic
• ~8M of employee awards
• ~100-108M from the $6.75B of converts, all in the money at those prices, net of the capped calls
• 30M from NVIDIA's right at $70, which also brings in $2.1B of cash
At 5x, that's ~$69B of EV minus ~$11.8B of net debt after NVIDIA's cash, so ~$57.6B of equity over ~575M shares, or ~$100. Your method with debt and shares held at the 8x numbers gives ~$99.
Happy to dig into whichever assumptions look like a stretch to you👍🏻
$IREN
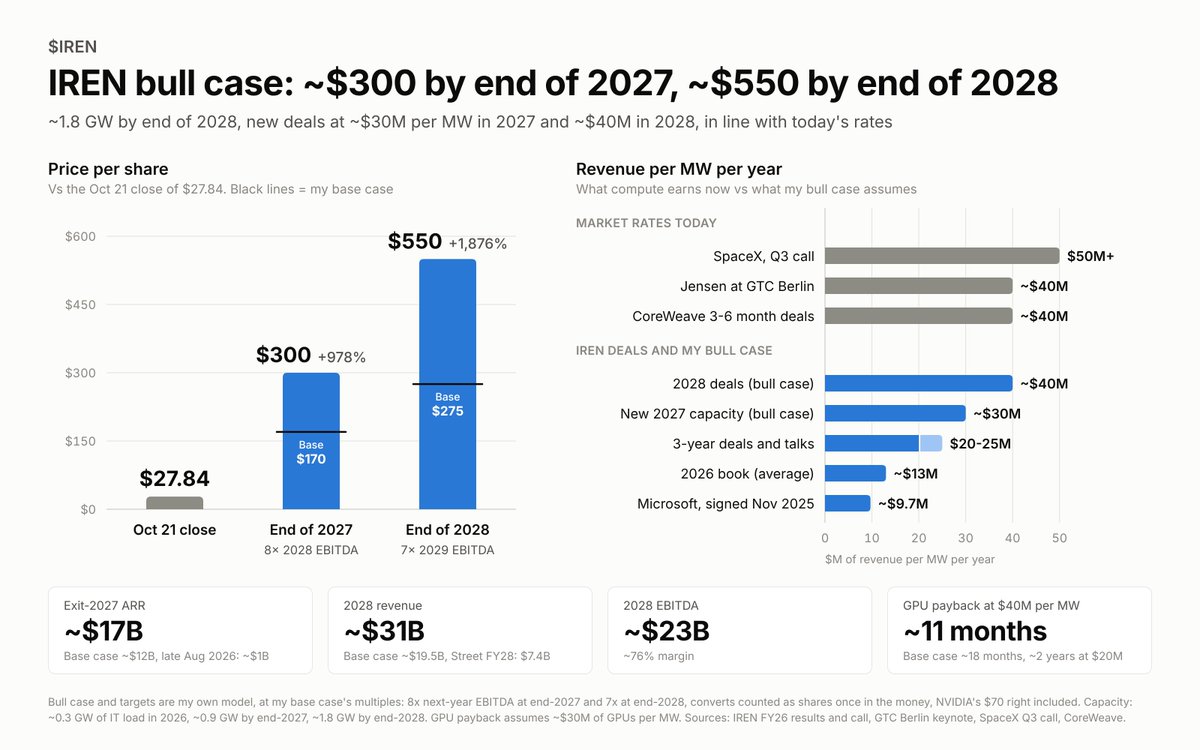
My IREN bull case, built on management's own plan.
What came out this week:
At GTC Berlin, Nebius's CRO said compute prices keep rising faster than expected and its 2027 capacity could sell immediately at current prices. Meta's 10-Q showed its non-cancelable commitments up from $349B to $455B in one quarter, mostly third-party cloud capacity. IREN set up IREN Europe with a 300 MW campus planned in Spain, and The Information reported Anthropic has a multiyear cloud deal with IREN, which lines up with the "leading frontier AI lab" IREN signed in August.
What a MW of AI compute earns right now:
• Jensen: ~$40M per MW a year
• SpaceX: slightly above $50 per watt, with payback under a year
• CoreWeave's 3-6 month deals in Q3: ~$40M per MW
• IREN: 3-year deals above $20M, talks around $25M, Microsoft at ~$9.7M
Why I expect IREN's 2027 and 2028 deals to price well above its 2026 book:
• 3-year pricing is up ~125% since November and 5-year ~70%
• Co-CEO Daniel Roberts: "Signing deals is not the bottleneck in this market, bringing GPUs online is," and "Every megawatt we build is scarce"
• Vera Rubin systems are already on order, and Jensen calls Rubin "30 times greater than Blackwell"
• The 2026 book averages ~$13M/MW, held down by Microsoft, which was signed before that ~125% rise
My base case:
• Management's plan: ~0.3 GW of IT load in 2026 and ~0.8 GW by end of 2027. I add ~0.6 GW in 2028 from Sweetwater, Kiowa, Bundey and Badajoz
• The $4B of ARR contracted for 2026 capacity fully live by early 2027, plus ~$0.7B from NVIDIA
• New 2027 capacity at ~$25M/MW, where talks are today
• 2028 deals at ~$30M/MW, still 25-40% below today's short-term rates
• ~20% of the funding gap raised as stock, taking shares from 394M to ~456M by end of 2028
That gives exit-2027 ARR of ~$12B, 2028 revenue of ~$19.5B and EBITDA of ~$14B, with payback on the GPUs down from ~2 years to ~18 months at $25M and ~15 at $30M. Valued at 8x next year's EBITDA, a discount to the 10x I use for Nebius, that's ~$170 by end of 2027. At 7x, it's ~$275 by end of 2028. That's about 29x and 15x forward earnings.
Stress tests on that:
• New deals stuck at $20M: ~$125 by end of 2027
• Every MW six months late: ~$130
• Today's ~5x EBITDA instead of 8x: ~$100
• Half the funding gap raised in stock at $30-40: ~$140
Bull case, ~0.9 GW by end of 2027 and ~1.8 GW by end of 2028, with new deals at ~$30M in 2027 and ~$40M by 2028: ~$300 by end of 2027 and ~$550 by end of 2028.
What the market pays today: ~$10B, ~2.1x the $4.7B of ARR already contracted for 2026 capacity plus NVIDIA, ~0.8x the ARR I expect at the end of 2027 and ~1.4x Street revenue of $7.4B for the year to June 2028. NVIDIA's right to invest up to $2.1B is struck at $70, ~2.8x today's price. ~21% of shares outstanding are sold short.
How it's funded: ~$14B of cash, committed GPU financing and prepayments, including $3.6B of investment grade GPU debt at 6.0% for Microsoft and $2.4B from Blue Owl and PIMCO at 9.0%. Prepayments cover 45-55% of GPU capex on recent deals, and every data center is still unencumbered.
Track record:
• AI cloud revenue went from $16.4M in FY25 to $128.8M in FY26, and Q4's $70.5M more than doubled Q3
• $1B of ARR operating by late August, and 2026 capacity "largely sold out"
• Signed Microsoft for $9.7B and NVIDIA for $3.4B plus a partnership for up to 5 GW, with customers including Perplexity, Cohere and Figure AI
• Delivered Horizon 1 in August with NVIDIA Exemplar Cloud status on GB300 NVL72
• Energized the 1.4 GW Sweetwater 1 substation on schedule, part of a 2 GW hub
Much of today's price is oil, rates and CoreWeave's bonds. IREN touched a new 52-week low of $24.86 today, ~68% below its high, with no IREN-specific bad news.
I'm long $IREN. It's one of my biggest positions.
@Agrippa_Inv@FransBakker9812@Bare_Birk@jiahanjimliu I'd value your take, especially on the pricing. A repost helps if you think it's worth reading.
$NBIS
Nebius just signed a $3.5B senior secured facility with Citi, while AI infrastructure debt is selling off across the board.
The terms:
• $3.5B, with Citi as mandated lead arranger, agent and security agent
• Term SOFR + 2.75% to start, capped at SOFR + 3.50%. With SOFR around 3.9%, that's roughly 6.6% today
• 364-day maturity
• For data center development, GPU procurement and general corporate purposes
The 364 days matters. COO Ophir Nave said it "provides additional financing to support our near-term capacity build-out," the plan that takes Nebius to ~0.9 GW by year-end and ~1.9 GW by end of 2027. He also said what comes after it: Nebius still has "asset-backed financing based on investment-grade customer commitments of more than $40 billion" of long-term contracts, which would mainly be the Microsoft and Meta deals. His line on the strategy: "Sequencing our financing is how we optimize our long-term cost of capital."
Nebius has already done one deal like that. In July it raised $775M at SOFR + 2.50%, maturing in 2030, secured on GPUs and the cash flows of an investment-grade customer contract. Together with those cash flows it covered more than 100% of the capex, and it was "significantly oversubscribed" across MUFG, ABN AMRO, Bank of America, Deutsche Bank, HSBC, Citi, Crédit Agricole, ING, Morgan Stanley and Goldman. Citi was in that group too, and is now providing a facility 4.5x the size of that whole deal.
What the rest of the AI debt market looks like right now:
• CoreWeave's 9.625% 2032 bonds are around 80 cents, a ~14.7% yield, with CDS around 1,100 bps
• Debt on Meta's Hyperion campus has fallen from above par in July to just under 92 cents
• Debt on QTS's Microsoft-leased Project Excalibur is below 88 cents, and on Oracle's Michigan campus it fell to 87
• Firmus pulled its Australian listing and SoftBank mothballed SB Energy's
• The 10-year Treasury is at 5.04%
In that market, one bank committed $3.5B to Nebius at a spread only 0.25 points wider than July's.
For comparison, IREN's Microsoft-backed GPU financing is 6.0% and its $2.4B Blue Owl and PIMCO loan is 9.0% fixed. Nebius is borrowing at close to what investment grade-backed money costs.
Nebius's funding stack now:
• $8.0B of cash at June 30
• $5.75B of converts in August, $3.45B of it at 0.50%
• $9B+ of customer prepayments expected this year, with ~70% of Q2 deals prepaying 50-60% of capex
• $775M secured in July
• $3.5B from Citi today
• Asset-backed financing on $40B+ of investment-grade contracts still to come
Secured lenders look at collateral and contracts. Nebius's Q2 deals pay back in about 22 months, and at GTC Berlin this week its CRO told CNBC it could sell all of its planned 2027 capacity immediately at current prices, and is holding some of it back on purpose.
The stock is still down ~3.5% premarket, with Nasdaq futures down ~1.6% and Brent around $112.
I'm significantly long $NBIS
$NVDA is down ~4% today and $AMD ~7.5%. Neither company has put out new numbers. What each of them last told investors:
Nvidia:
• Q2 revenue $96.2B, +106% YoY, with data center at $89.0B, +117%
• Q3 guided to $108B, excluding any China data center revenue
• Jensen: "demand is accelerating," and at GTC Berlin this week, "GPU demand has really gone through the roof"
• ~15x forward earnings, below the S&P 500's ~19x, and ~13% below its 52-week high
• Reports around November 18
AMD:
• Q2 revenue $11.5B, +50% YoY, with data center at $6.7B, +107%
• Q3 guided to ~$13B, +41% YoY
• Anthropic plans to deploy up to 2 GW of MI450 GPUs in Helios racks, and Helios customers include OpenAI, Meta, Microsoft and Oracle
• ~22% below its 52-week high
• Reports November 3
The people buying their chips aren't slowing down either. Meta's non-cancelable commitments rose by $105B last quarter, TSMC guided Q4 up 58% YoY, and Lam sees 2027 chip equipment spending above $200B.
$NVDA $AMD $SMH
$MU is ~31% below its high at ~$860 and trades at ~4.9x forward earnings. $SNDK is ~46% below its high at ~$1,261, at ~5.9x. Both fell 6-9% today. Here's what memory demand looked like this week:
• Lam's first look at 2027 equipment spending is "more than $200 billion," and the CFO expects 2027 to "continue to be constrained" by cleanroom space. Memory was 46% of Lam's systems revenue, and NAND revenue rose ~40% in one quarter
• IBM's servers and storage revenue grew 31% YoY. In July it said clients were shifting capex "toward servers, storage, and memory purchases" ahead of expected price increases
• Meta's non-cancelable commitments rose from $349B to $455B in one quarter, mostly cloud capacity, servers and network
• The Micron "strike" in Taiwan is a 24-hour warning strike by 11 union officials, with lines not halted. Micron already signed a profit-bonus deal with its Taichung union
Micron guided its current quarter to $61.5B of revenue and $38.15 of EPS, and over 75% of fiscal 2027 shipments are already committed. SanDisk guided to $10.3-10.8B and $44-46 of EPS, with $91.1B of contracted revenue, and reports on October 29.
Citadel's data shows memory EPS estimates up 25% since June 30 and the multiple down 34%, before this week.
$IREN touched $24.86 today, a new 52-week low and ~68% below its $76.87 high from last November. What has happened at IREN since that high:
• Signed Microsoft for $9.7B over five years and delivered the first 50 MW in August, with NVIDIA Exemplar Cloud status on GB300 NVL72
• Signed NVIDIA for $3.4B over five years, plus a partnership for up to 5 GW
• Contracted $4B of ARR for 2026 capacity, with management calling it "largely sold out"
• 3-year contract pricing up ~125% since November, with recent deals above $20M per MW and talks around $25M
• Energized the 1.4 GW Sweetwater 1 substation, got Sweetwater's 2 GW conditionally included as base load in ERCOT's Batch Zero, and set up IREN Europe with a planned 300 MW campus in Spain
• Reportedly signed Anthropic, per The Information, after announcing "a leading frontier AI lab" in August
At ~$10B, IREN trades at about 2.1x the $4.7B of ARR it has contracted across 2026 capacity and NVIDIA.
What I'm watching is delivery. ~40 MW was operating at June 30 against ~300 MW targeted by year-end, and Horizons 2-4 for Microsoft are due in the December quarter. Q1 results in early November are the next check.
Meta's filing today showed its non-cancelable commitments up $105B in one quarter, mostly third-party cloud capacity. IREN sells exactly that.
$NBIS is down ~7% today to ~$159, about 47% below its $299.86 high. Here's what Nebius-related news looked like on the same day:
• Citi committed a $3.5B senior secured facility at SOFR + 2.75%, roughly 6.6% today, while CoreWeave's bonds trade near 15%
• Meta's 10-Q shows its non-cancelable commitments went from $349B to $455B in one quarter, mostly third-party cloud capacity
• The same filing lists up to $14.7B of cloud capacity Meta may buy over five years, an amount that shrinks if the provider sells that capacity to other customers. That's the same structure as the up to $15B Nebius offers to others first under its Meta deal
• Nebius's CRO said this week it could sell all of its planned 2027 capacity immediately at current prices, and that the capacity auction keeps clearing higher
Nothing in that list is negative for Nebius. The stock fell with the Nasdaq-100, where 26 AI and chip names made up 93% of today's loss in value, and with Brent at ~$112 after attacks on Saudi Arabia.
At ~$44B, Nebius trades at about 1.5x the ~$29B of ARR I expect at the end of 2027, with $8.0B of cash at June 30, $5.75B of August converts, $9B+ of prepayments expected this year and now $3.5B from Citi behind the build.
I'm long $NBIS. It's my biggest position.
$NBIS $IREN $MU $SNDK $AAOI
If you're down 40-60% in AI names right now, here's the split that matters: what moved the prices, and what the companies actually reported. They point in opposite directions.
What moved the prices:
• On Feb 28, Trump ordered the start of the war with Iran. Brent hit ~$112 today, its highest since May, after attacks on a Saudi airport and an Aramco oil field, Trump saying the US isn't negotiating with Tehran, and a NYT report of plans for renewed strikes after the midterms
• September CPI came in at 3.7%, with gasoline more than half of the monthly increase. Core was 2.6%. NY Fed President Williams called tariffs "mostly in the rearview mirror" and energy "the bigger story"
• The Fed hiked in September for the first time in three years, and the 10-year went from ~3.9% in early March to 5.35% on Oct 7, the highest since 2002
• CoreWeave's bonds went to ~15%, and every company with AI debt got sold with them
What the companies reported over the same weeks:
• TSMC guided Q4 revenue up 58% YoY and raised its 2026 growth to ~44%
• ASML said its planned 2027 and 2028 supply won't fully meet demand, with customers asking about 2029 and 2030
• Lam's first look at 2027 equipment spending is "more than $200 billion," held back by cleanroom space. Asked about unconstrained demand: "It would be higher"
• TI's data center revenue grew ~95% YoY, and it isn't seeing a slowdown
• Meta raised the bottom of its capex range again, and its non-cancelable commitments went from $349B to $455B in one quarter, mostly third-party cloud capacity
• Tesla is "almost sold out of all Megapacks for 2027," citing "extreme demand from data centers"
• Nvidia guided Q3 to $108B with no China data center revenue, and Jensen said "demand is accelerating"
• Anthropic's Q3 revenue was $16.8B, more than triple Q1
• Nebius closed a $3.5B facility with Citi today, and its CRO said it could sell all of its planned 2027 capacity now at current prices
Who sold:
• Hedge funds net sold global tech at a record pace in early October, 3.3 standard deviations below normal in Goldman's data, both dumping longs and adding shorts
• Their net leverage is at a 5-year low
• JPMorgan's Panigirtzoglou says the semis selloff has already unwound most long positions, including momentum investors
The result is a crash in one factor. Goldman's high beta momentum basket is ~40% below its peak, while SPY is ~2.4% below its high. AI infrastructure estimates are up 25% since June 30 and the multiple is down 22% (Citadel, through Oct 12). Nvidia trades at ~15x forward earnings, Micron ~4.9x and SanDisk ~5.9x.
We've been here before. In July, Goldman's high beta momentum basket had its worst month since November 2000. When Situational Awareness sold its ~$16B book to Citadel in one block, Nebius rose 27% that afternoon, IREN 26.5% and SanDisk 24.6%. Micron then went from ~$830 on Aug 3 to $1,097 on Oct 1.
Some of what pushed prices down is already turning. The 10-year fell 11 bps to ~5.02% today, and the share of S&P 500 weight free to buy back stock goes from ~25% in mid-October to ~75% by early November, against a record $1.3T of buybacks authorized this year.
Next two weeks: the Fed on Oct 27-28, Microsoft on the 28th, SanDisk and Amazon on the 29th, AMD on Nov 3, AAOI on Nov 5 and IREN in early November.
$NBIS
My Nebius bull case, rebuilt around the scenario I think is most likely after today.
What came out of GTC Berlin:
Nebius's CRO told CNBC that AI compute prices keep rising faster than Nebius expected, that yesterday's capacity auction cleared higher again, and that Nebius could sell all of its planned 2027 capacity immediately at current prices. It's holding some back on purpose. Customers are asking for capacity "further and further out," he said 2028 could look the same, and supply "continues to fall far behind demand." Nebius also put its GPU spot prices online today. And Jensen named Nebius as an example of why neoclouds exist, because "every region wants to participate in the AI economy," and said "Startup companies like Nebius is doing incredibly well."
What a MW of AI compute earns right now:
• Jensen: a GW costs ~$50B and generates ~$40B a year, so ~$40M per MW
• SpaceX: slightly above $50 per watt, with payback under a year
• CoreWeave's 3-6 month deals in Q3: ~$40M per MW
• Nebius: $40-50M/MW short-term, $20-25M on its 1-3 year Q2 deals
Why I expect Nebius's late-2027 and 2028 deals to price well above Q2:
• The auction keeps clearing higher, and Nebius raised on-demand GPU prices 17-21% on Oct 1
• Musk on why SpaceX sticks to short-term contracts: "We see them renewing at higher dollars per watt, not lower dollars per watt," with H100s "renting for more than they rented when they were new"
• Vera Rubin is "in full production" and, per Jensen, "30 times greater than Blackwell," so a MW of Rubin does far more work than a MW of Blackwell
• Micron expects memory supply to be "much tighter in calendar 2027 and 2028 than they were in 2026," and every GPU needs HBM
• Under the Meta deal, Nebius offers up to $15B of capacity to other customers first and Meta buys whatever is left, so Nebius can sell it at market prices and still has a buyer of last resort
My base case:
• Management's capacity plan: ~0.9 GW by year-end, ~1.9 GW by end of 2027, ~3.1 GW by end of 2028
• This year's capacity at ~$12M/MW once fully live
• New 2027 capacity at ~$25M/MW, long-term deals at $20-25M plus the held-back part sold higher
• 2028 deals at ~$30M/MW, still 25-40% below today's short-term rates. Nebius keeps selling long-term at a discount because those deals come with prepayments that fund the build
That gives exit-2027 ARR of ~$29B, 2028 revenue of ~$42B and EBITDA of ~$27B, with payback on new capacity down from 22 months to ~18. Valued at 10x next year's EBITDA, that's ~$700 by end of 2027. At 9x, it's ~$1,100 by end of 2028. That's about 20x and 15x forward earnings, with converts counted as shares once in the money.
Stress tests on that:
• New deals stuck at Q2 pricing: ~$560 by end of 2027
• Every MW six months late: ~$540
• 8x EBITDA instead of 10x: ~$560
Bull case, with all 5 GW of contracted power online by 2029 and new deals at ~$40M/MW by 2028: ~$1,050 by end of 2027 and ~$1,800 by end of 2028.
What the market pays today: about 4x consensus 2027 revenue of $12.3B and ~1.7x the ARR I expect at the end of 2027, with Street 2027 EPS still negative.
How it's funded: $8.0B of cash at June 30, $5.75B of converts in August ($3.45B at 0.50%), $9B+ of prepayments expected this year with ~70% of Q2 deals prepaying 50-60% of capex, and one secured facility of $775M.
Track record:
• ARR went from $1.9B to $3.0B in one quarter
• Q2 deal value grew nearly 4x
• Every Microsoft tranche delivered
• Platinum in SemiAnalysis's ClusterMAX, a tier it shares only with CoreWeave
• First AI cloud to adopt Groq 3 LPX, and Token Factory inference workloads more than tripled in Q2
Much of today's price is CoreWeave's bonds. Nebius fell 25.2% last week, about as much as CoreWeave, without having publicly traded CDS.
I'm long $NBIS. It's my biggest position.
@EndicottInvests@daniel_koss@Sandeman52@SMASIMHO I'd value your take, especially on the pricing. A repost helps if you think it's worth reading.
$BE reports after the close today, with the call at 5 p.m. ET. What the bar looks like:
• Street for Q3: ~$1.07B of revenue and ~$0.65-0.69 of EPS. Q2 was $1.065B, so the Street has the quarter flat
• 2026 guide: $3.9-4.2B of revenue, $800-900M of non-GAAP operating income and $2.55-2.85 of EPS
• H1 revenue was $1.82B, so the guide implies $2.08-2.38B in H2. Street's Q3 and Q4 add up to ~$2.30B, already near the top of the range
• Bloom has beaten revenue and EPS estimates four quarters in a row, and Q2 revenue came in more than $200M above the Street
What I'm watching: another guidance raise, data center orders and how many of the hyperscalers and neoclouds that have validated Bloom's systems are now in backlog, and anything on 2027. The demand backdrop hasn't changed this week, with Musk saying the constraint on deploying AI is "more in power and cooling" than chips.
$LRCX is down ~8% premarket after a record quarter, and the part that matters for memory holders got lost in the selloff.
• Revenue $8.22B, up 54%, with a first-ever 40%+ operating margin
• Memory was 46% of systems revenue, memory systems revenue was up 120% from a year ago, and NAND revenue rose ~40% in one quarter
• Preliminary 2027 WFE: "more than $200 billion", up from roughly $150B this year
• December guide of $8.2-9.0B, held back by "near-term supply chain constraints"
The key lines came from the CFO. He expects 2027 to "continue to be constrained" by cleanroom space and supply chains, and when asked what demand would look like unconstrained: "It would be higher." The CEO said the same limits keep chipmakers and equipment companies from being able "to fully meet end demand."
So chipmakers plan to spend more than $200B next year and would spend more if they physically could. The bear case is that this much equipment eventually means a lot more bits. What Lam described is a 2027 bottleneck in cleanrooms, and new cleanrooms take years to build.
I'm long $MU $SNDK
$NBIS
Nebius just signed a $3.5B senior secured facility with Citi, while AI infrastructure debt is selling off across the board.
The terms:
• $3.5B, with Citi as mandated lead arranger, agent and security agent
• Term SOFR + 2.75% to start, capped at SOFR + 3.50%. With SOFR around 3.9%, that's roughly 6.6% today
• 364-day maturity
• For data center development, GPU procurement and general corporate purposes
The 364 days matters. COO Ophir Nave said it "provides additional financing to support our near-term capacity build-out," the plan that takes Nebius to ~0.9 GW by year-end and ~1.9 GW by end of 2027. He also said what comes after it: Nebius still has "asset-backed financing based on investment-grade customer commitments of more than $40 billion" of long-term contracts, which would mainly be the Microsoft and Meta deals. His line on the strategy: "Sequencing our financing is how we optimize our long-term cost of capital."
Nebius has already done one deal like that. In July it raised $775M at SOFR + 2.50%, maturing in 2030, secured on GPUs and the cash flows of an investment-grade customer contract. Together with those cash flows it covered more than 100% of the capex, and it was "significantly oversubscribed" across MUFG, ABN AMRO, Bank of America, Deutsche Bank, HSBC, Citi, Crédit Agricole, ING, Morgan Stanley and Goldman. Citi was in that group too, and is now providing a facility 4.5x the size of that whole deal.
What the rest of the AI debt market looks like right now:
• CoreWeave's 9.625% 2032 bonds are around 80 cents, a ~14.7% yield, with CDS around 1,100 bps
• Debt on Meta's Hyperion campus has fallen from above par in July to just under 92 cents
• Debt on QTS's Microsoft-leased Project Excalibur is below 88 cents, and on Oracle's Michigan campus it fell to 87
• Firmus pulled its Australian listing and SoftBank mothballed SB Energy's
• The 10-year Treasury is at 5.04%
In that market, one bank committed $3.5B to Nebius at a spread only 0.25 points wider than July's.
For comparison, IREN's Microsoft-backed GPU financing is 6.0% and its $2.4B Blue Owl and PIMCO loan is 9.0% fixed. Nebius is borrowing at close to what investment grade-backed money costs.
Nebius's funding stack now:
• $8.0B of cash at June 30
• $5.75B of converts in August, $3.45B of it at 0.50%
• $9B+ of customer prepayments expected this year, with ~70% of Q2 deals prepaying 50-60% of capex
• $775M secured in July
• $3.5B from Citi today
• Asset-backed financing on $40B+ of investment-grade contracts still to come
Secured lenders look at collateral and contracts. Nebius's Q2 deals pay back in about 22 months, and at GTC Berlin this week its CRO told CNBC it could sell all of its planned 2027 capacity immediately at current prices, and is holding some of it back on purpose.
The stock is still down ~3.5% premarket, with Nasdaq futures down ~1.6% and Brent around $112.
I'm significantly long $NBIS
I have them at ~$29B of ARR exiting 2027 in my base case and up to ~$38B in my bull case, and that's mostly at long-term contract pricing. If half of the capacity goes through spot and auction at today's $40-50M per MW, the base case is too low.
Management and the Nebius team execute better than everyone else. Simply incredible, and the upside over the next few years is generational. $NBIS
Yeah it's insane. I don't know why people are counting on them when you look at this:
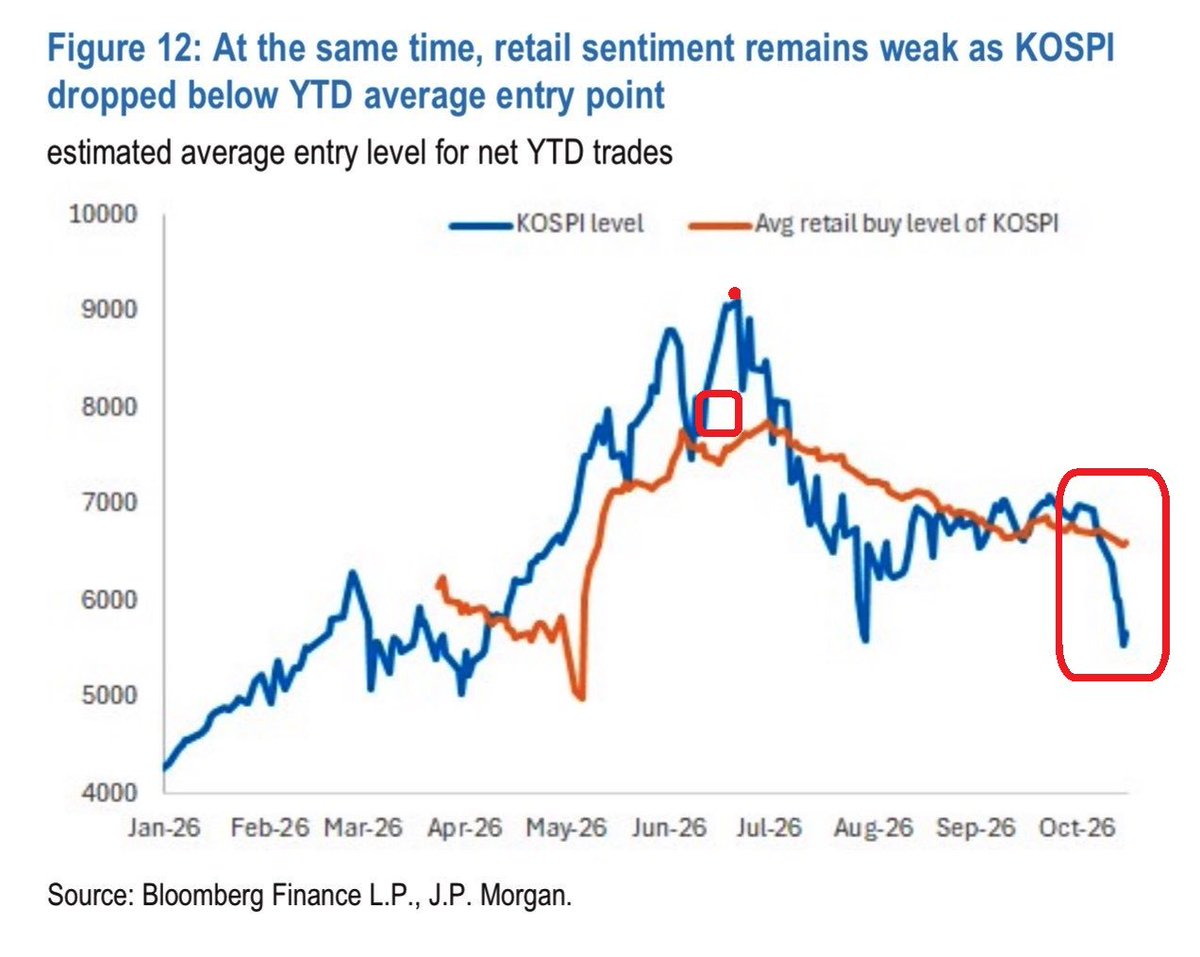
South Korean retail investors are DEEP UNDERWATER:
The KOSPI Index dropped below the estimated average entry level of retail investors' net purchases this year, with the index down to ~5,700 versus an average entry level of approximately 6,550.
This implies an unrealized loss of approximately -13% for retail investors.
This also marks a sharp reversal from June, when the KOSPI surged above 9,000, way above retail investors' average buying level of around 7,800.
Notably, this does not include the massive leveraged bets undertaken by mom-and-pop investors, which have amplified the losses.
Retail investors in South Korea have been CRUSHED.
I doubt they'll be of much help:
South Korean retail investors are DEEP UNDERWATER:
The KOSPI Index dropped below the estimated average entry level of retail investors' net purchases this year, with the index down to ~5,700 versus an average entry level of approximately 6,550.
This implies an unrealized loss of approximately -13% for retail investors.
This also marks a sharp reversal from June, when the KOSPI surged above 9,000, way above retail investors' average buying level of around 7,800.
Notably, this does not include the massive leveraged bets undertaken by mom-and-pop investors, which have amplified the losses.
Retail investors in South Korea have been CRUSHED.
$SPY $QQQ $AAPL $MU $SNDK
Companies were mostly locked out of buying back their own stock during the selloff.
Only about 25% of S&P 500 weight was outside its buyback blackout in mid-October. Citadel's estimate has that rising to about 75% by early November and over 90% by late November.
US companies have authorized a record $1.3T of buybacks this year, 8% ahead of last year's record pace, and $573B of it is tech.
$SOXL $NBIS $MU $IREN $NVDA
$AMD
While hedge funds were dumping tech, retail went the other way:
• Retail net bought $9.1B of US stocks the week of Oct 12, the most in 15 weeks, including $2.6B of semis, $2.4B of AI infrastructure and $700M of neoclouds, the most Citadel has ever seen go into neoclouds in a week
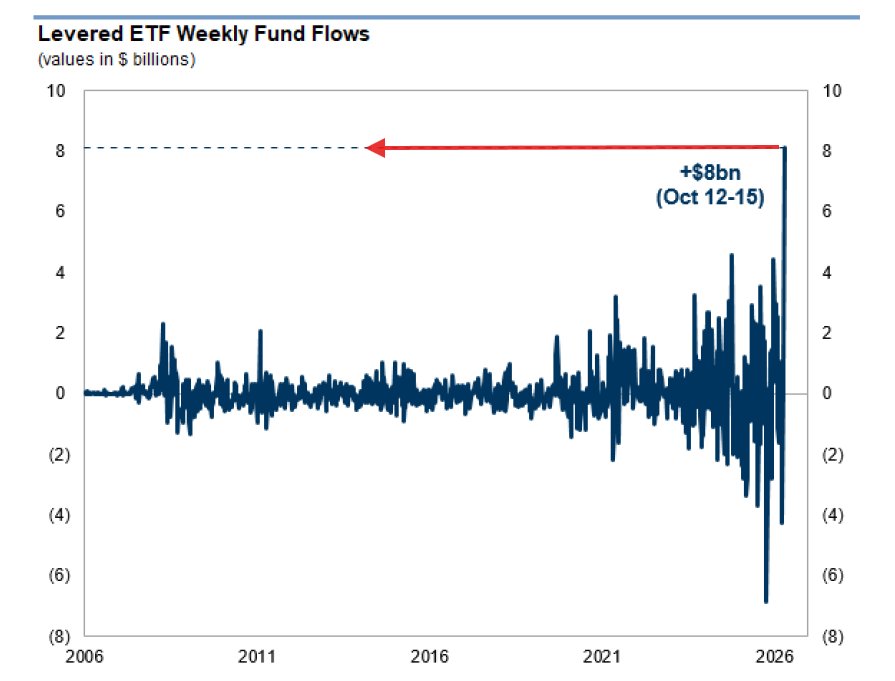
• More than $8B went into leveraged ETFs in four days, the largest weekly inflow in Goldman's data going back to 2006. SOXL alone took in ~$6B while its index fell 11%
• BofA's private clients have a record 66.4% of their assets in stocks and a record-low 9.3% in cash
Hedge funds are the least net long in five years. BofA's private clients have never held more stocks or less cash.
$QQQ $NDX $NVDA
The Nasdaq-100 traded at 16.7x forward earnings on Oct 16 (Bloomberg). That's below every low of the 2022 bear market and the cheapest since March 2020.
In 2022 the Fed was hiking at the fastest pace in four decades and earnings estimates were coming down. This time FactSet has Tech earnings growing 65% in Q3 and 53.5% for all of 2026.