Warren Buffett: "Even if the stock price drops by 50%, there’s no need to panic."
Investor: "What should I do if the stock price falls by 50%?"
Buffett: "First, you have to understand what a stock actually is."
Investor: "What do you mean by that?"
Buffett: "If you buy a stock, you must be mentally prepared for the possibility that it could drop by more than 50%."
Investor: "But wouldn't that mean my wealth has been cut in half?"
Buffett: "Exactly."
Investor: "Doesn't that make people afraid—and tempted to sell?"
Buffett: "In fact, Berkshire’s own stock price has fallen by about 50% on three separate occasions in the past."
Investor: "Even Buffett’s own company?"
Buffett: "Yes."
Investor: "And during those periods, was the company still performing well?"
Buffett: "There was nothing wrong with the company’s actual business operations."
Investor: "Then why did the stock price crash?"
Buffett: "Because stock prices and business value do not always move in sync."
Investor: "Even so, a drop like that is still pretty terrifying."
Buffett: "That is precisely why you should never borrow money to buy stocks."
Investor: "Why not?"
Buffett: "Because if the price drops, you won't be able to handle it."
Investor: "So, when exactly should one buy?"
Buffett: "No one can pinpoint the absolute bottom. No one can."
Investor: "Does that mean buying today might not necessarily be the right decision?"
Buffett: "Of course."
Investor: "Then why do you invest at all?"
Buffett: "Because I take a long-term view—spanning 20 or even 30 years."
This is a question every investor should reflect on at least once.
Of course, this doesn't mean you should hold onto every stock no matter what.
If a company’s performance or prospects deteriorate, you should consider selling.
However, many people rush to sell simply because the stock price has fallen. The hardest part of investing is not buying at the bottom or selling at the top. Rather, it is about being able to calmly evaluate the companies you trust, even during times of market turbulence.
In my view, it is precisely when the market crashes that an investor’s true mindset is put to the ultimate test.
( lf this helps you, like + follow + share. )
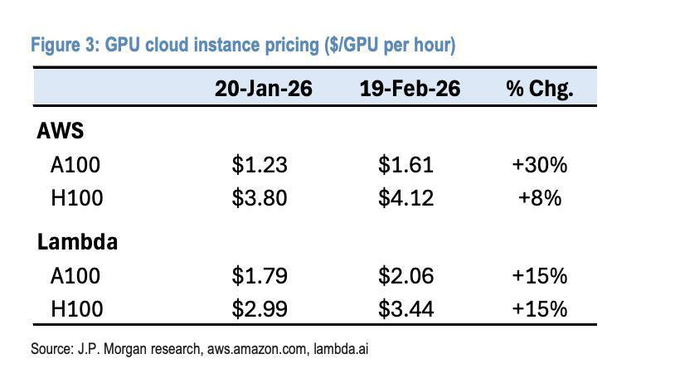
Who said older GPUs are worth less? The money-making cycle on GPUs is longer than the market thinks.
$IREN
just disclosed H100 re-sign pricing hit twice the prior level.
$CRWV
has about 300k GPUs with re-sign opportunity. A lot of contracts expire in 2027–2028. The commercial logic people are missing. For a lot of enterprises H100 is already enough for mature inference, model fine-tuning, and some agent work. Instead of waiting for more expensive new cards they can just rent existing compute. GPU market is splitting into layers. Frontier training uses GB300, Rubin. Large inference uses B300, GB300. Enterprise AI and mature inference keep choosing B200, H100, H200 based on cost and performance. First round of contracts helps recover the GPU purchase cost. Second round, if rent stays high, can keep generating revenue with lower incremental CapEx. IRENs current asset mix looks healthy. Repricing old H100s on one side, expanding B300 and GB300 on the other.
Adding more to my $IREN position.🔥🔥
In pre-market trading, the share price has climbed to $21—a gain of 7.8%—showing strong momentum. I am very bullish on the future potential of $IREN.
The entire "neocloud" (next-generation cloud services) sector is heating up, and $IREN is right at the heart of this wave. If you also hold $IREN, feel free to follow me.
I will continue to share the latest updates and key information. Things are looking increasingly promising.
Adding more to my $IREN position.🔥🔥
In pre-market trading, the share price has climbed to $21—a gain of 7.8%—showing strong momentum. I am very bullish on the future potential of $IREN.
The entire "neocloud" (next-generation cloud services) sector is heating up, and $IREN is right at the heart of this wave. If you also hold $IREN, feel free to follow me.
I will continue to share the latest updates and key information. Things are looking increasingly promising.
🔥 VALUING $IREN AT $4B ARR IS COMPLETE INSANITY!
Assuming 423M shares outstanding, here's what different valuation multiples could imply:
🔥 3x ARR = $28.37/share
🔥 4x ARR = $37.83/share
🔥 5x ARR = $47.28/share
🔥 6x ARR = $56.74/share
Even at just 4x ARR, the implied share price is nearly $38.
And remember, IREN's $4B+ ARR target is already contracted and funded, with operations targeted for early 2027.
The real question isn't whether AI compute demand exists.
It's how much the market will eventually be willing to pay for IREN's growing AI Cloud business.
The upside scenarios are getting VERY interesting. 🚀
#IREN #AI #AIInfrastructure
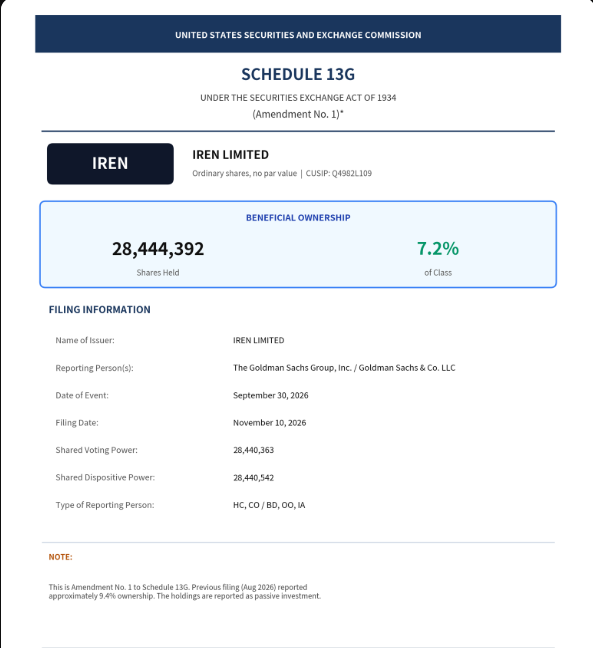
JUST FILED: Goldman Sachs Group, Inc. disclosed a 7.2% beneficial ownership stake in IREN Limited, holding 28,444,392 ordinary shares as per a Schedule 13G/A filing.
THE BULL CASE FOR $IREN IS GETTING STRONGER!🔥
Three major developments are worth paying attention to:
1️⃣ H100 PRICING JUST DOUBLED
IREN signed new H100 contracts at 2x the pricing of its previous Prince George contract.
Older GPUs are NOT becoming worthless overnight. Demand exists across multiple generations of AI compute.
2️⃣ B200 & B300 ARE EXPANDING THE OPPORTUNITY
IREN is positioning itself for next-generation GPU demand, with NVIDIA GB300 NVL72 Exemplar Cloud status already achieved.
It can monetize both existing H100 capacity and newer, higher-performance systems.
3️⃣ MIRANTIS ADDS THE SOFTWARE LAYER
IREN already has the power, data centers and GPUs.
Mirantis adds AI workload orchestration, deployment, monitoring and enterprise support.
That means IREN is evolving beyond simply renting GPUs toward becoming a more complete AI Cloud platform.
And the latest numbers make the story even more interesting:
🔥 3-year contract pricing: +11%
🔥 5-year contract pricing: +12%
🔥 A new 5-year deal with 90% of associated GPU CapEx prepaid
Customer prepayments can dramatically reduce IREN's upfront GPU funding burden.
My takeaway: IREN isn't just expanding its GPU fleet. It's building a platform that can monetize multiple GPU generations, improve utilization and serve a broader enterprise customer base.
The combination of pricing power, next-gen compute and software integration could be a major long-term growth driver.
I'm increasingly bullish on the bigger picture. 🚀
#IREN #AI #NVIDIA #AIInfrastructure
$IREN just got linked to one of the most important AI labs on the planet.🔥
The Information reports Anthropic has signed an unannounced multiyear cloud deal with IREN.
This is very likely the same “leading frontier AI lab” IREN quietly added in August — the one they refused to name.
While Microsoft and NVIDIA already anchor the majority of their backlog…
Anthropic would add the purest frontier-model demand in the market.
Anthropic is racing to lock power and capacity.
IREN already owns the scarce grid connections and land.
No official confirmation yet.
But when a top-tier lab chooses a former Bitcoin miner for multi-year compute, it’s not random.
Customer quality is improving.
Backlog quality is improving.
The market is still pricing pure execution risk.
I’m watching this closely.
Follow me for the AI infra developments that actually matter.
Still early on $IREN?
📌 GOLDMAN SACHS CUTS $IREN PRICE TARGET FROM $50 TO $30!
The positives:
✅ EBITDA beat expectations
✅ Improving AI pricing trends
✅ Greater CapEx flexibility
The concerns:
⚠️ Execution and financing risks
⚠️ $4B+ ARR target pushed to Jan/Feb 2027 due to customer-requested design changes and supplier delays.
The debate is clear: strong AI demand and pricing vs. execution and funding risks.
Can IREN deliver on its massive AI infrastructure opportunity?
#IREN #AI #Stocks
🚨 GOLDMAN SACHS SEES UPSIDE IN $IREN!
“IREN stock should trade higher given the EBITDA beat and positive pricing developments.”
Key drivers:
🔥 Adjusted EBITDA beat expectations.
🔥 Stronger pricing on new AI infrastructure deals.
🔥 Growing value per MW.
Wall Street is starting to recognize the strength of IREN’s AI Cloud business.
The fundamentals are sending a signal. Don't ignore it. 🚀
🚨 $34.9 BILLION ANTHROPIC DEAL NOW AT RISK!
Anthropic’s massive compute deal with Lambda is now terminable by either party after Lambda missed a key facility lease deadline.
Key details:
• $34.9B agreement now eligible for termination.
• Represents 85% of Anthropic’s $41.3B Lambda commitments.
• Payments only begin as GPU capacity is delivered and accepted.
• Neither side has issued a termination notice.
• Anthropic says it currently has no intention of ending the deal.
The bigger picture: AI demand is massive, but securing power, data centers, and GPU capacity remains a major challenge.
The AI infrastructure race is about execution, not just capital. 🚀
$NVDA
🚨 ANTHROPIC’S IPO COULD CREATE 4,250 NEW MILLIONAIRES!
According to estimates from private-market platform Hill, roughly 4,250 Anthropic employees could become millionaires following the company's IPO.
That's nearly 80% of its 5,300-person workforce!
One IPO. Thousands of potential millionaires.
The AI boom is creating wealth on an extraordinary scale. 🤯🚀
🚨 ANTHROPIC IPO MOMENTUM IS BUILDING — BIG NEWS AHEAD FOR $IREN?
Anthropic is pushing ahead with its IPO plans.
Meanwhile, IREN could have another major catalyst ahead, with details of its reportedly multi-year Anthropic deal potentially emerging this month.
Could we also see an expansion of the partnership?
Keep $IREN on your radar. The AI infrastructure story is far from over. 🚀
🚨 GOLDMAN SACHS SEES UPSIDE IN $IREN!
“IREN stock should trade higher given the EBITDA beat and positive pricing developments.”
Key drivers:
🔥 Adjusted EBITDA beat expectations.
🔥 Stronger pricing on new AI infrastructure deals.
🔥 Growing value per MW.
Wall Street is starting to recognize the strength of IREN’s AI Cloud business.
The fundamentals are sending a signal. Don't ignore it. 🚀
🔥 $IREN MAY BE PUSHING TOWARD 100% CUSTOMER-FUNDED GPU BUILDS.
Dan has rarely sounded this confident.
“The key question for us is how much of the funding of this buildout can we get these customers to pay for?”
As of Q1 FY2027, Anthropic had already prepaid 90% of GPU CapEx.
If IREN can push future deals toward 100% prepayment, that could dramatically reduce its capital burden.
Customers fund the buildout. IREN scales faster.
That's a powerful business model. 🚀
$IREN position update: I added another 2,000 shares at the market open today! I am extremely bullish on IREN’s potential. The company’s latest earnings report shows explosive growth in its AI Cloud business—with quarterly revenue nearly tripling—along with an order backlog exceeding $20 billion. They continue to aggressively expand their data center footprint and computing capacity. While there have been some short-term adjustments to delivery timelines, the long-term demand for AI infrastructure remains robust, offering massive room for growth. I am holding firm and continuing to increase my position. If you also hold IREN, feel free to follow me for future updates!🔥
$IREN #IREN #AICloud
$IREN position update: I added another 2,000 shares at the market open today! I am extremely bullish on IREN’s potential. The company’s latest earnings report shows explosive growth in its AI Cloud business—with quarterly revenue nearly tripling—along with an order backlog exceeding $20 billion. They continue to aggressively expand their data center footprint and computing capacity. While there have been some short-term adjustments to delivery timelines, the long-term demand for AI infrastructure remains robust, offering massive room for growth. I am holding firm and continuing to increase my position. If you also hold IREN, feel free to follow me for future updates!🔥
$IREN #IREN #AICloud
$IREN $NBIS $MU $SNDK 🔥🔥
I have carefully studied a report from the Nomura storage team regarding the impact of the midterm elections.
There is no federal-level ban.
Any potential restrictions would only arise at the state level; yet, in states with a high concentration of data center infrastructure, no elected governor has committed to implementing a permanent ban.
Capacity through 2027 is essentially locked in.
All capacity slated to come online next year is already under construction.
The real uncertainty lies in 2028: approximately 7% of new global capacity could face delays—rising to about 11% in a pessimistic scenario—but note that these are "delays," not "cancellations."
Project delays will further drive up GPU rental rates, which are already on an upward trajectory—just look at the spot prices for NBIS.
Rising compute costs will compel companies to accelerate their upgrades to newer-generation GPUs; therefore, a slowdown in construction could actually be a tailwind for chip demand.
The storage market is also unlikely to face a supply glut.
Thanks to long-term supply agreements, storage vendors can adjust supply volumes more than two years in advance, meaning any potential impact in 2028 will likely be far milder than the market fears.
Demand will not simply vanish; instead, it will shift to more policy-friendly states or overseas, forcing existing data centers to increase their operational intensity and driving up the cost paid per gigawatt (GW).
The true risk lies in valuation discounts driven by market sentiment—a situation that could persist until the Texas legislative session concludes in May 2027. This is particularly relevant for companies with heavy exposure in Texas and high leverage.
In short, compute resources—already scarce—are becoming even scarcer.
If you possess operational data center capacity, along with the necessary chips and storage resources, you are in an excellent position to profit.
Bullish —MarcusWallSt ⚡
$IREN
CEO underestimated
$IREN 🔥
8 months ago, he explicitly said: "In our view, [we] can roughly generate $10M per MW versus 1.5 to $2M in colocation." Yet,
$IREN
just signed: 1. 5Y deal at $22M per MW. 2. 3Y deal with Anthropic at $40M per MW including funding 90% of the GPU CapEx. $100M to $150M per MW by 2028 is highly likely.
🚨AST SpaceMobile and Rakuten Form Joint Venture
The two companies are establishing a joint venture, "Rakuten AST," aimed at building a sovereign "Direct-to-Device" (D2D) satellite network in Japan.
🇯🇵 The project has secured up to 148 billion JPY (approximately 1 billion USD) in funding from the Japanese government to support network deployment.
🛰️ AST will provide satellites for a low Earth orbit (LEO) constellation, operating in mid-band spectrum exclusively for Japan.
🤝 Ownership structure: Rakuten will hold a 51% stake, and AST will hold 49%.
📡 Operations in Japan are scheduled to begin by March 2029, enabling direct connectivity between satellites and standard smartphones—supporting services such as video streaming and broadband internet access.
🛡️ The network is designed to enhance Japan’s communication resilience during natural disasters and facilitate emergency roaming between mobile carriers.
🌍 Any capacity exceeding Japan’s domestic requirements can also be made available to AST’s global customer base.
AST is helping to build a government-backed, sovereign satellite infrastructure network. The project is being implemented in one of the world’s major economies and is supported by approximately 1 billion USD in public funding.
This serves as further compelling evidence of the technology's viability and the importance of strategic partnerships. 🚀
$ASTS