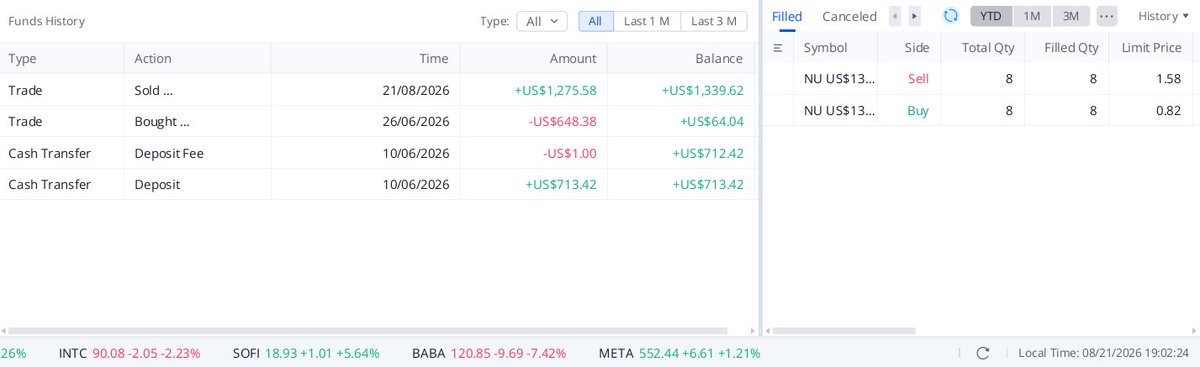
Today marks the day I closed my first ever call option.
I bought the call on the 26th of July for $648.38.
Today I closed it out at 96.73% profit.
The call was on NU holdings and priced at $13. NU is currently sitting at $14.70.
I learnt a lot from this call, and the main thing was patience. Although with that being said, my call was up 230% at a stage and I didn't take the profits in hope of more. Hopefully next time I get out a better time.
But for my first ever call, I think it was a good call. Haha, get it?
Side note: I also hold NU in my portfolio, currently weighted around 10% of my USD portfolio.
JSE TOP 40 BIGGEST MOVERS TODAY (-1.75%)
GREENIES🟢
1. Sasol: +1.89%
2. British American Tobacco: +1.77%
3. Shoprite: +0.87%
REDS🔴
1. Harmony Gold: -5.42%
2. FirstRand: -4.55%
3. Valterra Platinum: -3.10%
I hold Shoprite, FirstRand and Valterra. JSE got smoked today lol, no surprises though, it's just another day for the JSE.
Naspers valuation coming soon...
BRAIT - MY VALUATION
Brait (JSE: BAT): a holdco in wind-down where one unlisted gym chain is the entire valuation, and the company carries it 1.5 turns above where the market does.
Summary
Current price: R1.96 (JSE close, 5 Oct 2026)
Shares: 5,518.3m (post R2.5bn rights offer at R1.51, Aug 2026)
What it is: Virgin Active (61.3% pro forma, unlisted, listing targeted 2027-28), ~19% of Premier (JSE), New Look PIK loans. Valued look-through, not off Brait's own accounts.
INTRINSIC SHARE VALUE SUMMARY
Peer holdco-discount SOTP: R1.35 (cross-check, excluded)
Wind-down SOTP, VA at DCF: R1.60
Wind-down SOTP, VA at comps: R2.23
Monte Carlo median: R2.23 · P5–P95 R1.58–R2.99 (cross-check - excluded)
Gross SOTP, no costs or time: R2.41 (upper marker - excluded)
Brait reported NAV, rolled: R2.58 (reference - excluded)
DDM / P/E / RI on Brait's books: excluded - no dividend, and the book IS the NAV, so it's circular
Mean price: R1.92
Median price: R1.92
Values in cents, not whole rand - on a sub-R3 share, whole-rand rounding collapses every method to R1 or R2.
Read the range, not the midpoint - and know what the range actually is. My two in-median methods share 15 of their 17 SOTP lines: Premier, the debt, the holdco costs, the bond claim are identical in both. The only input that differs is how Virgin Active is marked. So R1.60–R2.23 isn't two methods disagreeing, it's the Virgin Active question asked twice. That's also why I won't lean on the R1.92 midpoint - averaging two readings of one input doesn't make that input any more certain.
On the same LTM EBITDA basis, the market pays 8.1x for Virgin Active, Brait marks it at 9.6x, and my DCF supports 6.8x. Brait's headline figure is 9.0x, but that's struck on "maintainable" EBITDA of £122m rather than the £114m statutory LTM - so part of the discount people quote is a definition, not a disagreement. On either basis the company-to-market gap is about 1.5 turns.
The listed gyms don't settle it. Life Time trades at 11.6x. Gym Group and Basic-Fit average 6.8x. That 4.8-turn spread between premium and low-cost is the whole valuation, and I've put VA halfway with a 50/50 weight that is a judgement, not a measurement. Move it to 75% Life Time and you get R2.54. Move it to 25% and you get R1.93.
Bull 🟢
The deleveraging is real and mostly done. Virgin Active raised £175m, Brait funding £108m of it out of the R2.5bn rights offer, taking VA to about 2.0x net debt to maintainable EBITDA. The GBP convertibles were called for redemption on 15 September for £138.5m. Premier grew FY26 EBITDA 18% to R2.8bn - and RFG consolidated only 21 days of that, so it's close to organic - and it's marked at market daily rather than guessed at. This is a wind-down, not a perpetual holdco, so the discount should close as assets are actually distributed, which is why I don't apply a permanent one. Bull case R3.13, strong bull R4.00.
Bear 🔴
My own DCF says R1.60, and it is not a harsh one. It already assumes VA's EBITDA margin climbs from 17.4% actual at Dec-25 to 22.0% by 2031, and 74% of its value sits in the terminal. Hold margins flat and it goes lower. My own selected 9.2x multiple implies 6.5% perpetual GBP growth when you solve it backwards - on the Life Time multiple it's 7.5% - and neither is a number I'd defend out loud. 57% of VA's EBITDA is South African, so rand strength cuts the rand NAV even when the business is fine. Doubling exit friction from my 7.5% base to 15% costs R0.15 a share. R2.1bn of exchangeable bonds sit outstanding at a R2.03 exchange price: debt today, dilution if the share runs. And the severe-bear case, with the listing slipping to four years and a fire-sale exit, is R0.76.
Verdict
Fairly priced, and I'd rather own the range than the midpoint. R1.96 sits inside R1.60–R2.23, a touch above the R1.92 middle. Buying BAT here is a bet that Virgin Active lists at a premium-gym multiple - not a bet on a discount to NAV. That "40% discount" headline overstates the case twice over: reported NAV carries the exchangeable bonds at IAS 32 book, below what it will cost to settle them, and it marks VA on an EBITDA definition the market isn't using.
Personal
I decided to value Brait because there has been a lot of chatter around them. I have held shares and I have never done any research on them. What I have gotten from this is, it's basically all on Virgin Active. Virgin Active IPOs in late 2027/2028, if the market pays a higher price (views VA as a premium service), buying now would be great. If the market views VA as cheap, crusty gyms, you're done for.
I'm going rant about gym stuff now so be prepared. I have been gyming at Virgin Active for 6 years now. Rosebank, Old Eds, Victory Park, Boksburg, Hatfield, Groenkloof, Loftus, etc. I do not think VA is a premium gym. Majority of VA's have been redone recently and yes, they look better and have newer equipment, but most of them use some of the cheapest and "least optimal" equipment, Technogym.
For an avid gym rat like myself, I notice these things, but 99% of gymgoers wouldn't be able to tell the difference. And even though I know Planet Fitness's have better equipment in general, it is not that big of a deal. Also, old habits die hard, changing now would be changing who I am. And, VA staff > PF staff.
One problem though, VA rates have been getting more and more expensive every year. There is not a single VA membership that is cheaper than the equivalent membership at PF, when not including discounts from insurance.
What do you think? Buy, Sell, Hold? Opinions would be greatly appreciated.
Not advice. DYOR.
PEPKOR - MY VALUATION
Pepkor (JSE: PPH): five methods, and the one that sets the answer is the one that just reads what the peers trade at.
Summary
Current price: R17.81
Shares: 3,703 million
Mkt Cap: R66.0bn
INTRINSIC SHARE VALUE SUMMARY
Tangible NAV: R4 (asset floor/reference)
DDM (policy payout): R7
Residual income: R10
Justified P/B: R10 (reference)
Comps (P/E + EV/EBITDA): R14
DCF - FCFF: R16
SOTP: R16 (= FCFF, excluded)
NAV - book: R18 (reference)
DCF - FCFE: R18
Monte Carlo: R16 (P5–P95 R12–R19) (cross-check)
Mean price: R13
Median price: R14
The median sits 22% below the price. But read how it got there before you use it.
My five methods split into three camps: cash flow to the firm (R15.87), book and cost of equity (R10.13), and peer multiples (R13.86). Comps lands between the other two, so it sets the camp median - and it's the middle of the five, so it sets the house median too. Both medians are the same number, and that number is Comps. Which means my headline is really "Pepkor
priced off its peers," not a consensus of independent methods.
And that peer reading is thin. The median P/E of 7.15x is set by TFG alone. The median EV/EBITDA of 5.11x is set by Mr Price alone. Drop Mr Price from the EV leg and Comps goes to R14.80; carry Lewis on it instead and Comps goes to R12.20. One peer either way moves the headline more than most of my drivers do.
So here's the bear point that doesn't need the peer set at all.
Pepkor earns 9.1% on its full capital base, including the goodwill from everything it has bought. Its cost of capital is 12.6%. To justify R17.81, my DCF needs the company to earn about 25.4% on every new rand it invests, forever. The defensible range from Pepkor's own numbers is 9.1% to 20.2%.
The price sits outside it and it still does at any price above R10.60.
Bull 🟢
FCFE at R18.07 is the one method above the price, and the Monte Carlo scan centres near R16 with a P95 of R19.49. The dividend is real and covered about 3x. Fintech and the credit books are growing fast and the market may be paying for that optionality. And the peer multiples themselves are depressed - SA apparel de-rated 20–46% over the year while Pepco re-rated +77%. A sector re-rate lifts Comps directly.
At 5.6x EV/EBITDA Pepkor is not on a demanding multiple.
Bear 🔴
Returns below the cost of capital on the full capital base is the whole problem: on everything it has invested, acquisitions included, Pepkor isn't earning its cost. The price needs roughly 25% perpetual returns on new capital, outside any band its own numbers support. Every method except FCFE is below R17.81. And a growing share of profit comes from lending to lower-income customers - that's a credit cycle, not an annuity.
Verdict
On this model Pepkor looks fully priced to over-valued, with an intrinsic median around R14 against R17.81. But I'd rather you took the terminal-ROIC test than the median: the median leans on two single peers, while the returns-below-cost-of-capital finding holds whatever the peer set does, and holds at any price above R10.60. The bull case is a re-rate plus fintech optionality. The bear case is arithmetic.
Personal
I have held Pepkor in my portfolio for over a year, and this is the first valuation I have ran for it and I was not expecting these results. Btw this valuation took me, Claude and ChatGPT more than 30 hours and a ridiculous number of credits. The numbers don't look great for Pepkor, but, their movement into the Fintech sector is going to be make or break. I am personally going to keep holding.
What is even attractive on the JSE right now? Our market has been so bad the whole year, every JSE stock feels like a gamble. I have really struggled to be confident in any JSE related decisions lately.
With that being said, I added some ABSA to my portfolio today.
Any opinions on this would be hugely appreciated thanks.
Not advice. DYOR.
@ThinkFoYourself Interesting take. I have actually heard quite a bit of chatter about Brait. I like Pepkor of course I hold it. I wouldn't touch Spar though.
JSE
What is your top pick on the JSE right now???🟢
Personally, the JSE has let me down this whole year, so I am very cautious about our SA market. There have been many outside factors affecting the market of course. But still, caution is on my mind. My top pick for stable growth and protection would be ABSA, possibly Growthpoint Properties just because they have pulled back from their highs a decent amount.
If I was looking for some impressive growth and risk, Bytes Technology. Disclaimer I held them earlier this year and sold after getting some nice profit(+31%), but I wish I kept holding, they've done very well this year (since Feb/March). Earnings on the 13th of October. If the outlook is positive, I will be loading up on them.
What company are you staying away from???🔴
Personally, I would be very cautious around Sasol for obvious reasons (it's priced for a continuing war). I would also be very cautious around Naspers because of the Chinese deflationary environment. Although, if China starts showing signs of growth and a positive outlook, Naspers would be a very strong buy at these prices.
DYOR. Not financial advice.
Would love to hear your opinions🙏
Honest answer: there isn't one.
Mr Price is closest on the retail side and sets my EV/EBITDA median at 5.11x on its own. TFG sets the P/E median at 7.15x on its own. Two single peers carry the whole number.
The credit-heavy names can't go on the EV leg — Lewis's interest and insurance income less debtor costs is roughly its entire operating profit, so an EV/EBITDA on it is a multiple on a lending book. But Pepkor's own EBITDA includes its fintech and credit books and I didn't carve those out either, so I'm pricing a retailer-plus-lender off a pure retailer's multiple.
What it's worth: drop Mr Price from the EV leg → R14.80. Carry Lewis on it → R12.20. Against a R13.86 base. That's why the terminal-ROIC test is the part of the post I'd actually lean on.
JSE TOP 40(-0.61%) BIGGEST MOVERS TODAY
GREENIES🟢
1. Impala Platinum: +2.24%
2. Valterra Platinum: +1.24%
3. Glencore: +0.81%
REDS🔴
1. Pan African: -4.48%
2. Investec plc: -3.57%
3. Investec Lmtd: -3.54%
I hold Pan, Valterra and Glencore. Another rough day for me(-0.94%) and the JSE 💔. How'd you do today?