External Marketing, Sales and Operations Consultant of Bilbel Capital. Like/ RT ≠ endorsement. Tweets not Financial/investment advice. Views are my own.
@bilbelcapital's 2026 Semi-Annual Letter is out!
Returns since inception (February 2022):
Bilbel Capital Gross: 1,748.3%
Bilbel Capital Net: 847.1%
S&P 500: 74.3%
https://t.co/JwW2qwp5SY
"What really matters, is not the ratio of good ideas to bad ones. But how deep the best ones are.
Bad ideas only cause lasting harm if they stop us from finding good ideas.
Other than that,
All harm is finite, and
The best ideas are infinite."
- @bilbelcapital 2025 Annual Letter
https://t.co/ZWKO3YQDhz Water Oasis. Cash>Market Cap. Has float because of its brand power and this float keeps growing making it more like investable float/excess cash. The industry is in the doldrums, it hasn’t affected Water Oasis. They can now and do acquire other clinics cheaper. Sees Candy type brand built on something mission critical. People’s faces and looks, especially in Hong Kong culture. @bilbelcapital letter outlines the thesis succinctly. @sammutgabi
The market is missing an important loop:
- Customers prepay for treatments, so the float funds the business
- That's why it holds ~HK$1bn of cash, far more than people think is excess
- That cash can buy struggling competitors cheaply, and the prepaid float of the clinics it buys covers most of their cost
- Each deal adds more prepayments, so the loop is self-sustaining and compounds
But it's hard to see because:
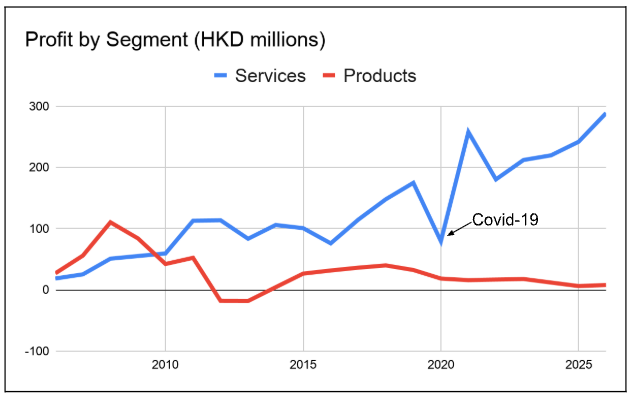
- Products and services are reported together, so growth looks flat
- Renovations are written off over ~1.6-yr leases but last 6+ yrs, so reported profit is too low
- Investment property (downward) revaluations swing reported profit, though they have nothing to do with the clinics
Plus:
- Dividends were previously cut to fund deals (but it was raised 43% in May 2026 because they have so much cash)
- Low liquidity
One of my favourite ideas this year came from my friend @sammutgabi , who runs Bibel Capital and is up about 2,000% gross since 2022.
Water Oasis runs beauty and medical-aesthetics centres in Hong Kong malls. It holds more cash than its market cap, has no debt, and trades at about 5x earnings.
Profit grew 27.6% in the last half, through a Hong Kong consumer recession, while its competitors shrink. Definetely a very interesting name, that I own in the fund.
Water Oasis is extremely cheap. Beauty service profit has grown 15% a year for over 20 years.
If it eventually trades at 15x earnings + net cash, that's 4x from here
Joel Greenblatt wanted a simple way to earn high returns.
He created the magic formula. It focuses on 2 factors:
-Return on Capital (ROC): Measures how well a business uses its assets to make money.
-Earnings Yield (EY): Shows how cheap a stock is compared to its earnings.
How It Works:
1. Rate 3,500 of the largest companies based on their Return on Capital (best to worst).
2. Rate the same companies by their Earnings Yield (high to low).
3. Add the two scores.
The lower the combined score, the better the ranking.
Example:
-A company ranked #1 in ROC and #5 in EY gets a combined score of 6 (1 + 5).
-A company ranked #10 in ROC and #4 in EY gets a score of 14 (10 + 4).
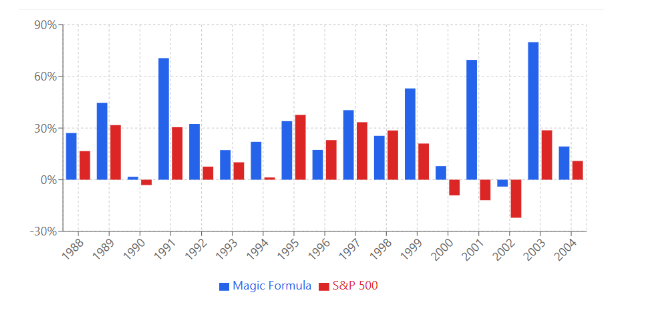
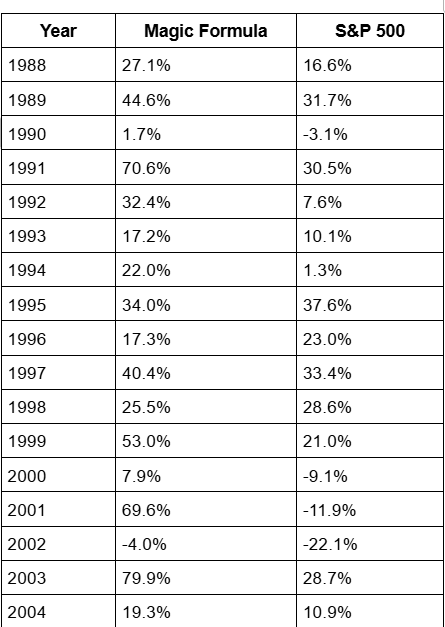
Average returns per year over the 17 year period:
-S&P 500: 12.4%
-Magic Formula: 30.8%
One of my constant buys since I wrote it up and favorite ideas, if not my favorite reported third-quarter results.
Original Writeup:
https://t.co/M4ZXB95ne2
The headline quarter looked soft, with net income down about 10%. But that came from mark-to-market losses on bonds and alternative investments.
Strip those out and the core business had a strong quarter. Insurance profit, which is what they make from underwriting before any investment results, was up 63% for the quarter. Through nine months it’s up 76%, to ₩969 billion from ₩550 billion. Nine-month net income is still up 23%.
They’re writing a little less new business, but at better margins. New CSM written in the quarter was ₩477 billion, down 6.7% from a year ago. But on policies sold through their own agents, the margin on new business (the CSM multiple) rose to 19.8x from 16.7x. Total CSM, the store of future profit already locked into policies, is now over ₩10 trillion, up from ₩8.9 trillion at the start of the year. This gets amortized into net profits each year providing a stable baseline for profits.
Investment yield is one of the core drivers of my thesis. When I wrote it up I said: “A 1% increase in the portfolio yield, would result in 370B in after tax income, 63% of 2025 Net income.” That is now happening. New money went in at 5.05% in Q3, up from 4.19% in Q1, while the existing portfolio earns about 3.06%. Management reaffirmed its target of ₩100 billion of investment profit a quarter.
The headline solvency ratio is above 210%. Since my write-up, the chairman has also gifted a 6% stake to his son, which matters for any long-term story about succession and capital return.
Worth noting: On the call they said they expect sensitivity to US rate exposure to decrease, they also increased premium pricing a bit as the industry as a whole scrambles towards profitability. Seems like a rational industry to be apart of not what Buffett described in his 1982 letter, where he describes insurance as the opposite of a rational industry:
“Insurance, therefore, would seem to be a textbook case of an industry usually faced with the deadly combination of excess capacity and a ‘commodity’ product.”
We scour global markets for overlooked microcaps trading far below intrinsic value.
Our advantage is that we Identify companies where perceived risk is enormous, but fundamental downside risk is limited.
We buy at deep discounts, focus relentlessly on capital preservation, and concentrate capital in our most compelling opportunities.
The ambition is exceptional long-term compounding.
Let me know if you’re interested in investing with @bilbelcapital, or if you require additional information.
You can pay double the stock price on Sun Kwang 003100 and still have a margin of safety. Because due to the market value of land and cash and investments these merely gets you to ascribing value to the operating business. Which is the best & cheapest port collections in the world at 2x current earnings. I think after all their projects are done and normalized that in 2032 earnings could be 3/4 todays market cap.
New podcast with @SammutGabi of @BilbelCapital:
- How his AI screens 15,000 stocks a month and finds 90% of his ideas
- Why volatility isn't risk
- Water Oasis $1161.HK
- What the Intellego $INT fraud taught him
- Why he only buys at 3-4x earnings
Link: https://t.co/kbxVtWbhXp
@sammutgabi podcast is a must listen if you are thinking about AI in your research process.
Young Buffett famously went through 20,000 pages of Moody’s manual. It’s hard work. I have done that. Five times. It took me 3 months to do one exchange. But AI can do it in minutes.
When I started building Apieron, I quickly realized how hard it is. Building the core data base, teaching it to think like me.
It is no where near perfect. But it’s way better than I expected.
It flagged:
B3 - Brazilian stock exchange at 10 times earnings.
Indocement - 1/3rd of replacement value, debt free cement company
A company that competes with Nike in Brazil with a fraction of that marketing budget.
It could’ve taken me months before I found these. But now Apieron does the grunt work. It rejects what I don’t want, tags the good ones.
I am excited for what it does next.
Great commentary on $1161.HK Water Oasis
My favorite takeaway: Risk=Volatility/Time
@sammutgabi shows Argus, a very cool screener that allows @bilbelcapital to start where the fish are and search from there. I think young Buffett and his Moodys Manuals would be quite jealous, although I do concede he must’ve felt like Sherlock Holmes using that big book
A very good discussion between @sammutgabi and @rja907
They talk about Argus, the Water Oasis thesis and why cheaper salons in Shenzhen don't break it; why volatility isn't risk; what the Intellego fraud taught Gabriel; analyzing a cement company as an energy business; and what returns he thinks are realistic as the fund grows.
https://t.co/q8sLUAuPex
@bilbelcapital currently holds some truly extraordinary companies in its portfolio.
They bring back positive flashbacks of Reysas…..
Businesses with exceptional fundamentals, significant undervaluation and enormous potential.
The future of investment research is being rewritten. And Bilbel Capital intends to be at the forefront of it.
At @bilbelcapital our proprietary AI-powered system, Argus, analyses 15,000 companies monthly.
Our competitive advantage? The ability to uncover deeply undervalued opportunities across global markets in a highly efficient manner.
The scale is extraordinary:
-15,000 companies analysed every month.
-Top 1% identified for further investigation.
-Global opportunities assessed through our investment philosophy.
-Human judgment focused on the most promising opportunities
What once required enormous amounts of research capacity can now be approached with unprecedented scale and efficiency.