An interesting move in the middle of October…. Undervalued yield pulling ahead of index concentration. $LMCLX
Miller Income Fund Info & Prospectus: https://t.co/SQoAud3biF
Higher rates have reset the return opportunity across bonds and equities.
But the critical variable isn't the direction of rates alone. It's the price investors pay relative to the cash flows and returns those assets can generate.
Five-year TIPS offered a -1.99% real yield in 2021. By Q3 2026, that yield had risen to +2.70%. That's a 469-basis-point improvement in the inflation-adjusted yield available to investors.
Higher rates can materially improve prospective returns on new investments.
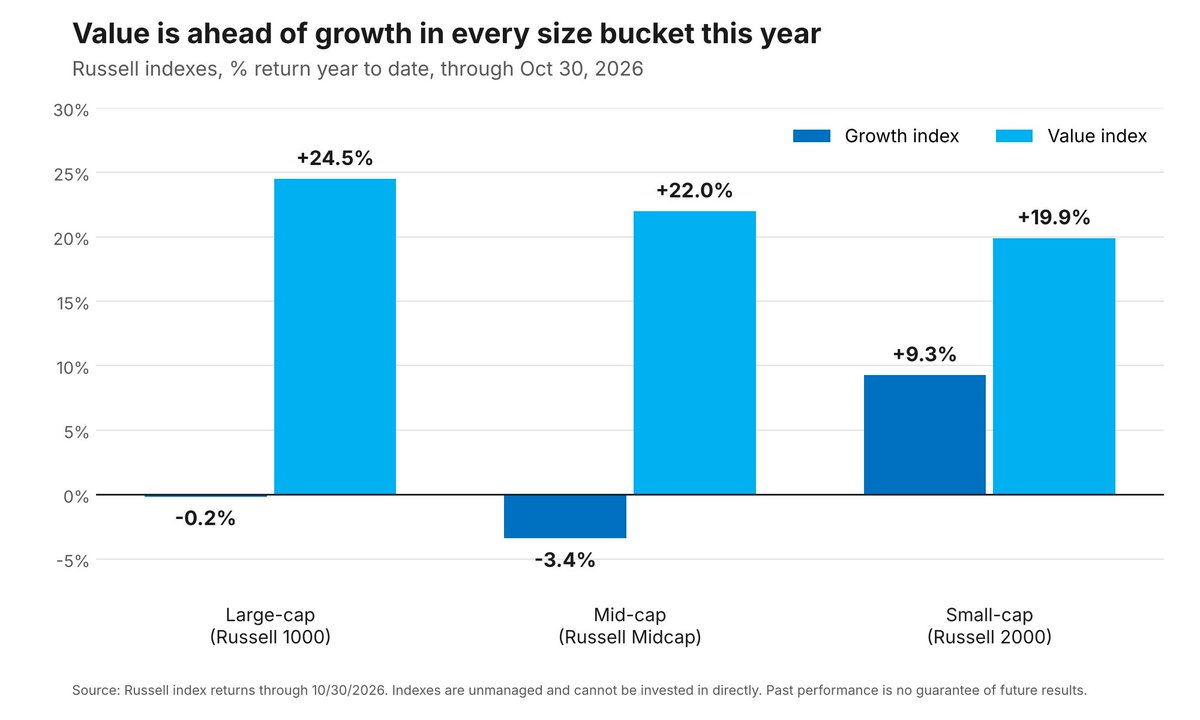
Value's consistent outperformance over growth across market capitalizations YTD is notable.
It reinforces the importance of separating market narratives from the actual distribution of returns. Valuation, earnings expectations, and company-specific fundamentals do not evolve uniformly across the market.
Neither do investment opportunities.
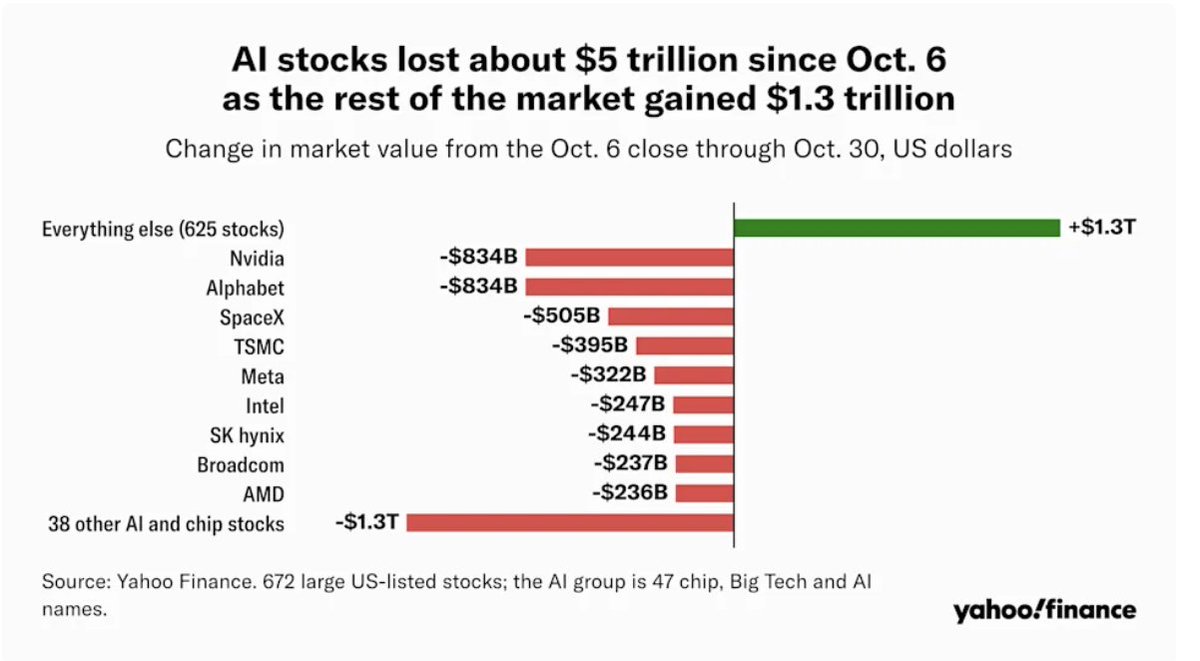
Today's AI-led sell-off exposed how much risk can be concentrated in a single investment thesis.
Diversification isn't just about owning more stocks. It's about owning businesses with different economic drivers and expectations embedded in their prices.
Investors don't have to choose between getting caught in every AI market swing and sitting out the market.
There are profitable businesses across financials, energy, healthcare and other sectors trading at valuations that reflect lower expectations today, but have high future potential. The opportunity set is much broader than the market's focus suggests.
Higher yields create opportunity when prices decline more than underlying fundamentals warrant. But when yields rise because cash flows are deteriorating or financial risk is increasing, the apparent opportunity may be misleading.
The difference is in the underlying economics, not the quoted yield.
The Fed held rates at 3.75%–4.00% last week, with two policymakers favoring a hike. The 10-year Treasury yield approached 5%.
Elevated long-term rates are changing the economics of income investing, from the returns available on Treasuries to the valuation of riskier assets.
Concentrix ($CNXC) has earned Everest Group recognition across four business-critical areas—including Leader designations in fraud management and trust & safety. https://t.co/f11I0u1oMl
MVP-managed portfolios hold CNXC; holdings may change. Informational only; not a buy/sell recommendation. Linking does not imply endorsement of MVP.
Market leadership can change quickly... and forecasting short-term moves is a waste of time.
Our approach is to identify businesses trading at attractive valuations relative to their future potential, not chase whichever segment is leading.
We believe there's a much broader opportunity set than the AI trade alone.
The 47 biggest AI/chip stocks lost ~$5T in value since Oct 6, per Yahoo Finance. The other 625 large US stocks gained ~$1.3T. The S&P slipped last week even as 9 of 11 sectors rose 1%+.