BREAKING: Israel is preparing for escalation with Iran, with Netanyahu urgently convening a security assessment tonight and his departure for the UN now unclear, per Channel 13.
A senior Israeli officer says the military is preparing for multiple scenarios, including a full-scale war with US backing or Israel acting entirely alone inside Iran. Senior officials estimate the Iranian front could flare up soon.
Netanyahu cut short his US trip on Saturday as Trump cut short his weekend at Camp David, and Trump said at the UN hours ago that his choice is a deal or to "annihilate the Islamic Republic."
BREAKING: Last week marked hedge funds' largest weekly purchase of US equities in 5 weeks.
This was driven by short covering in macro products, such as index futures and ETFs, as well as long purchases of single stocks.
The strongest demand was seen in Information Technology and Communication Services.
Hedge funds have now purchased equities in these sectors for 3 consecutive weeks.
Furthermore, hedge funds have bought US software stocks for 4 consecutive weeks and in 6 of the last 8.
As a result, hedge fund allocation to software rose to ~5.0% of their total market exposure, its highest level since the start of the year, up from a record low of 1.3% set in February.
Hedge funds are adding more tech exposure.
BREAKING: Trump reportedly canceled planned U.S. strikes on Ansarallah at the last minute, after changing his position on the operation multiple times, according to The New York Times.
Trump was reportedly opposed to strikes on Wednesday, backed them Thursday after speaking with Saudi Crown Prince Mohammed bin Salman, then reversed course again as the strikes were about to begin this weekend.
The New York Times also reports that much of Trump’s inner circle remains skeptical of military action against Ansarallah.
Trading will be 10x harder on Dec 6. They made it easier to trade, but extremely hard to make money.
Everyone thinks: more hours = more money.
Reality: more hours = more ways to lose.
Overnight = empty room. Wide spreads, no options, no big players, thin liquidity. You're trading against the house.
And more trades = more fees, more fatigue, more revenge trades. The closing bell used to save you from yourself. Now it's gone.
Real impacts on retail
Gap risk shrinks but doesn't vanish. You can react to Asia/Europe news, earnings, and geopolitical shocks in real time instead of eating the 9:30 gap. Weekends still exist, so Friday-to-Sunday gaps remain.
Liquidity will be concentrated in the top ~50 names. Mega-caps and big ETFs will get a usable overnight market; everything else will lag. Expect wide spreads and air pockets in small/mid caps, and the 20% bands aren't tight enough to save you from a bad fill.
No options overnight means no hedging your positions with puts at 2am, and no dealer gamma pinning or dampening moves. Overnight equity moves can run further than they would during RTH because the mechanical hedging flow isn't there.
Broker rollout will be uneven. Which brokers switch it on for ordinary accounts, and with which order types, is an open question. Market orders overnight will be a wealth-transfer mechanism to market makers.
Institutions come last. Most large asset managers have no mandate to trade thin books, so the buy-side won't flood in on day one. Overnight will be retail vs. market makers and prop desks for a while.
The 8–9pm pause and the 9pm reopen are new event windows nobody has data on yet.
After almost a decade of experience in this markets, I can almost read the script.
The Fed is hiking and oil is above $100.
Fundamentally, that is bearish for risk assets. Higher rates tighten financial conditions, higher energy prices pressure consumers and margins, and none of that suddenly becomes bullish just because the market pumps on the first reaction.
My base case is simple:
First, they pump it.
Then we get a 5–10% correction.
That correction pulls the bears back in, rebuilds short positioning, and convinces everyone that the breakdown has finally started.
Then comes the real squeeze.
They rip the market higher into year-end, force shorts to cover, drag sidelined money back in, and push bearish sentiment to the point where almost every bear finally gives up. This is where the majority starts believing that rate hikes are bullish.
And only after that, when positioning has completely flipped and everyone believes the worst is over, the real bear market begins in 2027.
The obvious macro trade rarely gets paid immediately.
First, the market punishes everyone who is positioned for it.
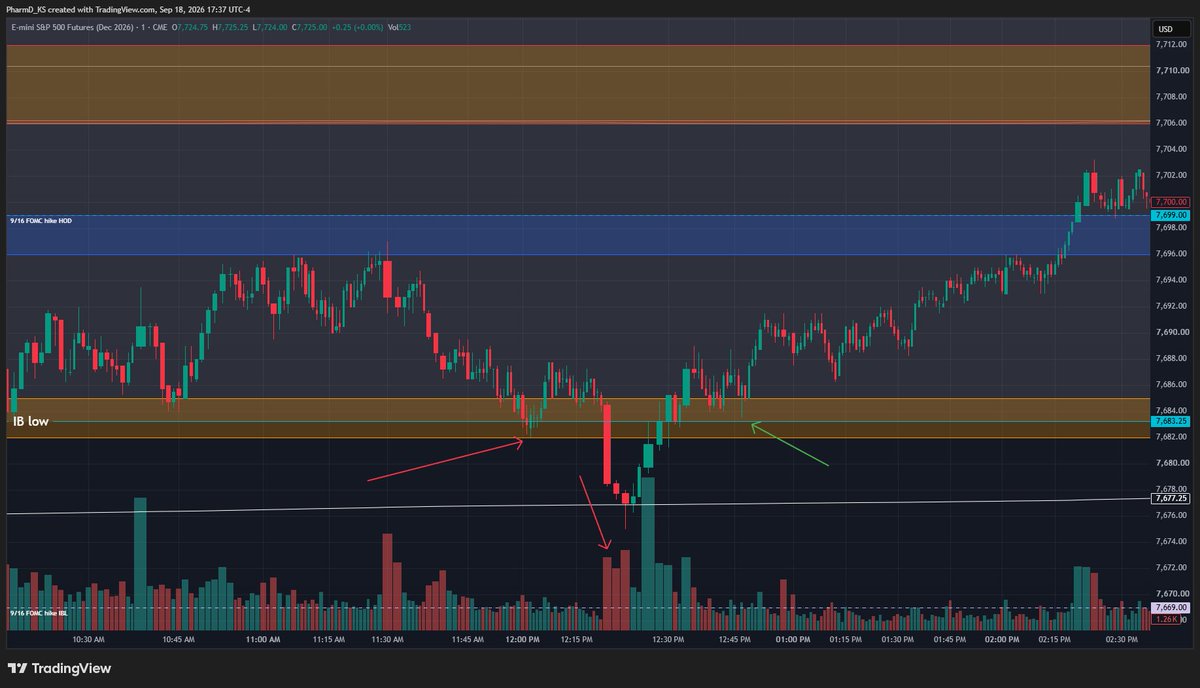
A great example of this on short frames today. I was short from the open, had taken profit already in my weekly 7682-7685 range. We came down and peeked below the IB low (83.25) and started to come back in. Normally I would cover more and possibly consider flipping long on a LBAF the IB low. I did neither. Clearly the 82-85 buyers lacked the strength to lift that daily 96-99 level (blue). They needed to be rinsed to bring in stronger buyers. 20 minutes later we got a break on accelerating volume, clearly a ton of stops had blown. I'm always covering some into liquidations and NOW my eyes are open for a reclaim of the IB low to cover and get long
Rumors are flying in China over Xi Jinping begin taken ill during his visit to India. They include claims that he suffered a minor illness to experiencing a stroke worsened by by failure to treat early. Some wild claims say rival group armies are mobilizing for civil war. No confirmation but Treasury Sec Bessent is meeting with Chinese counterparts today and we’ll see if the summit for Sept. 24 is still on
> Be Scott Bessent.
> Announce massive Treasury buybacks.
> Fallout with old pal Stan Druckenmiller.
> Bond yields instantly blow out anyway.
> Japan dumps US debt.
> Nobody wants to buy our debt.
> Hormuz is closed.
> Bab el Mandeb is closed.
> Crude explodes.
> Mortgage rates rip.
> FOMC forced to hike again.
> Iran parliament speaker makes fun of the Taylor Rule.
> Can't bond buyback a naval blockade.
> Trump isn’t so happy
Straits Taylor Rule:
i = r* + π* + 1.5(π−π*) + 0.5(y−y*) + α(SOH−SOH*) + β(BEM−BEM*), α,β > 0
Let’s see if a hike could open SOH or produce a single barrel :)
You can’t 25bp a chokepoint and r* isn’t neutral. It’s SOH risk premium, and We set it.
Stay unanchored !
Straits Taylor Rule:
i = r* + π* + 1.5(π−π*) + 0.5(y−y*) + α(SOH−SOH*) + β(BEM−BEM*), α,β > 0
Let’s see if a hike could open SOH or produce a single barrel :)
You can’t 25bp a chokepoint and r* isn’t neutral. It’s SOH risk premium, and We set it.
Stay unanchored !