@rdkriplani Tirumala Tirupati Devasthanams (Official Website) https://t.co/QZ6Qjlm4AK
Check here.
Try suprabatha seva you will get a chance to see deity very close.
Timepass talk on Sunday
1. Rentomojo
South Korea - In 2025, LG Electronics’ annual appliance subscription revenue grew 29% to ₹17,300 crore, on top of a staggering 75% growth in 2024 over 2023.
High urban density, particularly the prevalence of apartments, combined with younger generations moving more frequently, makes flexibility and built-in maintenance increasingly attractive compared with outright ownership.
India - Rentomojo is India’s largest organised furniture and appliance rental platform, offering a digital-first, full-stack rental solution across furniture, appliances, fitness equipment and household products through flexible subscription plans.
The company has evolved from a pure furniture-rental business into an integrated, multi-channel model spanning subscriptions, e-commerce and re-commerce. As of FY26, Rentomojo had 2,53,825 live subscribers and 8,51,184 live items across 29 cities, supported by 20 warehouses and 82 experience stores, generating ₹387 crore in revenue.
The real value creation sits in the asset lifecycle. Rentomojo procures products, delivers them to customers on subscription, manages maintenance and refurbishment, and then redeploys the assets across multiple rental cycles to maximise utilisation.
Appliances have quickly become the company’s biggest revenue driver, contributing around 40% of sales. The company also benefited from appliances accounting for 42%-47% of subscription revenue in FY25, while its market share was estimated at around 50%-55% of live subscribers as of March 2025. Profitability has also accelerated sharply, with FY26 PAT growing at a 118.4% CAGR over FY24-FY26, as the company scaled while maintaining healthy asset occupancy of above 82%.
Globally, this business model has already gained traction across multiple markets, with South Korea being the latest notable example.
According to one estimate, India’s appliance rental and subscription market was worth around ₹8,300 crore in 2023 and could nearly triple to ₹29,000 crore by 2028, implying a ~28% annual growth rate. The growth is being driven by urbanisation, a younger workforce seeking flexibility, and the appeal of avoiding large upfront capital expenditure.
So, while the growth opportunity in India’s cities and towns looks undeniably strong, operational challenges could keep Rentomojo on its knees.
Customers can be less careful with rented assets, leading to scratched beds, wobbly tables and damaged sofas. The problem becomes even more important in appliances, where reliability is non-negotiable. Any deterioration in asset condition or service quality could quickly lead to customer dissatisfaction and churn.
Rentomojo’s success, therefore, will depend not just on acquiring subscribers, but on maintaining operational discipline across logistics, installation, maintenance, refurbishment and customer experience. And as the company expands into Tier 2 cities, the economics of logistics, asset utilisation and servicing could become materially different.
The opportunity is clearly large. But in this business, execution is everything.
2. Triveni Power Transmission Limited
Triveni Engineering’s Power Transmission Business (PTB), focused on high-speed gears, industrial gearboxes, and defense propulsion systems, is arguably one of the hidden gems within Triveni Engineering & Industries.
The business is expected to be listed in the next couple of weeks. The NCLT has already approved the demerger, with July 22 being the record date.
With EBITDA margins of around 35%, a strong and diversified customer base, a sticky business model supported by a growing aftermarket segment, and a dedicated multi-modal defense manufacturing facility, PTB appears well-positioned for the next phase of growth. Capacity expansion is currently underway, with the potential to take revenues from FY26 levels of ₹340 crore to a peak capacity of around ₹700 crore over time.
The company has also secured a significant breakthrough order in the defense segment recently, further strengthening its growth visibility.
Another interesting aspect is its Swiss subsidiary, which could emerge as a wildcard. Located in Schaffhausen, Switzerland, a renowned precision engineering and industrial manufacturing hub bordering Germany, it provides PTB with proximity to several leading European OEMs and strategic access to key export markets.
The aftermarket business continues to gain importance. Its contribution to overall gear revenues increased to 40% in FY26, compared to a historical average of just over 30%. Triveni's turnaround time for standard aftermarket solutions is typically 2-3 months, versus an estimated 12 months for some global competitors. To further strengthen this advantage, the company has commissioned a dedicated aftermarket facility in Mysore aimed at improving execution speed and reducing delivery timelines for international customers.
Overall, PTB appears to be entering an interesting phase with multiple growth levers in place. It is certainly a business worth keeping on the watchlist once the standalone listing takes place.
3. Sudeep Pharma
Sudeep Pharma Limited is a diversified specialty chemicals and pharma excipients manufacturer operating three core businesses: Pharma, Food & Nutrition (66% of Q1FY27 revenue) producing phosphates and mineral-based absorbents (Absorbis Bisglycinates, a differentiated, high-margin specialty ingredient), Specialty Ingredients (31% of revenue) manufacturing premixes and encapsulation products, and NSS (acquired May 2025), a European subsidiary in food additives and industrial chemistry.
They generate ~56% of revenue from exports to 44 countries, with 32% from Fortune 500 customers. The business model relies on proprietary chemistry, regulatory approvals (USA, EU, etc.), and long-term customer contracts. Q1FY27 saw revenue of ₹158.3 Cr (up 27% YoY) with industry-leading EBITDA margins of 34.7% and PAT margins of 25.6%, demonstrating both scale and operational excellence in a capital-light, high-margin specialty chemicals franchise.
FY27 growth is anchored on three pillars: First, Absorbis Bisglycinates inflection, Q1 sales alone already surpassed the entire FY26 full-year sales, with two major North American approvals now scaling and visibility of this portfolio becoming a top 2-3 revenue contributor within 2-3 years. Second, Greenfield facility (Navsari) for pharma/food nutrition (5 customers approving, supplies starting Q3 FY27), which will unlock additional manufacturing capacity for the high-margin pharma/nutrition segment. Third, Specialty Ingredients normalization, Q1 was constrained by LPG supply shortage (causing sub-50% utilization), but production has normalized; core specialty (excluding NSS drag) maintained mid-30s margins and is expected to "bounce back" in Q2 with historical 30%+ growth trajectory resuming. Additionally, NSS European market is stabilizing with new leadership, 5 new customer approvals in infant nutrition/dairy signed, and 12-customer project pipeline building, positioning for margin recovery as energy costs moderate.
FY28 and beyond pivot toward two transformational growth engines. First, Sudeep Advanced Materials (SAM), the battery-grade iron phosphate project is on track for Phase 1 commissioning by March 2027 (25,000 KTPA capacity) at ₹300 Cr cost, with 44 active customers, 28 product approvals, two strategic MoUs signed with South Korean cathode manufacturers, and 7 customers in pre-commercial/commercial validation. Management expects to conclude two binding off-take agreements this year (FY27), which will trigger Phase 2/3 scaling to 100 KTPA; they're also evaluating expansion from 100 to 200 KTPA to meet long-term customer demand by calendar 2030-31.
Second, NSS margin recovery, target is for NSS to deliver similar margins as core specialty (~35%+) by FY28 as European market normalizes and integration benefits materialize. Combined with Greenfield contributions and continued Absorbis growth, the company is positioned to sustain 20%+ topline CAGR while protecting 34-37% EBITDA margins, with SAM becoming a meaningful growth engine once binding off-takes are signed and Phase 1 ramps post-March 2027.
4. Neetu Yoshi
Neetu Yoshi is primarily an engineering and manufacturing company dedicated to the Indian Railways and private railway ecosystems. They manufacture critical safety-grade components (Class A components), assemblies, and sub-assemblies across Wagon & Coach Components (Bogies, couplers, yoke supports, and sub-assemblies for wagons, locomotives, and passenger coaches) and manufacture Turnouts and sub-assemblies used in track infrastructure.
FY26 Performance – Century Mark Achieved:
The company achieved ₹101 crores total income (44% YoY growth) with PAT of ₹25 crores (53% YoY growth), delivering a 25% PAT margin. This exceptional profitability stems from a permanent Section 115BAB tax concession, the company's effective tax rate is 17.5% versus competitor peers at ~25%, creating a sustainable 7-8% tax advantage with no sunset clause.
New Manufacturing Facility - Operational Status:
The company's new bogie manufacturing facility in Hairdwar, Uttarakhand, funded with ₹50 crores of IPO proceeds, would have commenced commercial production on September 13, 2026. This facility is expected to substantially enhance manufacturing capabilities, improve operational efficiencies, strengthen execution capacity, and support increasing demand for the company's products in the railway and engineering sectors.
RDSO Approvals – Latest Milestone:
As of September 17, 2026, the company received RDSO approval for Friction Wedge (Item ID 3100430), a critical safety component for the new-generation high-speed "Raftar" bogie design. This is a high-value addition to the company's product portfolio and is expected to significantly strengthen qualifications for participation in upcoming procurement opportunities. Combined with prior approvals, the company has 25+ certified products with a pipeline of 15-20 additional products awaiting RDSO/railway zone approval.
FY27 Guidance & Revenue Visibility:
Management has provided FY27 revenue guidance of ₹210-220 crores, expecting to sustain 25% PAT margins. Revenue generation is skewed toward H2 FY27 as new production lines progressively ramp up. Peak capacity potential across both plants (old ₹110 Cr + new ₹200 Cr + track products) stands at approximately ₹340-350 crores, expected to be achieved in FY28.
Order Book & Demand Visibility:
Order book stands at ₹140-150 crores with various open orders. The company is positioned for the 1-lakh wagon tender, which will drive indirect demand for bogie assemblies and component sub-assemblies. The wagon industry is expected to return to normal growth trajectory as the mega tender activates.
Capital Expenditure & Working Capital:
No heavy capex is budgeted for FY27; focus is purely on harvesting FY26 investments. The new facility capex is complete, positioning the company to drive operational leverage from H2 FY27 onwards.
Risk Factor:
Biggest anti-thesis: B2G companies may face headwinds in FY27 due to fiscal deficit constraints, which could lead to slower government spending and delays in project awards and execution.
5. Shivalik Rasayan
Shivalik Rasayan is an integrated chemical manufacturer transitioning from legacy agrochemical producer into a research-driven CDMO (Contract Development & Manufacturing) platform, with US FDA-approved facilities for complex oncology and non-oncology.
What Went Wrong: Shivalik delivered decent revenue growth but suffered PAT collapse (especially in Standalone numbers). The culprit is a combination of deliberate transformation costs.
First, R&D spend jumped to ₹94.9 Cr as management attempts to convert the R&D center from a cost center to profit center, this is strategically sound but margin-dilutive near-term.
Second, both new manufacturing plants (Dahej-II FDA-approved API facility and Dahej-III 2,500 MTPA agrochemical facility) came online with ramp-up inefficiencies and underutilization.
Third, the core agrochemical business faces structural headwinds: heavy China intermediate reliance, global oversupply, and freight/energy volatility compressing margins on commoditized technicals. Profitability moderated despite scale, which is why Street focus now shifts to when margin recovery begins.
Current Situation: The company is operationally transitioning well, first commercial NCE-1 product delivered in April 2026, proving CDMO capabilities beyond R&D promises.
Two additional API programs (F2F + NCE-1) are active with a US pharma customer, and interest from Japan/South Korea is expanding the addressable market. Consolidated revenue jumped 18% (₹36.8 Cr), benefiting from strong associate (Medicamen Biotech) performance.
The critical inflection is Dahej-III: management explicitly targets ₹200 Cr revenue potential over the next two years from this new agrochemical facility, which is achievable given new technical launches (Trifloxystrobin, Kresoxim Methyl) and structured export demand. So while profitability contracted, the underlying operational setup is primed for a significant margin and volume inflection starting FY27.
4 Growth Triggers:
1) Dahej-III monetization (₹200 Cr/2 years): New 2,500 MTPA technical-grade agrochemical plant ramps to full utilization with premium-priced new molecules, driving gross margins of 35-40% vs. current commodity pressure.
2) CDMO/NCE-1 inflection: As existing projects transition from development to manufacturing, contract gross margins of 40-50% will structurally elevate overall profitability; current pipeline of 3-4 active programs suggests 2-3 could hit commercial supply by FY28.
3) R&D profit-center transformation: Company achieved breakeven on R&D last year and targets profitability this year; incremental ₹20-30 Cr CDMO revenue contribution = 25-40% upside to current PAT.
4) Complex API facility utilization: US FDA-approved facility specifically built for regulated-market APIs (including oncology at 30-40% gross margins) is now receiving validation from US customer programs and geographies like Japan/South Korea; as these scale into manufacturing, both topline and margin profile shift dramatically.
Key watch: Any potential contarct wins for Palbociclib molecule, Standalone EBITDA margin recovery to 19-20%+ and active CDMO pipeline depth (# of projects in manufacturing phase).
That's all for this edition. Have a great Sunday!
Disclaimer: None or buy or sell recommendations. This publicly available information is shared for learning and education purposes.
@NHAI_Official Please take care of Guddur toll gate in Karnataka Andhra border properly. One of the worst facilities with uncleaned washrooms. No water and people will get diseases one they enter. Attached google map reviews for reference
https://t.co/ILm239a67q
@nitin_gadkari
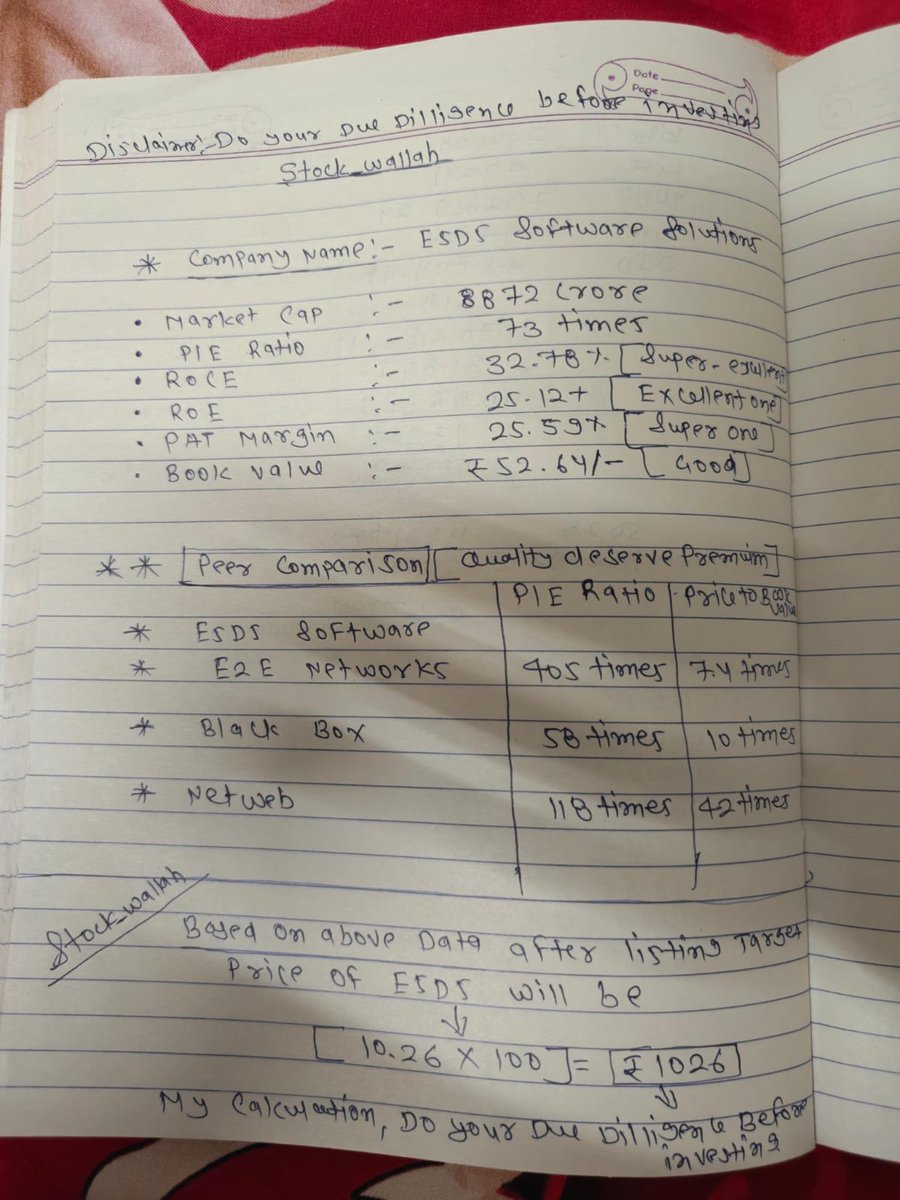
ESDS Software Solution 💻 🔥💎💛:- core portfolio stock 💵💲💚
ESDS WILL BE NEXT NETWEB 🚀
My notes 👇
Co. is interesting because it is not just a normal IT-services company. It is positioned at the intersection of 👇
Data Centres + Cloud + AI/GPU + Cybersecurity + Digital Sovereignty.
So the investment story isn't simply:
Data centre company ❌
It is increasingly:
Data Centre → Cloud → GPU → AI → Cybersecurity ✅
AI + Sovereign Cloud + Data Centres 🔥🥇
ESDS is building an Indian technology infrastructure ecosystem where organisations can keep critical workloads and data on Indian infrastructure under Indian regulatory jurisdiction. The company currently operates multiple Tier-III data centres and is expanding its footprint.
🔥 6 major strengths
1. 🏢 Data-centre infrastructure
Tier-III data-centre network
Cloud, colocation, managed infrastructure and disaster recovery
Exposure to India's growing data-centre demand.
2. ☁️ Indigenous/Sovereign Cloud — BIG speciality
ESDS is positioning itself as an Indian alternative for organisations that need data residency, regulatory compliance and control over critical workloads.
3. 🤖 AI + GPU opportunity
This is probably the most exciting growth angle.
ESDS has entered GPU-as-a-Service and AI infrastructure, including large GPU clusters/SuperPOD infrastructure. Its platform is designed to support AI/ML workloads.
4. 🛡️ Cybersecurity
ESDS is developing an integrated security ecosystem including SIEM, PAM, database activity monitoring and managed security services.
5. 🧠 Proprietary AI software
The company has launched its SWARAJ product ecosystem, including:
SWARAJ Cloud
SWARAJ Bodhi — AIOps
SWARAJ Garuda — application performance/observability
SWARAJ Jatayoo — database activity monitoring
SWARAJ Nandi — privileged access management
SWARAJ Hansa — SIEM/security
That gives ESDS an additional software/platform layer on top of its physical infrastructure.
6. 🏦 Strong exposure to BFSI + Government
This is strategically important because banks, government departments and other regulated organisations have stringent requirements around security, compliance, availability and data residency. ESDS serves government/PSUs, BFSI and enterprises.
💎💎💎💎💎💎💎💎💎💎
Why I find the ESDS story interesting
Think of the business like this:
India's digitisation
↓
More data
↓
More cloud usage
↓
More data centres
↓
More AI workloads
↓
Huge GPU requirement
↓
More cybersecurity
↓
ESDS potentially participates in several layers of the same megatrend.
In one sentence: 👇
🔥 ESDS's biggest speciality is that it is trying to become an Indian end-to-end digital infrastructure player combining sovereign cloud + data centres + AI/GPU infrastructure + cybersecurity, rather than remaining a conventional IT-services company.
⚠️ One important caution
The story is attractive, but don't look at it as a guaranteed multibagger. ESDS has customer concentration, with its largest customers contributing a meaningful portion of revenue, and data-centre/AI infrastructure requires substantial capital expenditure. GPU, memory and cooling costs are also risks.
@epfobellandur@officialepfo It's almost 2 months still my claim amount is not settled. Really not sure what kind of work these @officialepfo staff does. Do a bit of work for the salary you people get.
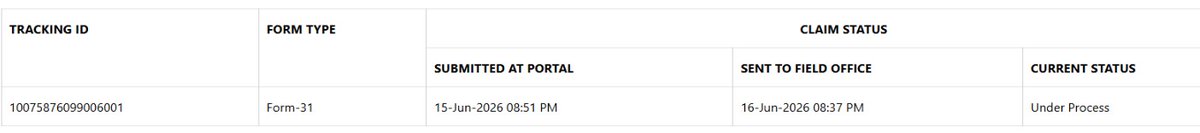
@officialepfo Initiated a claim on 15-06-26 with track id: 10075876099006001 it is under process for more than 50days. Initiated another claim after EPFO3.0 with id: 10075876099006501 that also in process. I am requesting my money on emergency why can't you settle it immediately?