PayPal $PYPL: Golden Buying Opportunity Before Q4 Earnings
By Hataf Capital
It is quite rare to see a global fintech pioneer like PayPal $PYPL treated like a dinosaur in a world suddenly obsessed with generative AI and flashy neo-banks.
If you look at the price action lately, you’d think the company was facing an existential threat rather than just navigating a transition year. The stock has been underperforming, and let’s be honest, the sentiment is ugly.
But as I’ve said before about Novo Nordisk and UnitedHealth, sometimes the market hands you gifts wrapped in fear.
With the Q4 earnings call scheduled for February 3rd, we are looking at what I believe is a classic "coiled spring" setup. Between an RSI that signals a deep oversold condition and a valuation that borders on the inexplicable, the bar for PayPal has been set so low that even a modest jump could trigger a massive re-rating.
The Myth of Growth Deceleration
The prevailing narrative on Wall Street is that PayPal is a "broken growth story." Analysts are projecting Q4 revenue to hit roughly $8.8 billion, which represents a meager 5% year-over-year growth.
To me, this forecast isn't just conservative; it’s a fundamental misreading of the 2025 holiday season data.
Historically, PayPal sees a sequential revenue bump of 7% to 8% between Q3 and Q4, driven by the sheer magnitude of holiday spending.
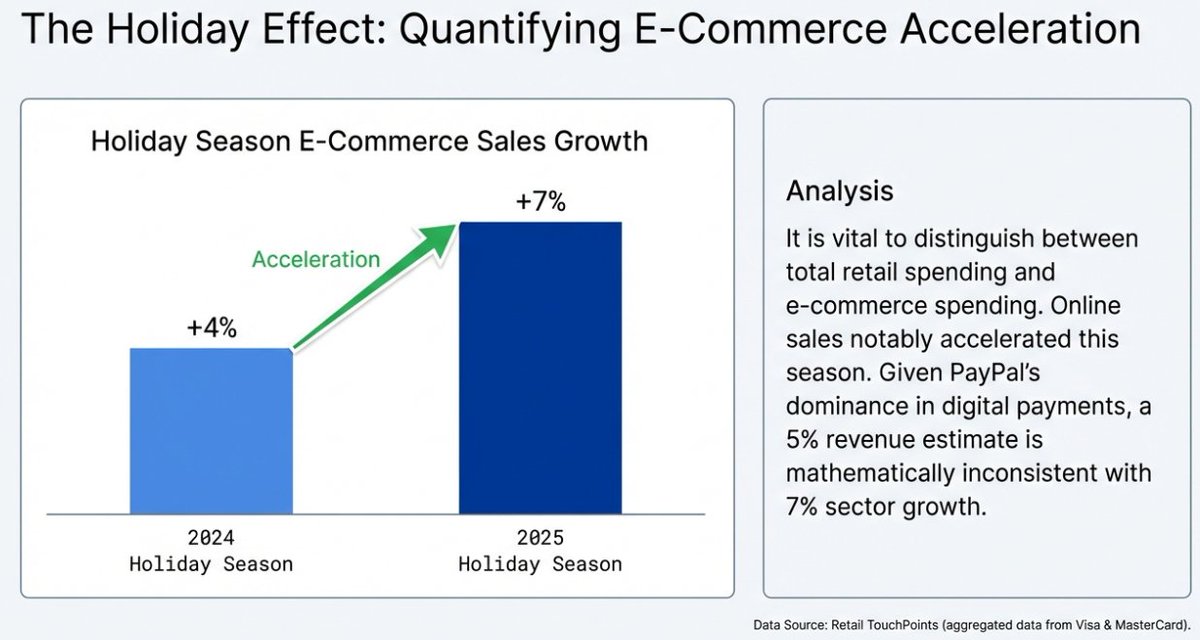
If we look at the actual boots-on-the-ground data from Visa and MasterCard, e-commerce sales growth topped 7% during this past holiday season. Compare that to the 4% growth we saw in 2024.
We are seeing a notable acceleration in digital wallet utilization, yet the market is pricing in a deceleration.
I don't think PayPal is going to pivot back to a slow-growth crawl while the U.S. economy remains this resilient.
With unemployment still hovering near record lows and consumer spending shifting more aggressively toward digital platforms, a 7% year-over-year revenue growth is a much more realistic, yet still grounded, forecast.
When the market expects a 5% "failure" and gets a 7% "success," the resulting squeeze is where the money is made.
Improving Unit Economics: The Profitability Lever
One of the most underappreciated aspects of the PayPal story is the management’s commitment to operational efficiency.
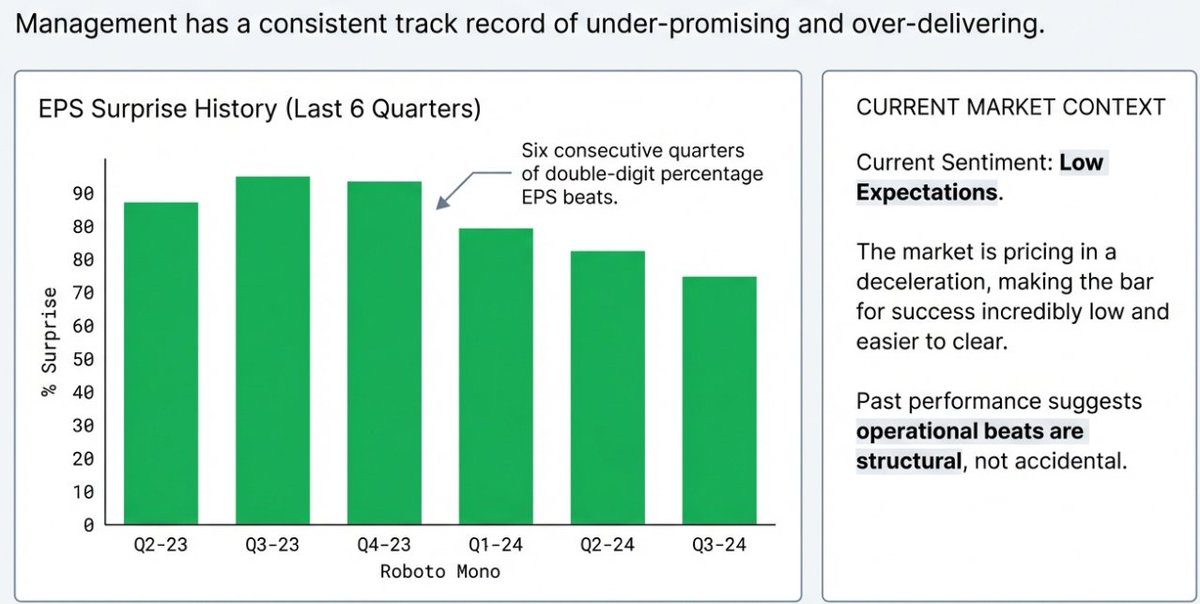
Over the last six quarters, PayPal has delivered six double-digit percentage EPS beats on average. These weren't symbolic one-cent surprises; they were evidence of a company that is learning to do more with less.
If you analyze the TTM gross and operating margins, they’ve expanded by approximately 100 basis points compared to FY2024.
PayPal has a proven track record of driving bottom-line growth faster than top-line revenue demonstrated by a five-year EPS CAGR of 13.5% against revenue growth of 10.1%. This tells me their unit economics are improving.
If the company delivers on my 7% revenue growth projection, the operating leverage inherent in their model should easily push EPS into low double-digit growth territory.
The market is valuing PayPal like a legacy processor, but the numbers suggest a highly profitable, cash-generating machine that is becoming more efficient with every transaction.
A Valuation Anomaly That Defies Logic
Let’s talk numbers, because this is where the thesis becomes truly asymmetric. PayPal is currently trading at an estimated FY2026 forward P/E of just 9.
Think about that for a second. This is a 58% discount to its historical average. We are talking about a company with a dominant market position and a healthy balance sheet trading at a lower multiple than many stagnant utilities.
On an EV/Sales basis, it sits at 1.5x, while the sector median is closer to 3x. Its Price/Cash Flow of 7.4x is nearly half of the sector’s 13.5x.
Wall Street’s average target price is sitting around $70, which implies a 33% upside from current levels. But I think even that might be conservative if the market finally recognizes the intrinsic value of PayPal’s massive user base and its role as the plumbing of the internet. You are essentially paying for a distressed asset and getting a high-quality, high-margin fintech leader.
The Technical "Coiled Spring"
From a technical perspective, the setup is almost perfect for a post-earnings pop. The 14-day RSI is currently sitting at 27. For those who don't follow technicals, anything below 30 is considered deeply oversold.
This tells me that the sellers have largely exhausted themselves. The "weak hands" have already folded, and the current shareholders are likely those with higher conviction or those waiting for a reason to buy more.
When a stock is this oversold heading into an earnings release where expectations are already in the basement, a "double beat" (Revenue and EPS) usually results in a violent upward correction.
What Could Go Wrong?
I’m bullish, but I’m not blind to the risks. In the short term, the market is a voting machine, and right now, it’s voting for AI.
If tech giants like Meta or Microsoft release earnings in the same window and suck all the oxygen out of the room with AI hype, PayPal’s solid results might be ignored for a few weeks.
There is also the "noise" factor. Geopolitical headlines or macro shifts can mute even the best earnings reports. However, for the long-term investor, these are temporary distractions.
The fundamental thesis that PayPal is a cash-flow monster being mispriced by a factor of two remains intact regardless of the daily news cycle.
Final Thoughts
PayPal is currently in an identity crisis, but the data suggests it’s far healthier than the share price indicates. We have a combination of conservative estimates, accelerating holiday data, and an extreme valuation discount.
I am maintaining my Strong Buy rating. The market is giving us a chance to buy a blue-chip fintech name at a "junk" multiple. I, for one, am happy to take the other side of that trade.
[Guys! Please Make Sure To Like And Repost If You Like Our Content]
A video of Serbian family celebrating the feast of St. Nicholas went viral on Instagram, but sadly it’s because many Americans mocked them for having simple food and humble circumstances.
Respect for their faith and resilience. God bless and help this family.
🇷🇸☦️
Here Tom Brady explains why 99% of QB discussions on the internet are garbage and why he's the goat.
In 5 minutes he clearly distinguishes the main difference between great QBs and average QBs without ever mentioning the one thing that most TV and Twitter NFL analysts focus on - because that "thing" doesn't really matter if the QB is actually great at his job. See if you can spot it? This is a must watch if you love QB play. #GoFins