$NVDA 2 mm glass substrate push is a decisive unlock for massive AI packages—superior rigidity and lower warpage enable denser GPU+HBM stacks at scale. With TGV drilling and ALD/HiPIMS metallization already demonstrated, this cements NVIDIA’s packaging lead and accelerates next-gen AI performance - Bullish $GLW $ASX $SHMD $LPKF $PLANOPTIK
$NVDA IS PUSHING GLASS SUBSTRATES TO EXTREME THICKNESSES
According to Korean semiconductor publication KIPOST, NVIDIA is requesting glass substrates with a thickness of 2,000 µm (2 mm), potentially driving the adoption of new metallization technologies, including atomic layer deposition (ALD).
As AI packages grow larger to accommodate more GPUs and HBM, substrate rigidity becomes increasingly important. Thicker glass improves mechanical stability and reduces warpage, but makes through-glass vias (TGVs) harder to manufacture.
For perspective, a 2 mm substrate with 50 µm vias would have an aspect ratio of 40:1.
Conventional sputtering struggles to deposit uniform conductive seed layers inside such deep, narrow holes. ALD's superior conformality could provide a solution.
However, ALD isn't the only competing technology.
In September, TRUMPF announced its HiPIMS technology for coating deep TGV structures, using highly ionized plasma to improve coverage. Meanwhile, MKS Atotech introduced a wet metallization process combining electroless copper seeding with advanced electroplating.
Progress is also being made in drilling. Korean equipment manufacturer Philoptics demonstrated TGV processing on 2 mm-thick, 510 × 515 mm glass panels, claiming zero defective holes in its demonstration.
CPO makes late defect detection expensive.
MA-tek warns that defective silicon photonics dies escaping wafer-level screening can waste expensive materials once they enter CPO packaging. Testing must account for optical, electrical, thermal and mechanical interactions, with fast, repeatable optical alignment critical to throughput.
Taiwan’s suppliers are building for that demand. WinWay reports 10 CPO socket projects, while MSS’s photonics analysis tool is undergoing customer trials and validation. The implication: catching defects earlier and shortening measurement time could become increasingly valuable as CPO production scales.
https://t.co/j4Es8Uw7oK
CPO turns late-stage defects into high-cost scrap because photonic dies sit inside expensive co-packaged optical engines—early wafer-level opto-electrical screening is therefore economically decisive, not optional. Taiwanese interface suppliers (WinWay’s 10+ socket projects, MSS trials) are correctly targeting the multi-physics test and alignment bottleneck that will gate yield as production ramps @schulz_research
Glass Substrates Are Progressing Faster Than Ever
Lately, it's SEMCO that's been pushing commercialization forward
SEMCO has just completed initial reliability testing of its 100 × 100 mm glass substrates and moved to package-level testing using actual customer chips
The company is working with several major global customers
SEMCO targets an operational production line by late 2027 and full-scale manufacturing in 2028
Previous TGV reliability issues delayed equipment orders, making successful package-level validation a critical milestone
It's strongly rumored that $LPK played a key role in resolving these issues, with improvements coming primarily from the development of thicker glass substrates
$GLW just signed a $3B+ fiber deal with $T, 3x the 2024 one, on top of its $AMZN and $NVDA contracts. A lot of this shortage might be getting locked into multi-year contracts before it ever reaches spot, which would explain why Japan spot isn't exploding yet.
Corning's Q3 optical number will be a good one to see!🧐
$GLW
Morgan Stanley now puts Corning inside NVIDIA's CPO supply chain for the Rubin NVL576 generation. That's the right call on $GLW, and it moves Corning from the cable outside the rack to the fiber inside the box.
CPO (co-packaged optics) puts the optical engine on the same package as the switch chip, so the fiber has to run inside the switch box, all the way to that package. Corning's management said it plainly in September: "We are bringing optics inside the box for a new generation of technology for co-packaged optics and near package optics."
The same month Corning described its NVIDIA deal as a partnership "to dramatically expand US-based manufacturing of the advanced optical connectivity solutions needed." In-box fiber now has a named customer behind it.
I hope Corning puts a revenue number on in-box optics on its next earnings call. Once NVL576 ramps, $GLW should start getting paid for the fiber inside the box, and I'd expect that business to keep growing from there.
Glass substrates just cleared a meaningful hurdle at SEMCO. Moving from substrate-level reliability to package-level testing with actual customer chips on 100×100 mm formats shows the TGV issues that stalled them earlier this year are being solved in practice, not just on slides.
This size is already larger than Nvidia’s Blackwell package substrate and lines up with what hyperscalers want for the next wave of AI accelerators. The fact that multiple major customers are engaged and equipment orders have restarted supports the case that glass is transitioning from pilot to early commercial readiness faster than most expected six months ago.
LPKF looks well placed. Its LIDE process is one of the few proven ways to make reliable TGVs at scale, and the industry shift toward thicker glass for stiffness and lower warpage plays directly into its strengths. If SEMCO hits the late-2027 line start, glass moves from “interesting alternative” to a real option for high-end AI packaging.
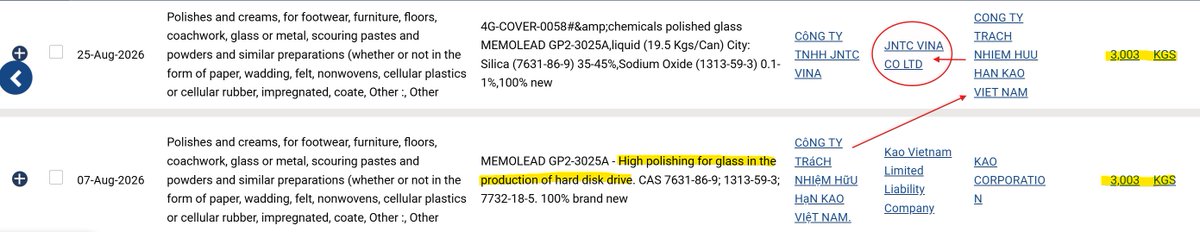
JNTC Vina shipment of ~8,300 kgs of polishing consumables specifically for HDD glass substrates/platters. I would assume consumables would be one of the last purchases before mass production.
*Vietnam import data I can see only goes to August 31 so I can't see September yet
Everyone is counting glass-core capacity. Schmid ($SHMD) pointed at a different step.
On its Aug 25 call the CSO named TGV metallization, filling the holes with copper, as the technical bottleneck. Customer qualification was still ahead then.
Yesterday brought a datapoint on that exact step: Korea's JNTC cut copper fill in 2 mm glass to minutes, and TOPPAN (TSE: 7911) checked production efficiency (The Elec).
The bath chemistry is mostly Japanese. On our glass-core map, 4 of the 8 plating chemical suppliers are Japanese, including JCU (TSE: 4975) and Uyemura (TSE: 4966).
What I'm watching next: the first glass-core qualification Schmid announces.
Glass substrate talk isn’t just cheap narrative—the industry has already moved past slides. Intel, Samsung, and TSMC have public glass-core and panel-level packaging roadmaps targeting AI accelerators precisely because organic substrates warp and lose signal integrity at the package sizes now required. Volume is still a few years out, but the constraint is process yield and supply-chain build-out, not demand. Early suppliers with existing glass-processing know-how get paid for qualification lots and design wins long before the income statement looks dramatic. Myopia cuts both ways: dismissing the shift until revenue arrives is how specialty players get rerated after the fact
Marvell’s October 6 Investor Day reset the AI interconnect narrative. Management’s first-ever fiscal 2031 revenue framework of $70–90 billion (midpoint $80 billion) sits far above prior Street models near $47 billion, off a fiscal 2026 base of roughly $8.2 billion. The data-center TAM was lifted to about $400 billion by 2030—roughly four times earlier projections—with interconnect (optical and electrical links) sized at a $65 billion opportunity and expected to contribute roughly $37.5 billion of Marvell revenue at the long-term midpoint.
The binding constraint is no longer compute silicon; it is moving data at 1.6T and beyond as copper reaches physical limits inside the rack. Scale-up optics, co-packaged optics, and near-packaged optics are pulling demand forward. Lumentum’s CEO has stated the company expects to fulfill only about 30 percent of customer requests in 2027 (a 70 percent shortfall), with supply-demand balance not anticipated until 2029–2030 even after aggressive capacity adds. Coherent remains booked through the end of 2027. Those shortages support pricing power and multi-year visibility for the pure-play laser, transceiver, and silicon-photonics suppliers riding the same curves.
The highest-leverage names in the supply chain are therefore Lumentum (critical EML and pump lasers), Coherent (vertical integration and backlog), Applied Optoelectronics (in-house InP and hyperscaler exposure), Ciena (coherent systems), Tower Semiconductor (silicon-photonics foundry capacity), and Astera Labs (connectivity silicon). Marvell’s own interconnect ramp validates the end-market trajectory those companies already serve. Execution risk remains on capacity ramps and customer qualification timelines, but the combination of a multi-year TAM expansion, documented allocation, and hyperscaler capital commitments creates a durable volume and pricing tailwind through the end of the decade
Glass Substrates are no longer Slideware - 3 Things to Watch ⚠️‼️ TGV volume-production yield, whether CoPoS holds its 2028 mass-production schedule, and when the first AI accelerator on a glass interposer actually ships
https://t.co/axFSij0rqv
$SHMD sits at the equipment layer of two transitions now moving into commercial scale: wafer-to-panel packaging and organic-to-glass substrates. Powertech’s AMD FOPLP program, Silicon Box past 1 billion packages, Samsung’s glass-substrate tool order and WG Tech’s TGV capacity build all point the same way—customers are adding real capacity. That is when equipment demand typically starts to matter
A very interesting day for the $SHMD investment case.
Four separate developments across Taiwan, Korea, Singapore and China provide further evidence that two markets Schmid Group is exposed to – Panel Level Packaging and Glass Core/TGV – are moving closer to industrial scale.
1⃣ Powertech: large-format FOPLP for AMD
Taiwanese OSAT Powertech is scaling its 510×515mm FOPLP platform for AI applications.
Equipment for an AMD-related project is already installed, with small-scale production planned for H1 2027 and volume production targeted before mid-2027.
PTI has already developed packages above 5x reticle size, targets equipment for 9x reticle by year-end and eventually plans to support 14x reticle.
The company says large AI packages could achieve up to 45 units per panel versus roughly 8–9 using wafer-based processing, while yields have improved to above 90%.
For Schmid, this is important because it shows large-format panel processing progressing from technical development into a real AI customer program.
2⃣ Silicon Box: Panel Level Packaging is already at billion-unit scale
Silicon Box has now shipped more than 1 billion advanced packages from its panel-level facility in Singapore.
Only around one year ago, the company had reached 100 million.
The next target is 2 billion units by the end of 2026, while another $300m is being invested in Singapore capacity.
This is an important validation point for the broader PLP thesis:
Panel Level Packaging is not merely a future alternative to wafer-level processing. It is already being operated at industrial volumes – and customers continue to add capacity.
3⃣ Samsung Electro-Mechanics: concrete equipment spending for Glass Substrates
Hanmi Semiconductor received a KRW 24.48bn equipment order from Samsung Electro-Mechanics.
The systems are explicitly designed for applications including Glass Substrates and integrate sawing, cleaning, vision inspection, sorting and placement.
This matters because Glass Core only becomes commercially relevant once an entire production ecosystem exists around it.
TGV formation alone is not enough. Manufacturers need metallization, RDL, handling, inspection and back-end automation.
A major substrate producer now spending real money on this process chain is another step towards industrialization.
4⃣ China: WG Tech scales TGV capacity towards 1 million m² per year
WG Tech has started the second investment phase of its TGV glass-substrate production line.
Its first phase provided roughly 100,000 m² of annual capacity.
The longer-term target is up to 1 million m² per year, with customer qualifications already completed and initial small-volume deliveries underway.
Target applications include AI computing, 1.6T optical connectivity and CPO.
Again, the important point is not another laboratory prototype.
It is capacity being built for commercial production.
⬇️
Why does all of this matter for Schmid Group?
Schmid is positioned at the equipment layer of both transitions:
Wafer → large-format Panel Level Packaging
and
Organic substrates → Glass Core / TGV
No single announcement proves how large Schmid's future revenue opportunity will become.
But taken together, today's four datapoints are meaningful:
➡️ real AI customer programs
➡️ billion-unit PLP production
➡️ concrete Glass Substrate equipment orders
➡️ rapidly expanding TGV capacity
The discussion is gradually shifting from whether these technologies can work to how quickly customers will scale them commercially. And that is exactly the point where the size of the equipment opportunity for Schmid starts to become much more interesting.
...
Disclaimer: No guarantee is given for the accuracy or completeness of the information provided. This is not investment advice. Schmid Group shares are held in the Tigris Small & Micro Cap Growth Fund.
Taiwan Supply Chain to Keep Hiking Prices in 2027
Taiwan’s chip supply chain is heading into another round of price increases in 2027
$TSM plans process-specific wafer price increases starting in January 2027, while mature-node pricing will be negotiated case by case. VIS expects 2027 increases to match or exceed those in 2026, UMC plans broad contract renegotiations, and PSMC and SMIC are also preparing hikes
$ASX is reportedly considering price increases of up to 20%, driven by higher material costs and capex for capacity expansion
Taiwanese IC designers expect to pass these costs downstream. For display driver ICs, foundry costs represent 60–70% of total costs, meaning a 10% wafer price increase would raise total product costs by 6–7%
After 10–25% IC price increases in 2026, 2027 pricing will depend heavily on end demand. Cloud AI has the strongest pricing power, while mobile, PCs, MCUs, and PMICs face much greater resistance to higher prices