Simplifying the $1k → $100k challenge.
Old:
25% $QQQ
25% $VOO
25% $SPMO
25% $SCHD
New:
50% $VOO
50% $SPMO
Less overlap. Lower weighted fees. Less dividend tax drag. Simpler rebalancing.
New money always buys whichever is <50%. If both are balanced, 50/50.
VOO gives me the market. SPMO systematically concentrates into whatever is winning.
That’s it.
“Action creates information.”
I’ve learned this the hard way. I’ll sit on something, turn it over in my head, research it some more. Feels productive, but I’m still stuck on the same questions.
Then I finally do the thing and find out half of what I was worried about didn’t matter. The actual problem was something I hadn’t even considered.
Send the message. Make the ugly first version. Try it while you still suck at it.
Now you have a response, a mistake, something to work with. You can adjust.
Thinking has its place. But sometimes you’re asking your brain to answer a question that only doing it can answer.
@SCHDaccumulator Let’s gooo! Have you checked out X Money? They’re paying like 6% and give a little welcome bonus too. No fees and super easy to move in and out.
Small win elsewhere on that dip yesterday: $156.73, fully cashed out. Moved it into the Stack, never to see the light of day again.
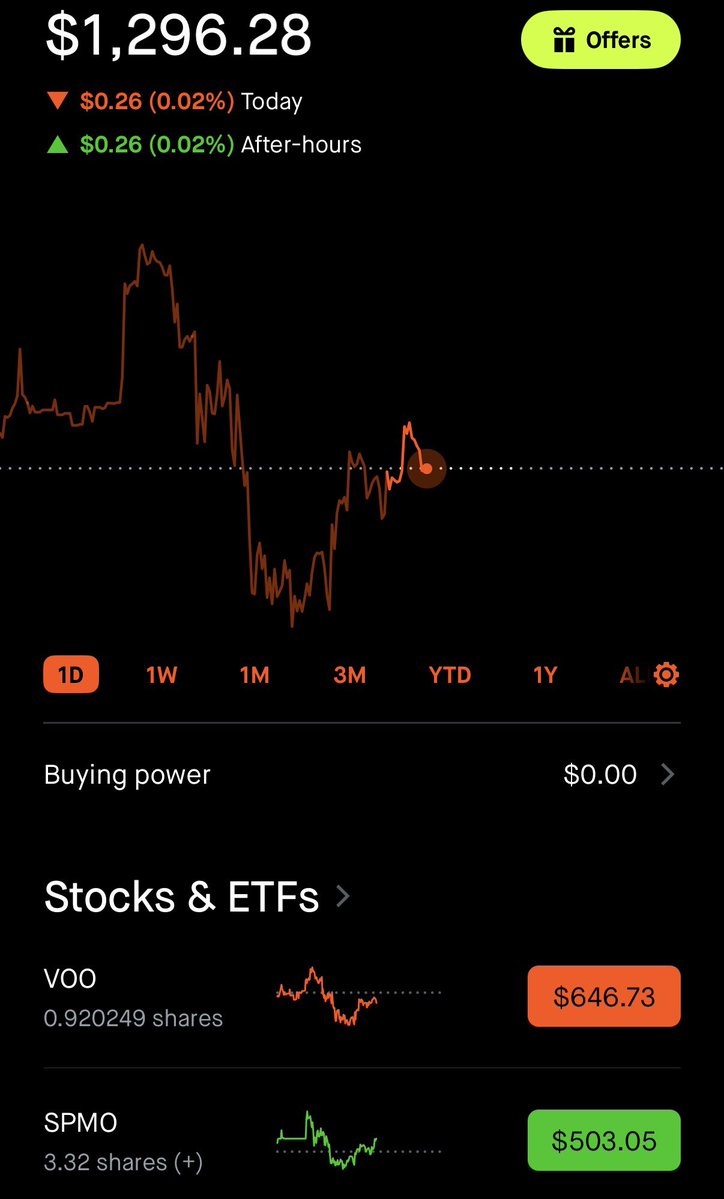
Placed the buy order for the underweight fund to bring my $VOO + $SPMO portfolio closer to 50/50.
A little more added, a little less left to go.
@Cernovich How true. whatever it takes to stay in the game longest. If you hit a big liquidity event, what diff does it make if you were 80% invested vs 100%? You saved countless sleepless nights and you avoid 1 mistake or bad break from wiping out 1000 good decisions
@BowTiedBull Indeed, will be revisiting when the time comes for now renting is fine for me until I get a family. Will def pay for propwire or who knows what ai will be able to assemble by then. Exciting times!
@SCHDaccumulator I used to eat Chipotle back in school. Cheapest I’ve eaten and best shape I’ve been in was doing dump-and-go Instant Pot meals. $2–3 a serving shopping the sales. Recently had Muse find recipes and order ingredients. Imagine automating that every week lol, crazy ROI.
@BowTiedBull In these areas i looked at, there’s also a deluge of remodels or complete teardowns for customs almost constantly since covid. It’s akin to the nobles throwing up castles on the most defensible spots in feudal era
Went on propwire, filtered for >= 3x median price AND (absentee owner OR low debt OR multiple properties)
Absolutely astounding how deep ITM these owners are. A huge portion got token loans around 3% during covid prob just to throw into other investments. Imagine a fixed 30y 2.75% non-recourse (not all states) cost of capital. Nuts.
Btw this is also a great way to decide where to stay when traveling stateside. Or just look at where the highest end grocery stores are.
@DividendMil I'm stuck at 10k too. watch out for how some merchants code. I've gotten only 1x points instead of 3x. they also bury the cash back option way down. they definitely are trying everything in their power to stay afloat on this card since it's too good haha
@SCHDaccumulator I remember around that time waking up early before school to catch cnbc and seeing it hit $1k. was crazy to see the cognitive dissonance then let alone now haha.
@kevinxu Love this. Taking emotion out of both the idea and the execution is a huge win. Would be great to see it extend to the maintenance side too, like keeping the portfolio rebalanced to the original thesis as prices drift.
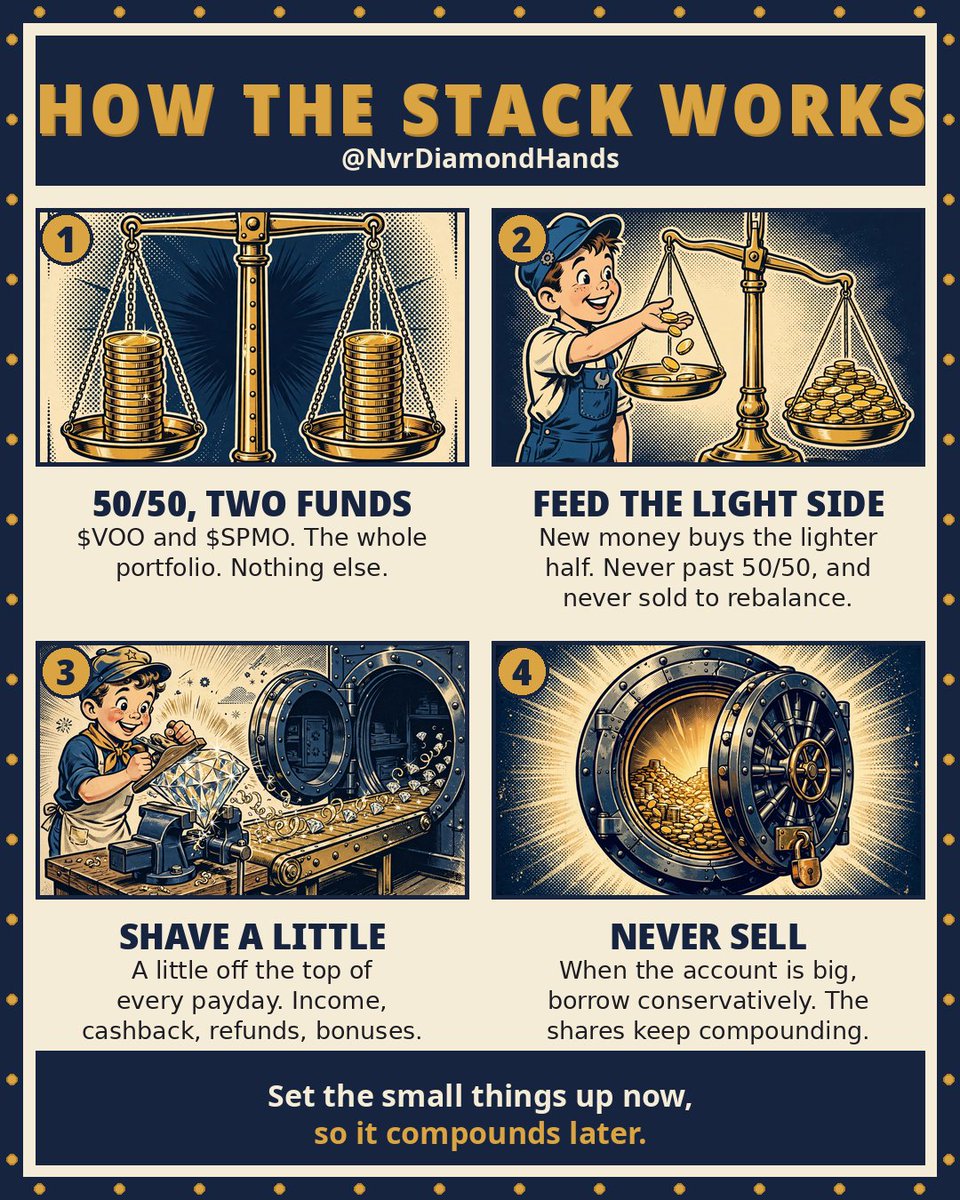
A few people asked what the actual system is. Here are all four rules on one card.
1. 50% $VOO, 50% $SPMO. That's the whole portfolio.
2. New money buys the lighter half. Never past 50/50, never sold to rebalance.
3. A little off the top of every payday. Income, cashback, refunds, bonuses. In, never out.
4. Never sell. When the account is big, borrow conservatively against it instead.
Set the small things up now, so it compounds later.