The HSA is the only account in the tax code with a triple tax advantage.
- Contributions go in pre-tax
- Growth is tax-free
- Withdrawals for qualified medical expenses are tax-free
Most people use it like a checking account. Swipe the card, spend it down every year.
The better play for many high earners: pay current medical bills out of pocket, invest the HSA, save your receipts.
A family maxing the 2026 limit ($8,750) for 25 years at 7%:
→ ~$553,000 (Illustrative.)
There's no deadline to reimburse yourself for qualified expenses incurred after the HSA was opened.
Requires an HSA-eligible high-deductible health plan. 2027 limits: $4,500 self-only, $9,000 family.
Your HSA might be the best retirement account you're not using as one.
The deadline to fund your 2026 401(k) is December 31.
The deadline to fund your 2026 IRA is April 15, 2027.
Most high earners treat those like the same date - and leave a full year of workplace contributions on the table.
Here's the calendar that actually matters: ↓
19 midterm elections since 1950. 19 times the S&P 500 was higher a year later.
Average gain: about 15%.
Last week my group chat went from "Let's go!" to "PAIN" in 24 hours.
Here's why the election shouldn't touch your plan: ↓
I’ve seen a lot of comments and quote tweets on this post, and it’s remarkable how many people have no understanding of how taxes work.
Our tax brackets are MARGINAL.
That means each bracket only applies to the dollars that fall inside it. Moving into a higher bracket doesn’t raise the tax on all your income. It only changes the rate on the dollars above the line.
Think of it as buckets.
Your income fills the 10% bucket first. Then the 12% bucket. Then the 22% bucket.
Each bucket keeps its own rate.
Here’s the math for a single filer earning $76,600 in 2027:
Subtract the $16,600 standard deduction → $60,000 taxable
- First $12,800 at 10% = $1,280
- Next $39,225 at 12% = $4,707
- Last $7,975 at 22% = $1,754.50
Total federal income tax: $7,741.50
That’s 10.1% of what they earned.
“In the 22% bracket.” Paying about 10%.
Now give that person a $5,000 raise.
Every new dollar lands in the 22% bucket.
→ $1,100 in additional federal income tax
→ They keep $3,900 (before payroll and state taxes)
Moving into a higher bracket can’t cost you more than the raise. It only taxes the new dollars at the new rate.
The two numbers you need to know:
Marginal rate = what your next dollar costs you. Use it for decisions like 401(k) vs. Roth or Roth conversions.
Effective rate = what you pay overall. Use it for perspective.
Markets got rocked yesterday.
S&P −4.4%. Nasdaq −5.5%.
Worst day since the April tariff shock.
Morgan Housel has 3 mindset shifts for exactly this moment you need to hear:
↓
*Anonymous People on X*
"An advisor is a waste of money, you can easily optimize everything on your own. Complete Scam"
*High Earners in Real Life*
"I work 60 hours a week, I have 3 kids under 5, I'm getting crushed on taxes, and I do not have the time or energy to give this the effort it needs. I'm willing to pay a premium to ensure my family is taken care of for the next 30+ years"
If I had to pick the one thing we hear about most from prospective clients, it’s taxes.
Usually it comes out as something like “we make good money, but it feels like a third of it is gone before we ever see it.”
And almost every time we pull up their benefits elections, there’s money being left on the table. Most people pick their elections once when they start a job and never look at them again. Benefits are a GIGANTIC part of your compensation package, yet most people only care about the salary
Here are a few of the most common things we end up addressing:
1. Contributing to the 401(k) only up to the match. The match is a great start, but the max this year is $24,500. Every dollar between the two lowers your taxable income.
2. Skipping the HSA. If you’re on a high-deductible plan, you can put in up to $4,400 for yourself or $8,750 for a family. It goes in pre-tax, grows tax-free, and comes out tax-free for medical expenses. Through payroll, it skips FICA too.
3. Paying for daycare with after-tax dollars. A Dependent Care FSA lets you run up to $7,500 of childcare costs through pre-tax payroll.
A few others:
Missing the mega backdoor Roth. If your plan allows after-tax 401(k) contributions with in-plan Roth conversions, you can add tens of thousands a year in Roth savings.
Overlooking a 457(b). If you work for a hospital, government agency, or nonprofit, you may have one available that stacks on top of your 403(b).
And a few smaller ones: a limited-purpose FSA alongside your HSA for dental and vision, commuter benefits for transit and parking, and for higher earners, a deferred comp plan that can shift income into years when you’re in a lower bracket.
To be fair, not everyone can or should max all of this.
Cash flow and an emergency fund come first, and money in a 401(k) isn’t money you can easily get to. But you should know what each of these is worth before you decide to pass on it.
Open enrollment is happening right now at most companies, and once you submit, your HSA and FSA elections are pretty much set for 2027.
Every dollar matters, and the low-hanging fruit is the easiest place to start.
Every once in a while, a prospective client fills out our intake form and under “what are you looking for help with?” it just says:
“Investments.”
This brings up one of the most important conversations in financial planning.
Yes - your investments are an extremely important part of your financial plan.
But the PLAN is vastly more important.
Your investments serve one purpose: funding the life you want for your family.
Let’s put numbers to it:
Person A: Age 40, $5M saved.
Wants to be work optional next year.
Family spends $1M/year.
Not even close without drastic lifestyle changes
Person B: Age 40, $1M saved.
Family spends $40k/year.
May never need to work again depending on other factors
5x the money. Completely opposite outcomes.
The number on your statement means nothing on its own.
It only matters relative to:
What your life costs
When you want work to be optional
How much you keep after taxes
How your cash flows month to month
We see this constantly - people focused on returns while the bigger levers sit untouched.
Every situation is unique. That’s why investments can’t live in a silo. They need to be coordinated with tax planning, cash flow optimization, protection, and estate planning.
Investments are the tool, but the plan is the point
Last year, my wife and I got hit with $32,000 in medical bills.
After the phone trees, coding errors, and resubmitted claims, the final number came in. We owed about $1,000.
On this app you hear everything's a scam: from insurance to 401ks - until the day it isn't: ↓
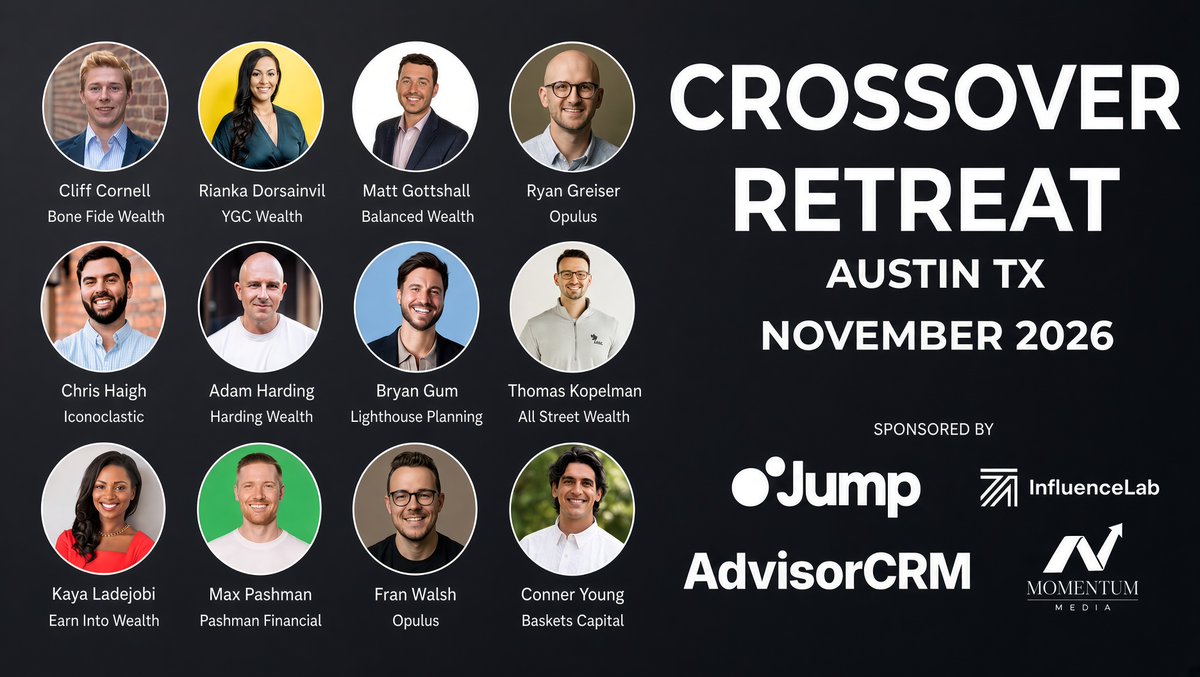
Heading to Austin next month for the first Crossover Retreat.
Going to be in a room with some of the best young firm owners in the U.S.
Looking forward to learning how they’re building systems, using AI, and growing their firms.
BIG ANNOUNCEMENT! 🚨 🚨 🚨
We have been keeping a HUGE SECRET. We’ve been planning the biggest surprise event for almost a whole year for financial advisors that are building the best practices in the US.
Our podcast, Advisor Freedom, has (amazingly!) exploded over the last 18 months and has been so much fun to run.
We thought the greatest way to celebrate that is to do the opposite of what every podcast seems to do (World Tours) and instead host an awesome and massive event for incredible financial advisors in Austin TX!
Soooo, we are excited to host the Inaugural Crossover Retreat!
I am obsessed with learning from other financial advisors (especially these superstars) on how they’re building their practices, growing their firms/social media reach and utilizing AI everyday.
That’s exactly what Crossover is for. Sharpening with and learning from some of the best minds in the same room.
If you want more info comment CROSSOVER and I'll send you info and event details.
Big thank you to our sponsors: @JumpAdvisorAI , AdvisorCRM , InfluenceLab and Momentum Media
Excited to explode with this year’s cohort!
@cliffcornell_ - Bone Fide Wealth
@Rianka_D - Founder, YGC Wealth
@matt_gottshall - Balanced Wealth Group
@Greiser - Co-founder, Opulus
Bryan Gum - Founder, Lighthouse Planning
@iconocapital - Founder, Iconoclastic Capital
@hardingwealth - Founder, Harding Wealth
@TakeActionCopy - Founder, Influence Lab
@TKopelman - Co Founder, All Street Wealth
Kaya Ladejobi - Founder, Earn Into Wealth
@maxpashman - Founder, Pashman Financial
@FranWalsh73 - Co Founder, Opulus
And we’re not done with surprises (👀)… Stay tuned!!!
Social Security went viral again last week - dividing generations into a debate.
My full thoughts below, and how to build an 8 step plan that doesn't rely on Politicians 👇
https://t.co/CPVqRU0eKc
Two investors. Same $250,000. Same strategy. Same market year.
One gets a tax bill for $1,785 without selling a single share.
The other owes $0.
The difference isn't the portfolio. It's the wrapper it came in: ↓
Roughly 30% of Americans have a written financial "plan."
That means 7 out of 10 people are winging their financial future with no roadmap.
It's probably even more than that.
Here’s how to fix that - 8 core steps to build a rock-solid financial plan that actually works ↓
My dad did the responsible thing. He bought life insurance.
$250k. Sole earner. 5 young kids.
No one ever told him that wasn't close to enough.
It's the reason I became a financial planner ↓
Most high earners think the 401(k) limit is $24,500 in 2026.
That's just the employee contribution limit. The actual IRS limit is $72,000.
The $47,500 gap? One of the most common things we see left on the table.
Here's how to access it ↓
Most six-figure earners don't have a budgeting problem.
They have a systems problem.
Wealthy people don't track every dollar.
They build systems that run on autopilot - so the right things happen whether they're watching.
5 systems every high earner needs: ↓
A 15-year-old's summer job can turn into $1.7M by retirement - without them saving a single dollar of their own paycheck.
Most parents have never heard of the account that makes this work: ↓