I don’t think Bitcoin is selling off because of MSTR
I think it’s being tapped to fund the market’s upcoming hot ball of money trades: SpaceX, Anthropic, whatever else everyone suddenly “has to own”
This means in the future, the correlation breakdown will itself become the fuel
The happenings:
- @brix_money announced 5.5m raise, live on Mon (~40% apy carrytrade)
- https://t.co/0oY4jS2CQD was overhauled in extreme detail
- @getubitel has been offering worldwide data plans
- @hitdotone uncapped their beta last week and drove more 24hr perp volume than several entire chains
- @PrismFi_ integrated polymarket settlement on their frontend
- @AveForge teased their second game mode (bullet hell style)
- @Tulpea_org raised 100k for their first RWA vault
- @MegaCorpHQ announced their mint date for pilot licenses. These give ability to mine for $1M (real) prize
- @worldmarketsinc perps went live
- @GMX_IO came online
- @TopStrikeIO proved to be an actually sticky app
- @NextRare_cards came online, settling their multichain gacha on MegaETH
- @ferdybet went crosschain
- @aori_io worked with us to offer 1:1 stablecoin bridging on https://t.co/ruCkmbZToE (soon all aggs).
- @ethena USDe was added to @aave, but it's actually sUSDe and allows for looping the yield
- @megatruther's new game caught fire with it's shorter epochs
- @_canonic new MAOB spot CLOB is somehow offering some of the tightest spreads on the chain
- @gains_trade brought OIL/commodities to USDm
- @purrlend moved over and kicked off their merkl incentive campaign
- @agntsocial built a social layer for agents
Novel things to watch for the next ~2wk:
@trychisino@blackhaven@stripyield@NxTerminal@BackedApp + @DuonLabsHQ@premarket_xyz
There will never be fewer apps than there are right now. There will never be fewer tx than there are right now.
We've been cooking too. More soon.
ethena generated $666m in annual fees on a $780m market cap. price-to-fees ratio of 1.17x. the fee switch isn't even turned on yet. $50m revenue in a single day on march 26. 88% of USDe backing shifted to t-bills, blackrock BUIDL reserves, first GENIUS-compliant stablecoin. they're licensing the entire stack to new chains as white-label stablecoins. jupUSD, USDm on megaETH, suiUSDe all running on ethena infrastructure. $131m deployed and growing. every new L1 and L2 launching with an ethena-backed dollar is permanent demand for USDe collateral. ENA holders currently receive zero percent of that $666m. the moment that fee switch activates at even 50% share, that's $333m flowing to stakers on a token priced under 10 cents. do the math on that yield at current market cap
Leveled up in the Great Gas Reckoning with ETHGas! 💪
Hero Jack status: 1.6133 ETH gas spent, 1000 Beans earned—supporting the Gasless Future!
Claim your Gas ID at https://t.co/xBDXOoCk9r
Do crypto traders have an edge in equities?
The answer here is nuanced.
Crypto is pure in the sense that most coins trade solely on attention, narrative, price action, charts, and memetic consensus. It's the most vibes-based asset class.
Traders who have done well in crypto are well versed in these particular skillsets. In crypto, these factors are the pillars of having sustainable edge.
That said, equities are different because they have real fundamentals, and thus offer a lot of information to be analyzed. Different parts of the equity market have differing proportions of fundamental vs. meme, but for the most part, none are as pure as crypto in that sense.
Every 3 months, earnings rear their ugly head and that means fundamentals can shatter the narrative or chart by dumping a lot of incremental information.
The universe of equities is immense, with thousands of names, so even initial table selection is more difficult than in crypto. In crypto, if you have been around for a while and have a decently curated TL + group chats, you will instinctively know the hot play of the moment. In equities in can be quite difficult to get your bearings if you are starting from scratch.
The reality is that the amount of information to digest and analyze in equities is infinitely greater than in crypto. For the most part, crypto does not stress this skillset very much. Many of the sharps that I know, who have moved over from crypto to equities and done well, have this in spades. Not everyone does.
As a participant in the equity market, you are trading against people who know way more than you. A meaningful part of the discretionary capital in equities is driven by sector experts who have covered a given sector for years, and know everything there is to know about it. They meet with the management teams regularly, talk to industry experts for channel checks, get proprietary data, etc. Of course this can lead to myopia as well, but as a general rule, you are starting off with a negative edge.
You have to know whether an earnings print was good or bad, whether a catalyst was good or bad, and the exact magnitude relative to expectations, in order to feel out the price action relative to the news.
Not just at a security specific level, but the overall market structure for equities is much more complex. There are many different layers of market participants with vastly varying styles and signatures, and the options market is a massive driver.
Being able to see across the breadth of the market and understanding sector rotations and flows are a big part of assessing overall market dynamics. In crypto this is easy. In equities this is overwhelming due to its sheer size and complexity. It's doable but it takes a lot of bandwidth.
The skillsets I mentioned before, attention, narrative, price action, charts, and memetic consensus, can help overcome this. Ultimately it becomes a matter of weighing out the positive edges and the negative ones.
On the other hand, equities (esp. US equities) are much more forgiving in the sense that beta is on your side, given the passive inflows into the asset class. So there is a natural beta tailwind that offsets any negative edges from an alpha perspective, particularly in larger cap US stocks. Probabilistically, someone will do much better buying a random S&P500 stock than a random CMC Top 500 coin, this goes without saying.
Not only that, but the lower volatility also lowers the psychological intensity, and makes it less likely to force you into mistakes.
Given this element, if someone does not have the edge to generate alpha, it's better to acknowledge this and shift to being longer-term focused, to harvest the beta instead.
I would guess that many crypto traders are not fully aware of how much the social layer has been a part of their success. In other words, the degree to which their compounded social connections and informational network have helped them make money in the space, instead of other edges. This does not transfer over in a new asset class and will fully reset.
I know this is not necessarily the most hopeful message, but it is an honest one. I do think very sharp people can move over and crush it. Given this slow period as we approach year end, it's worthwhile to spend some time being transparent with yourself, assessing the state of your process as a trader, and understanding what your strengths and weaknesses are. No matter what, you can grow on every dimension, though natural abilities also matter.
lock in.
its not the best time to touch grass, not the time to disengage.
and definitely not the time to be a tourist thinking “I’ll be back when markets look good.”
by then, it’s usually too late.
this is usually when the next rotation quietly starts forming and you only catch it if you show up every day.
one thing I’ve learned watching multiple cycles is that wealth in crypto rarely rotates into the same ideas twice.
it doesn’t move from one meme to its sequel. it moves from old attention to new curiosity.
that’s why so many people get stuck waiting for the next version of what already worked. most of the time, that’s where capital gets trapped.
real rotations usually begin somewhere new:
- new tech
- new behavior
- new use cases
- or a catalyst most people aren’t watching yet
and they usually start when things feel messy, boring, and unclear like the market right now.
to catch it, you need to be present.
I didn’t catch things early that made me money because of luck.
I caught them because I was around, paying attention and had dry powder when it mattered.
so yeah lock in. stay patient. keep some chips ready and show up everyday
that’s how you stay in the game long enough to catch the real rotation.
In Defense of Exponentials
I used to tell founders, the reaction you are going to get to your launch is not hate, it’s indifference. By default, nobody cares about your new chain.
I have to stop telling them that now. Monad just launched this week, and I’ve never seen so much hate about a blockchain that just launched. I’ve been investing into crypto professionally for 7+ years now. Before 2023, almost every chain I’ve ever seen that launched was mostly met with enthusiasm or indifference.
But now, new chains are born into a chorus of hate. The amount of haters I’ve seen for projects like Monad, Tempo, MegaETH—before they even hit mainnet—is a genuinely new phenomenon.
I’ve been trying to diagnose: why is this happening now, and what does it mean about the psychology of this market?
The Cure is Worse than the Disease
Forewarning: this is going to be the vaguest blockchain valuation post you ever read. I don’t have any fancy metrics or charts to sell you on. Instead, I’ll be arguing against the zeitgeist of Crypto Twitter, which for the last couple of years, I’ve been constantly on the opposite side of.
In 2024, I felt like what I was arguing against was financial nihilism. Financial nihilism is the belief that none of these assets matter, it’s all memes at the end of the day, and everything we’ve built is inherently worthless.
Thankfully, that’s no longer the vibe. We have broken out of that spell.
But the zeitgeist now is what I’d call financial cynicism: OK, maybe some of this stuff has value, maybe it’s not all memes, but it’s grossly overvalued and it’s only a matter of time before Wall Street finds that out. Not that all chains are worthless. But these things are all maybe worth 1/5th-1/10th of what they’re currently trading at (have you seen these PE ratios?), and so you’d better pray like hell Wall Street doesn’t call us on our bluff, because once they do it’s all getting wiped out.
You’ve got many bullish analysts now trying to conjure up optimistic L1 valuation models, inflating PE ratios, gross margins, DCFs, trying to fight against this mood.
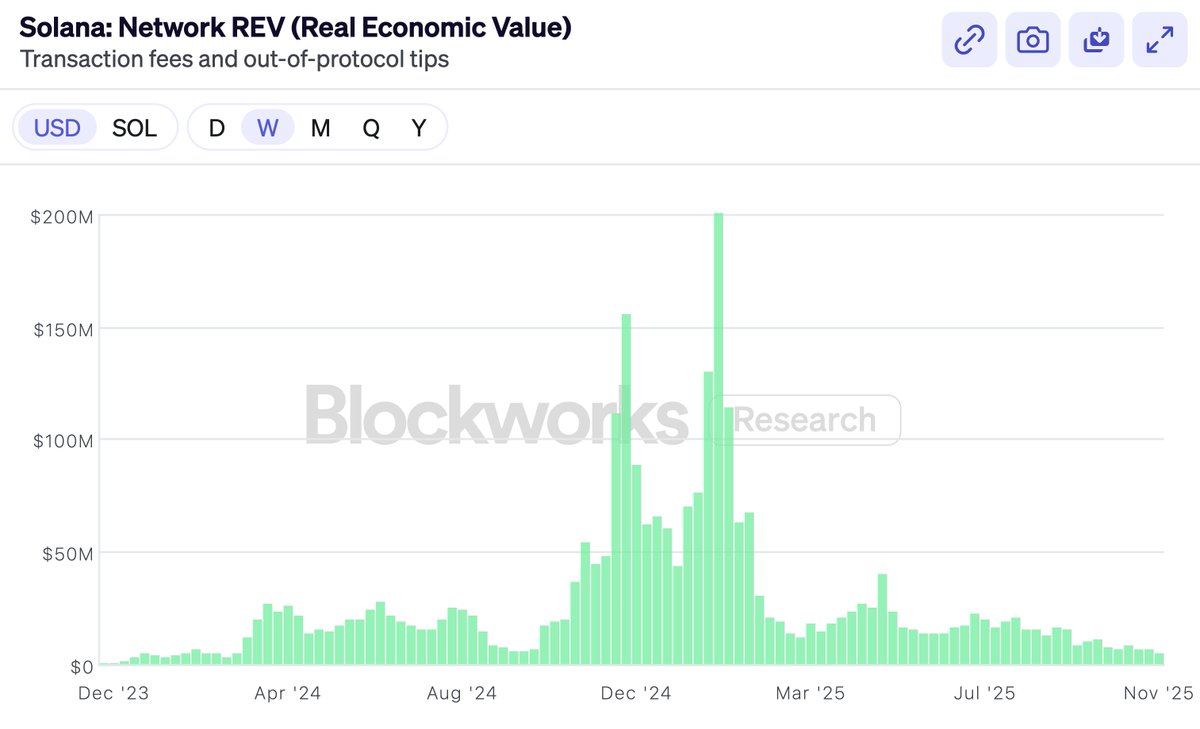
Late last year, Solana very proudly embraced REV as a metric that could finally justify their valuation. They proudly announced: we—and only we—are no longer bluffing to Wall Street!
And, of course, almost immediately after REV was embraced, it fell off a cliff (though $SOL, tellingly, did better than REV did).
Not that there’s anything wrong with REV. REV is a very clever metric. But the point of this post is not metric selection.
Then came the launch of Hyperliquid. A DEX that had real revenue and buybacks and PE multiples. And the chorus said—look, look I told you! Finally, for the first time ever, a token that has some real profits and a proper PE multiple. (Nevermind BNB, we don’t talk about that.) Hyperliquid will eat everything because obviously Ethereum and Solana don’t make any real money, we can stop pretending to value them now.
Hyperliquid, Pump, Sky, these buyback-heavy tokens are all great. But the market always had the ability to invest into exchanges. You could always buy Coinbase, or BNB, or whatever. We own $HYPE, and I agree that it’s a fantastic product.
But that’s not why people were investing in ETH and SOL. The fact that L1s don't have exchange-like profit margins is not why people were buying them—if they wanted that, they could’ve bought Coinbase stock.
So if I’m not critiquing blockchain financial metrics, maybe you think this post is going to be chiding the sinfulness of the token-industrial complex.
Obviously, everyone has lost money on tokens in the last year, VCs included. Alts are down bad this year. And so the other half of the zeitgeist on CT is arguing about who's to blame. Who’s become greedy? Are the VCs greedy? Is Wintermute greedy? Is Binance greedy? Are the farmers greedy? Are the founders greedy?
The answer, of course, is the same as it’s ever been.
Everyone is greedy. Everyone. The VCs, Wintermute, the farmers, Binance, the KOLs, they're all greedy, and you are greedy too. But it doesn't matter. Because no functioning market has ever required anyone to act against their self-interest. If we're right about crypto, we can all be greedy and the investments will still work out. Trying to analyze a market that has gone down by figuring out “who’s greedy” is going to be about as fruitful as commissioning witch trials. I guarantee you, nobody just started being greedy in 2025.
So this, too, is not what I’m going to be writing about.
Many people want me to write a post about why $MON should be valued at X or $MEGA at Y. I’m not interested in writing this post, or advocating that you buy anything in particular. In fact, you probably shouldn’t buy any of them if you don’t already believe in them.
Will any new challenger chain win? Who knows. But if it has a material chance of winning, it's going to be priced on that basis. If Ethereum is worth $300B or Solana is worth $80B, a project that has a 1-5% chance of becoming the next Ethereum or Solana will be priced according to those probabilities.
Somehow CT is scandalized by this, but it’s no different than Biotech. A drug that has less than a 10% chance of curing Alzheimer's is priced by the market as worth billions of dollars, even if 90% chance it won’t pass stage 3 trials and will go to 0. That's how the math works—and turns out, markets are pretty good at doing math. Binary outcomes are priced on probabilities, not on run rates or moral turpitude. It’s the “shut up and calculate” school of valuation.
I really don’t think that’s an interesting question to write about. “5% chance to win? No way, that’s clearly a 10% chance!” Markets, not articles, are the best way to assess that for any individual token.
So here’s what I am going to write about: CT doesn't seem to believe anymore that chains are valuable.
I don’t think this is because they don’t believe new chains can win market share. We just saw Solana dominate market share after emerging from the ashes less than 2 years ago. It’s not easy, but of course it’s possible.
It’s more that people have come to believe that even if a new chain wins, there’s no prize worth winning. If $ETH is just a meme, if it’ll never generate real revenue, then even if you win, you won’t be worth $300B. The contest is not worth winning, because these valuations are all bunk and it’ll all come crashing down before you go to claim your prize.
Being optimistic about chain valuations has become passé. Not that nobody is optimistic—obviously there must be optimists out there. For every seller there’s a buyer, and as much as CT cool kids love to drag L1s, people are comfortable buying SOL at $140, ETH at $3000.
But there’s a perception now that all the smartest people are over buying smart contract chains. Smart people know the jig is up. If not now, then soon. The only people buying here are suckers—Uber drivers, Tom Lee, and KOLs who say stuff like “trillions.” And maybe the US Treasury. But not the smart money.
This is bullshit. I don’t believe it, and you shouldn’t either.
So I felt like I had to write a smart person’s manifesto on why general purpose chains are valuable. This post is not about Monad or MegaETH. It’s really in defense of ETH and SOL. Because if you believe ETH and SOL are valuable, the rest is straight downstream.
Defending ETH and SOL valuations is generally not my job as a VC, but fuck it, if nobody else is willing to do it, then I’ll write it.
Feeling the Exponential
My partner Bo experienced the Chinese Internet boom first-hand as a VC. I’ve heard how “crypto is like the Internet” so many times now that it doesn’t even register for me anymore. But when I hear his stories, it always reminds me how costly it is to be wrong about these things.
A story he often tells is about when all the early e-commerce VCs (it was a small group back then) got together for coffee in the early 2000s. They debated: how big is the market for e-commerce going to be?
Is it going to be mostly electronics (maybe only techies will use PCs)? Could it ever work for women (perhaps they’re too tactile)? What about food (maybe impossible to manage perishables)? These were deeply important questions for early VCs to decide what to invest in and what prices to pay.
The answer, of course, was that literally every single one of them was devastatingly wrong. E-commerce would sell everything, and the target audience was the whole fucking world. But nobody at the time actually believed it. And even if they did, it would be too absurd to say out loud.
You just had to wait long enough for the exponential to show you. Even among the believers, very few thought e-commerce would become as big as it became. And those few who did, almost all of them became billionaires from just not selling. Every other VC—as Bo tells me, since he was one of them—sold too early.
It has become passé in crypto to believe in the exponential.
I believe in the crypto exponential. Because I’ve lived it.
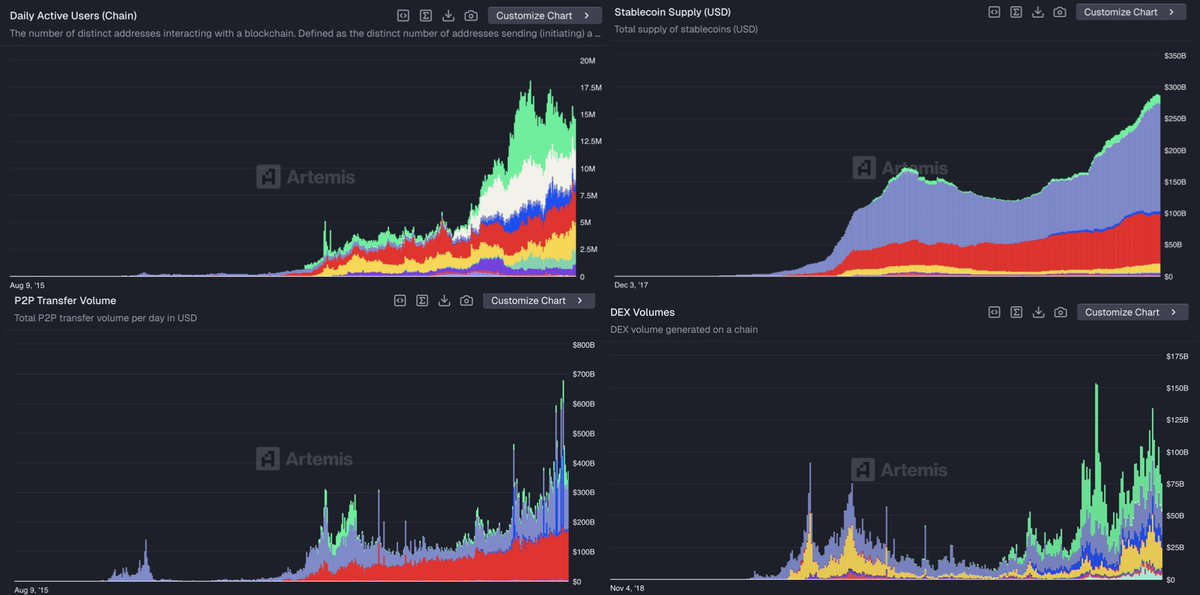
When I started in crypto, nobody used this stuff. It was tiny and broken and awful. TVL on-chain was in the millions. We invested into the first generation of DeFi, MakerDAO, Compound, 1inch, back when they were science projects. I remember playing around on EtherDelta back when DEXes traded single digit millions a day, and that was considered to be a huge success. It was complete dogshit. Now we routinely trade in the tens of billions on-chain every day. I remember believing it was crazy that Tether hit a billion dollars in issuance and was being written up in the NYT as a ponzi scheme on the brink of shutdown. Now stablecoins are over $300B and regulated by the Federal Reserve.
I believe in the exponential because I’ve lived it. I’ve seen it over and over again.
But you might respond—well, stablecoin growth might be exponential, maybe DeFi volumes are exponential, but they don’t accrue to ETH or SOL. The value doesn’t get captured by the chains.
To which I answer: you still don’t believe in the exponential.
Because the exponential’s answer is always the same: it doesn’t matter. This stuff is going to be so much bigger than it is today. And when it’s absolutely enormous, you’ll make it up on scale.
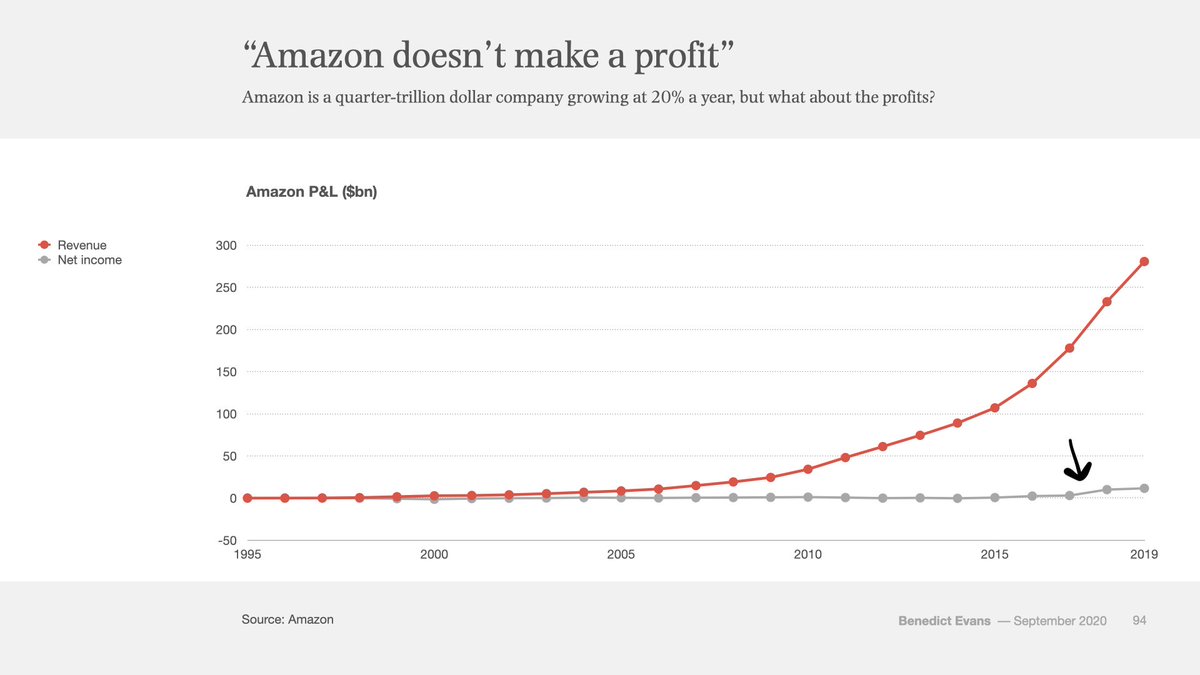
Study this chart.
This is Amazon’s P&L from 1995 to 2019. That’s 24 years. Red is revenue, gray is profit. You see that little blip on the end where the gray line goes up? That’s when, 22 years in, Amazon started actually making a profit.
Amazon was 22 years old when this little gray line of net income first peeled off of 0. Every single year before then, there were op eds and critics and short sellers claiming that Amazon was a ponzi scheme that would never make any money.
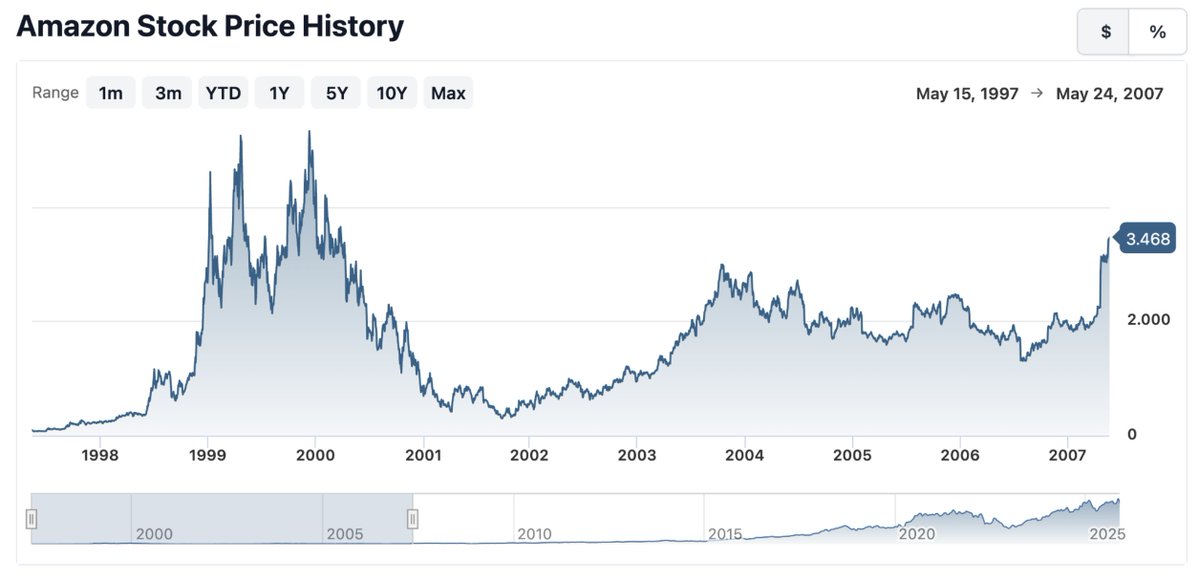
Ethereum just turned 10 years old. This is what the first 10 years of Amazon stock looked like:
10 years of chop. All along the way, Amazon was beset with doubters and non-believers. Is e-commerce a VC-subsidized charity? They’re selling underpriced cheap low-quality knick-knacks to bargain hunters, who cares? How are they ever going to make actual money, like Walmart or GE?
If you were arguing about Amazon’s P/E ratio, you were in the wrong regime. That’s the regime of linear growth. But e-commerce was not a linear trend, and so every single person for 22 years arguing about P/E ratios was devastatingly wrong. No matter what you paid, no matter when you bought, you were not bullish enough.
Because that’s what exponentials do. When it comes to truly exponential technologies, no matter how big you think it’s going to get, it just keeps getting even bigger.
This is the thing that Silicon Valley has always understood better than Wall Street. Silicon Valley was raised on exponentials, while Wall Street was raised on linearity. And over the last few years, crypto’s center of gravity has migrated from Silicon Valley to Wall Street. You can feel it.
Granted, crypto growth doesn’t look as smooth as e-commerce’s growth. It’s burstier, it goes in fits and starts. This is because crypto, being about money, is deeply tied to macro forces, and it also has more violent regulatory push and pull than e-commerce. Crypto strikes at the heart of the state—money—and so it’s more unnerving to governments than e-commerce ever was.
But the exponential is no less inevitable. It's a crude argument. But if crypto is exponential, then the crude argument is correct.
Zoom out.
Financial assets want to be free. They want to be open. They want to be interconnected. Crypto turns financial assets into file formats, makes it as easy to send a dollar or a stock as to send a PDF. Crypto makes it possible for everything to talk to everything. It makes it all 24/7, global, interconnected, and open.
That will win. Open always wins.
If there’s no other lesson I've learned from the Internet, it’s that. Incumbents will fight against it, governments will huff and puff, but eventually they will give up against the adoption, the generativeness, the sheer efficiency that this technology enables. It’s what the Internet did to every other industry. Blockchains are how that same trend will gobble up all of finance and money.
Yes—with enough time—all of it.
An old saying goes: people overestimate what can happen in two years, but they underestimate what can happen in ten.
If you believe in the exponential, if you zoom out enough, then it’s all still cheap. And it should humble you that every day, the holders outlast the sellers and naysayers. Big capital has a longer time horizon than CT swing traders might lead you to believe. Big capital has been trained through history not to fade big technologies. You know, the big gushy story that originally got you to buy $ETH or $SOL? Big capital believes that story and hasn't stopped.
So what exactly am I arguing?
I am arguing that applying P/E ratios to smart contract chains (the “revenue meta,” as it’s now called), is giving up on the exponential. It means you have consigned this industry to the regime of linear growth. It means you believe 30 million DAUs on-chain and <1% of M2 is it. Crypto is just one of the things in the world. A sideshow. It did not win. It was not inevitable.
More than anything, I’m arguing to be a believer. Not just a believer, but a long-term believer.
I’m arguing that this exponential will be bigger than anything else you’ve been a part of in your life. That this is your e-commerce. That you will look back when you’re old and tell your kids—I was there when it all happened. Not everyone believed it was possible, that whole societies could change, that all of money and finance would be transformed by programs running on decentralized computers that we collectively owned.
But it actually happened. It changed the world.
And you were a part of it.
Disclosure: These are my own views. Dragonfly is an investor in $MON, $MEGA, $ETH, $SOL, $HYPE, $SKY among many other tokens. Dragonfly believes in the exponential. This is not investment advice, but is advice of another kind.