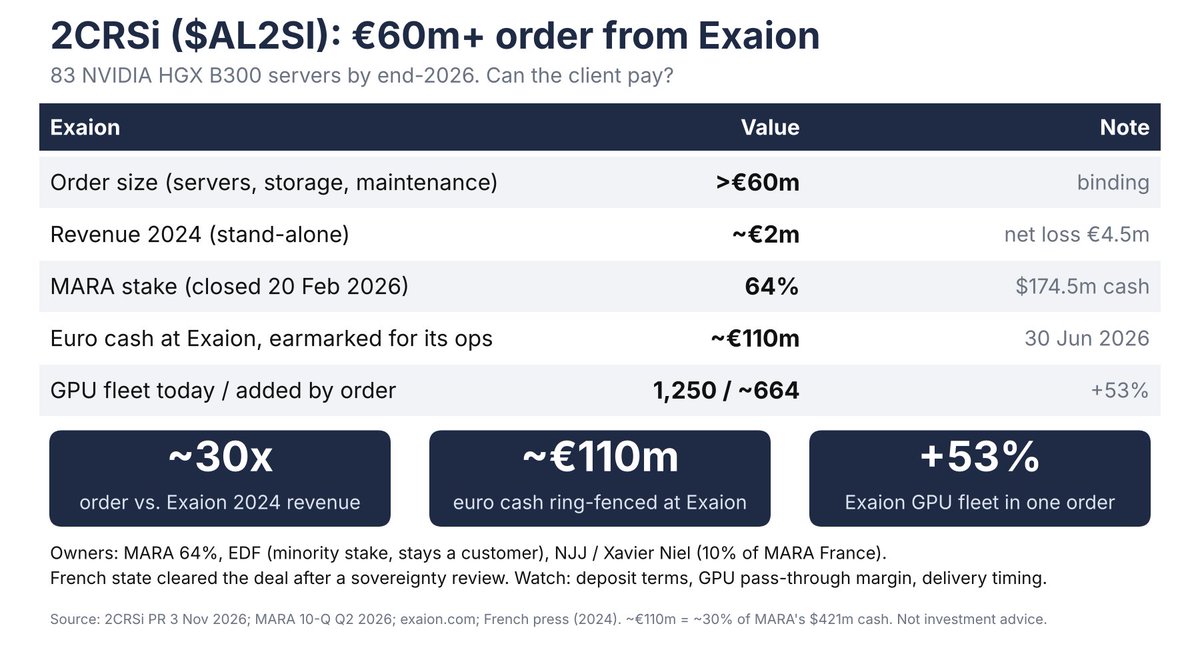
6) All in all, a real order with a real client. Payment risk is definitelly lower compared to #NYGC. 664 B300 GPUs lift Exaion's fleet by ~50% in one go. The gross margin of the order is the biggest question.
Not investment advice.
1) $AL2SI just announced a binding €60m+ order from Exaion: 83 NVIDIA HGX B300 servers plus storage and maintenance, to deliver by end-2026.
On its own, Exaion looks thin. French press reported ~€2m revenue and a €4.5m loss in 2024. This order is ~30x that.
5) On a positive note, $AL2SI named the customer. That lets investors check the counterparty, as above. A small but welcome step up in communication.
#2CRSI
9) Every number is from 2CRSi's own FY25/26 annual report. The arithmetic is mine, correct me if any figure is wrong. Not investment advice.
@ResearchGrizzly#Nvidia
1/ 2CRSi made €17.0m net profit in FY25/26. On surface, looks nice. Business is booming
Now remove ONE contract. The customer? It is CEO's own holding company (HAW).
EBIT drops from €18.7m to €4.6m.
Table made from the data in 25/26 the annual report
$AL2SI #2crsi
8) Valuation on core profit (22.6m shares):
€21.92 Friday close = €495m mcap ≈ 107x core EBIT
€13.57 today’s close = €307m ≈ 66x
Even after −38% in a day, that’s 66x for a 1.2% EBIT margin.
Cheap? You decide. 🤔
@Plaskpojken Hey, could you please share the link to 2025 Annual Statement. I could not find it neither in IR site, nor in Bloomberg, only a press release.