Pranav Construction
#Pranav#PranavConstruction
Inv PPT:
Ongoing+Upcoming projects GDV pegged at almost 3800+cr across 38 projects
24-36 months handover
Healthy revenue visibility for next 3 years
Good Q1FY27 on P&L side:
Rev at 164cr⏫16%
EBITDA at 29cr⏫41%
OPM at 17.81%⏫318 bps
PBT at 18.5cr⏫43%
PAT at 14.4cr⏫46%
PAT margins at 8.75%⏫179 bps
Under construction:
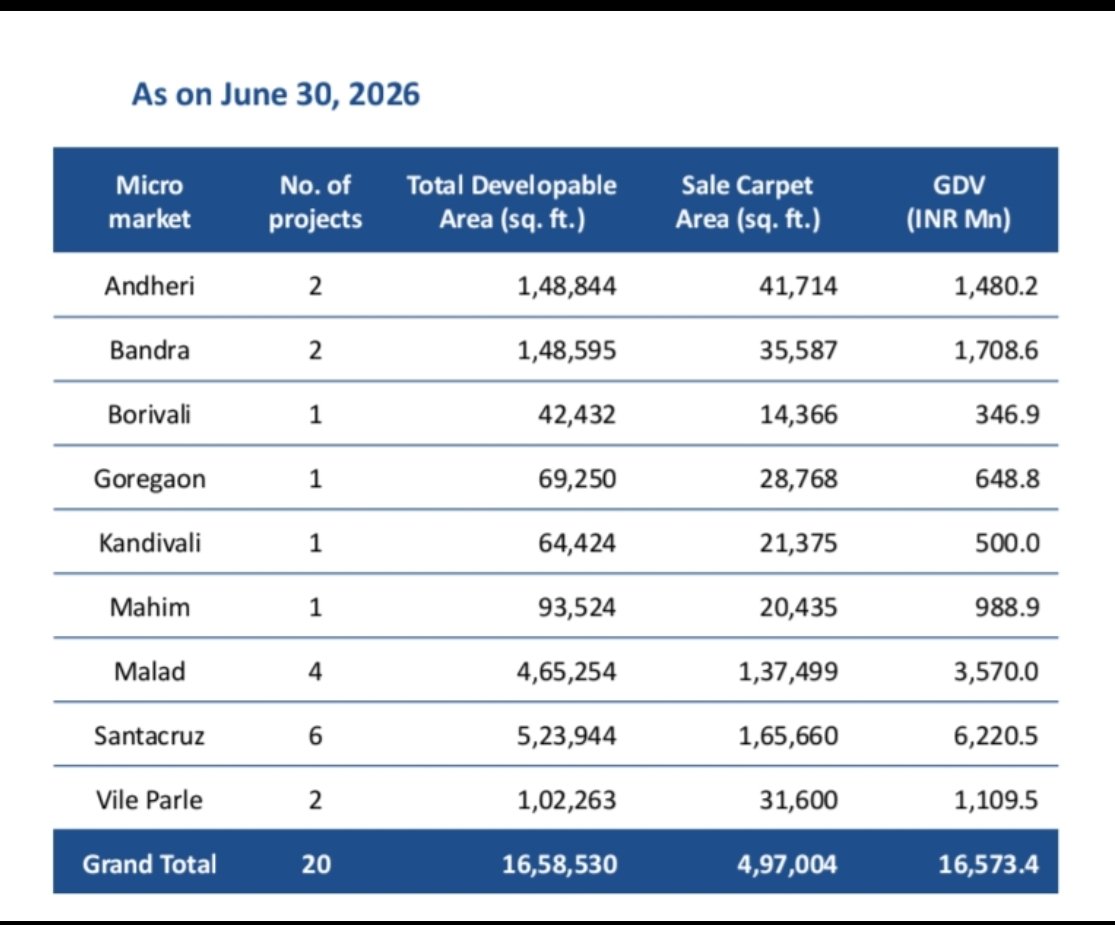
Total GDV of 1657cr across 20 projects
1.65 mln sqft
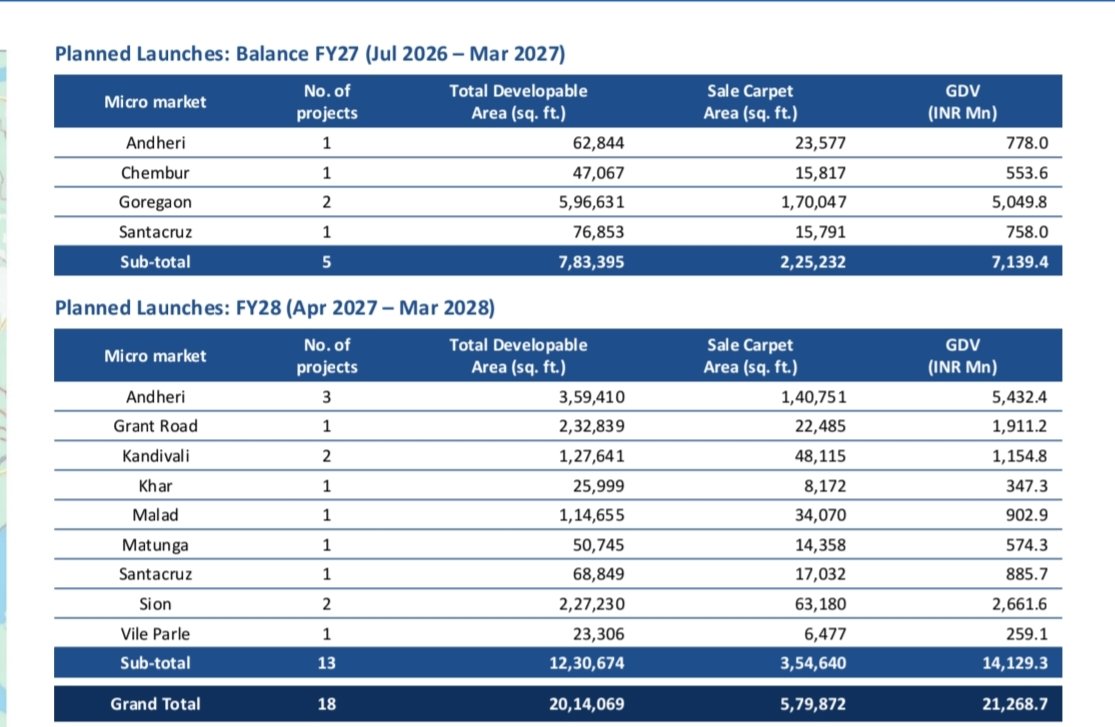
4 more launches planned in H2FY27
714cr GDV
18 planned launches for FY28
2.01 mln sqft
GDV pegged at 2127cr
Added 2 new redevelopment projects during Q1FY27
Asset light
Pure play redevelopment player
Timely completion
Strong track record of execution
2050+ units supplied
38 total projects
As of Q1FY27,
29 Completed projects worth 1.47 mln sqft
20 under construction worth 1.66 mln sqft
18 upcoming projects worth 2.01 mln sqft
11% mkt share in Malad micro market
9% mkt share in Santa Cruz micro market
Q1FY27:
Pre sales down at 90cr vs 109cr
Future pre sales to be driven by new launches
Avg realizations ⏫6.3% YoY at 39521/sqft vs 37187/sqft
Collections at 94cr⏫26%
5 new projects planned to be launched in H2FY27
Expects robust pre sales number for H2FY27
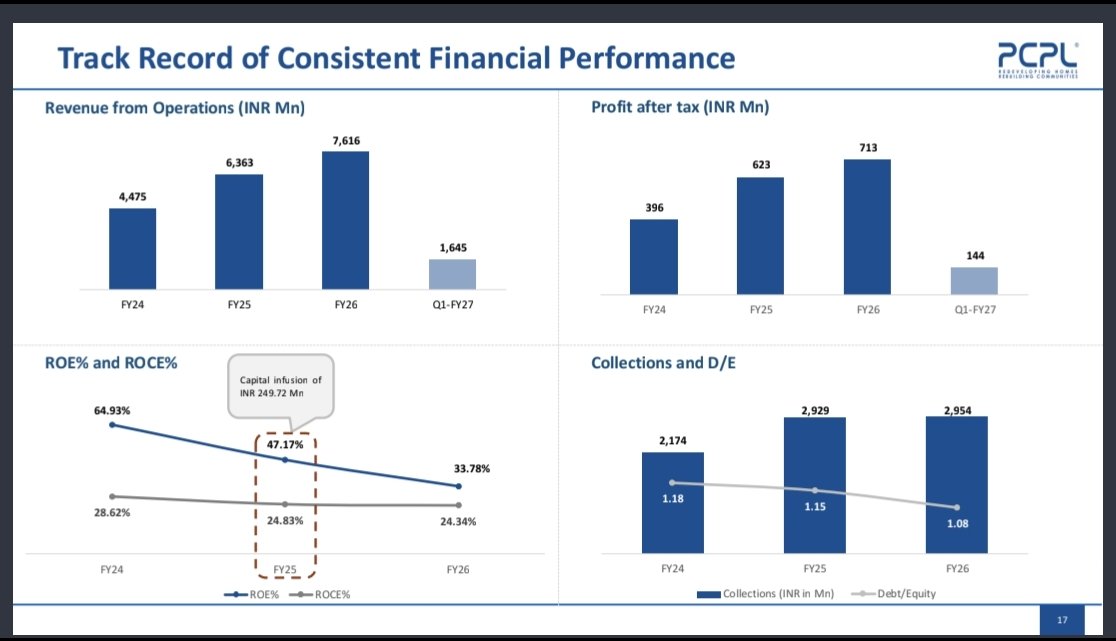
Last 3 years:
Rev:
FY24 448cr
FY25 636cr
FY26 762cr
EBITDA:
FY24 58cr at 12.8%
FY25 96cr at 15.2%
FY26 129cr vs 16.8%
PAT:
FY24 40cr
FY25 62cr
FY26 71cr
RoE 34%
RoCE 24%
D/E at 1.08x
OnEMI Technology Solutions
#Kissht
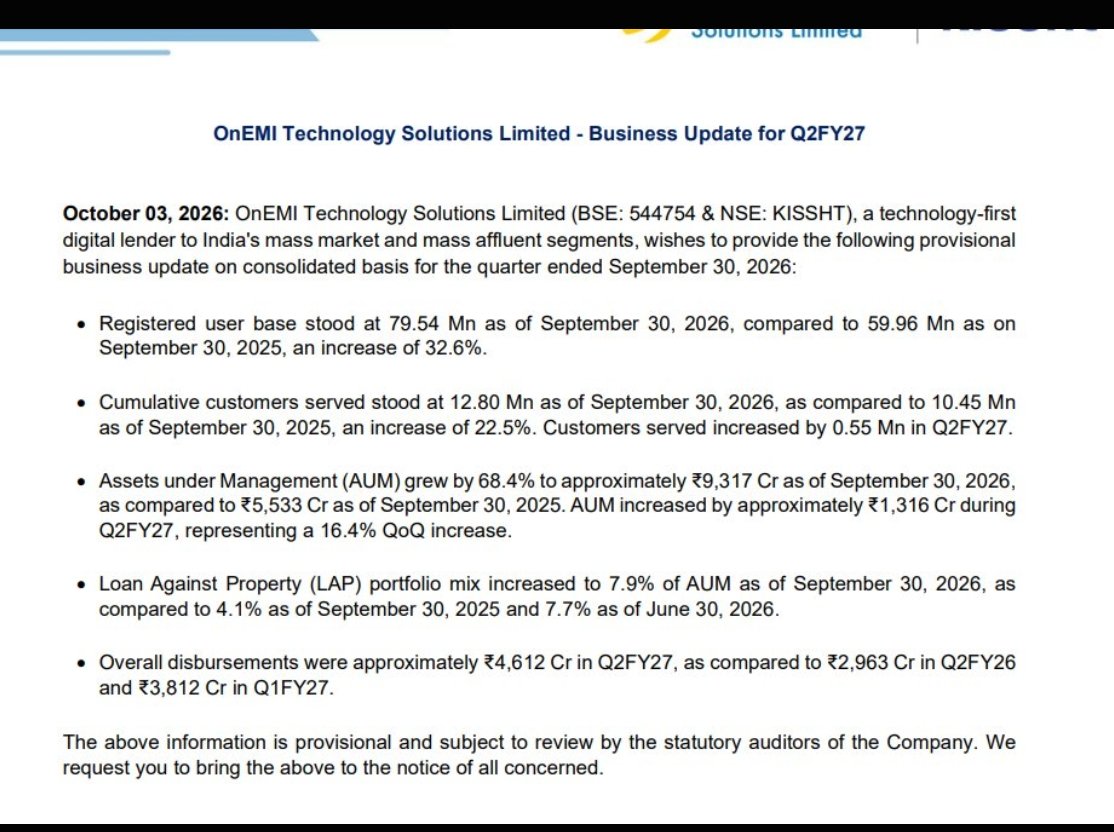
Good #Q2FY27 update with solid AUM uptick QoQ and YoY
Registered user base at 79.54 mln⏫33%
AUM ⏫ 68% at 9317cr
⏫16.4% QoQ which is an amazing uptick
Overall disbursements at 4612cr vs 2963cr
3/10/26
#Q2FY27
Hindusthan Insulators and Industries
#HIIL
First company to declare Q2FY27
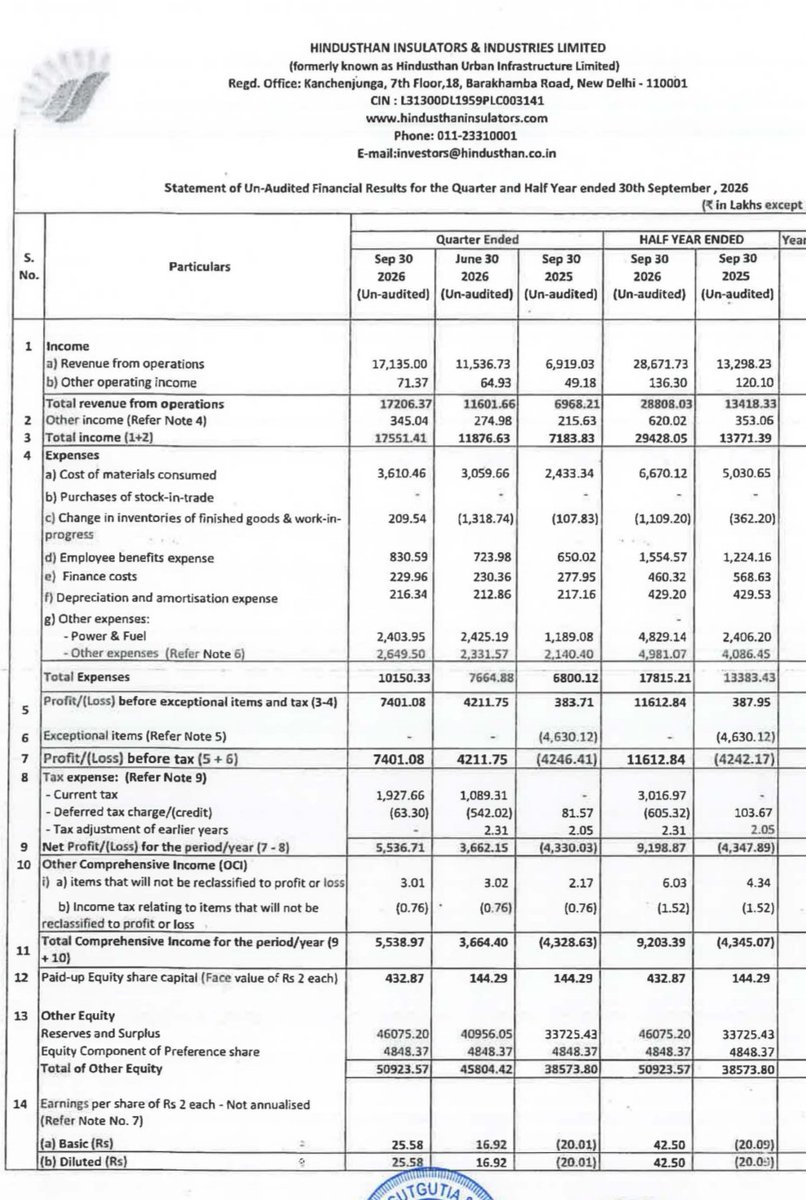
Solid Q2FY27 and H1FY27
Bumper #Q2FY27
Big QoQ and YoY uptick across all parameters
Rev at 171cr vs 69cr
Q1 at 115cr
PBT at 74cr vs 4cr
Q1 at 42cr
80%+ QoQ growth
PAT at 55cr vs loss
Q1 at 37cr
OCF at 71cr vs 5cr
#Good #Q2FY27 update:
Sedemac Mechatronics
Kissht(OnEMI Technology Solutions )
Ujjivan Small Finance Bank
L&T Finance
DMart
MOIL
Bank of India
Jammu Kashmir Bank
Bank of Baroda
Vedanta Aluminium
Vedanta Power
Continued
3/10/26:
Banks and NBFCs continue to deliver healthy growth QoQ and YoY
Solid advances, deposits and business growth
20%+ growth for most of them including PSUs
MFIs continue to see solid disbursements and AUM uptick with good asset quality
#Kissht and #SGFin are the standout performers till now from this segment
Good #Q2FY27 update:
Post 6pm
Karnataka Bank
Bajaj Finance
Bajaj Housing Finance
AU Small Finance Bank
Manipal Payment and Identity Solutions
#MPIManipal
Inv PPT:
Increasing opportunity size in all segments
Increasing exports
Geographical diversification
Q1FY27:
Rev at 419cr⏫48% YoY
⏫23% QoQ
EBITDA at 124cr⏫44% YoY
⏫32% QoQ
OPM at 30%
PAT at 78cr⏫129% YoY
⏫37% QoQ
International business at 15.3% vs 3.9% of revenues
Core business compounding :
Govt ID and kiosk programs
International business scaling up:
5 regions
APAC,ME,Africa,UK&Europe,Americas
Nigeria bureau fully operational and certified
Emerging engines scaling up:
Growing at 2.3x
Metal card portfolio expanding with 10+ varaunta across top issuers
Tax stamps win adds multi year Long term revenue
Q1FY27 had 7.7cr incremental costs as seeding and development costs for new initiatives
FY23���FY26: strong growth, rising profitability and high returns with zero leverage
Opportunity size:
Identity Solutions: 1 Bn+ national ID cards delivered – taking the India model to emerging markets
International business: from ~1% of revenue in FY23 to 15.3% in Q1 FY27
Metal Cards: patented, Make-in-India premium cards – supplying all top-4 Indian issuers and exporting globally
Tax stamps: 30–35 Bn excise labels a year, ready to scale beyond India
RFID & IoT: item-level tagging for global retail majors, in a ~₹2.8 lakh cr global market by FY30
Steel Strips and Wheels
#SteelStrips#SSWL
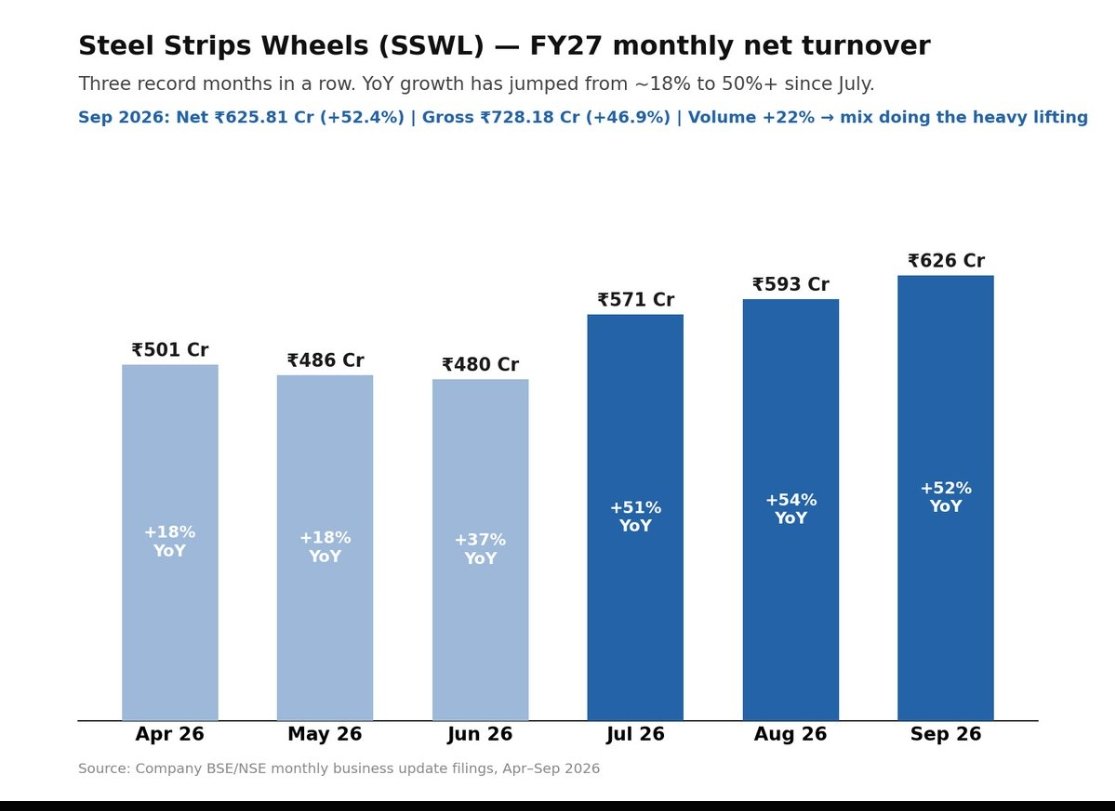
MoM momentum in #Q2FY27
Won't be surprised if SSWL posts 85-90cr PAT in Q2FY27 looking at last 3 months sales data
As margins are much better now with product mix in Q2FY27
Exports ⏫ 154% in Sept
Better margins here
July sales at 571cr⏫51%
Aug sales at 593cr⏫54%
Sept sales at 626cr⏫52%
22% volume growth
Elevate Campuses
#Elevate#ElevateCampuses
SBI MF increased stake to 7.18% vs 5%
Added 36.74 lakh shares which is 2.18%
Total 1.21cr shares held after latest addition
Good #Q2FY27 updates:
Good start to quarterly updates!for Q2FY27
Steel Strips and Wheels
SG Finserve
Lloyds Metal and Energy
TVS Motors
Tamilnad Mercantile Bank
Tata Motors CV
Force Motors
VST Tillers
Hero Motocorp
CSL Finance
Maruti Suzuki
HUDCO
Dhanlaxmi Bank
Karnataka Bank
JTL Defence
Ashok Leyland
Eicher motors
Decent:
Capital SFB
M&M
Hyundai Motors
Coal India
Bansal Wires
TMPV
APL Apollo Pipes
SML Mahindra
Canara Bank
Bad:
Escorts
Bajaj Auto-supply chain disruption
Pranav Construction
#Pranav#PranavConstruction
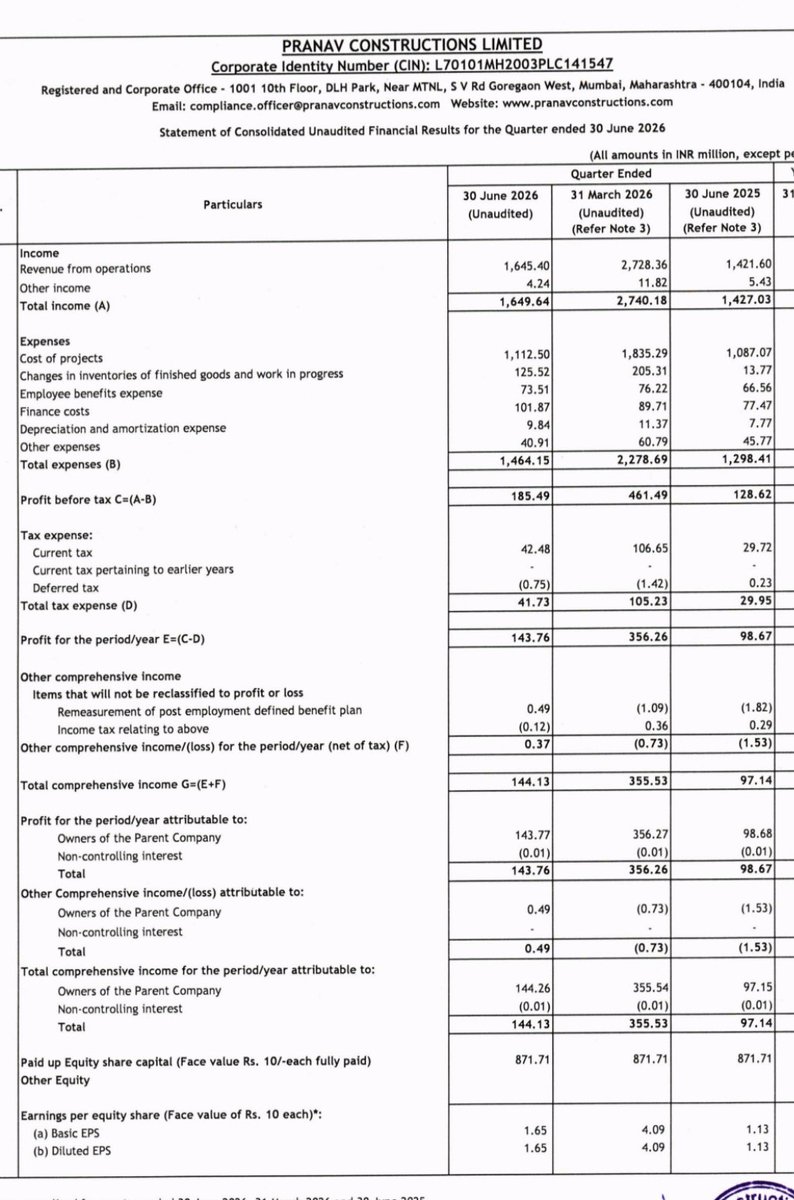
Good Q1FY27 with healthy YoY uptick and good margin expansion YoY
Company has good pipeline of ongoing projects which are scheduled to be delivered in next 24-30 months (waiting for PPT for more details)
QoQ can't be compared for real estate companies as they are lumpy in nature
Rev at 164cr vs 142cr⏫16%
EBITDA at 29cr vs 20.7cr⏫44%
PBT at 18.5cr vs 12.8cr⏫42%
PAT at 14.4cr vs 9.8cr⏫46%
Waiting for inv PPT for more details on:
Q1FY27 pre sales
FY27 pre sales trajectory if any
Pipeline of upcoming and ongoing projects and delivery schedule
Manipal Payment and Identity Solutions
#MPIManipal#ManipalPayment
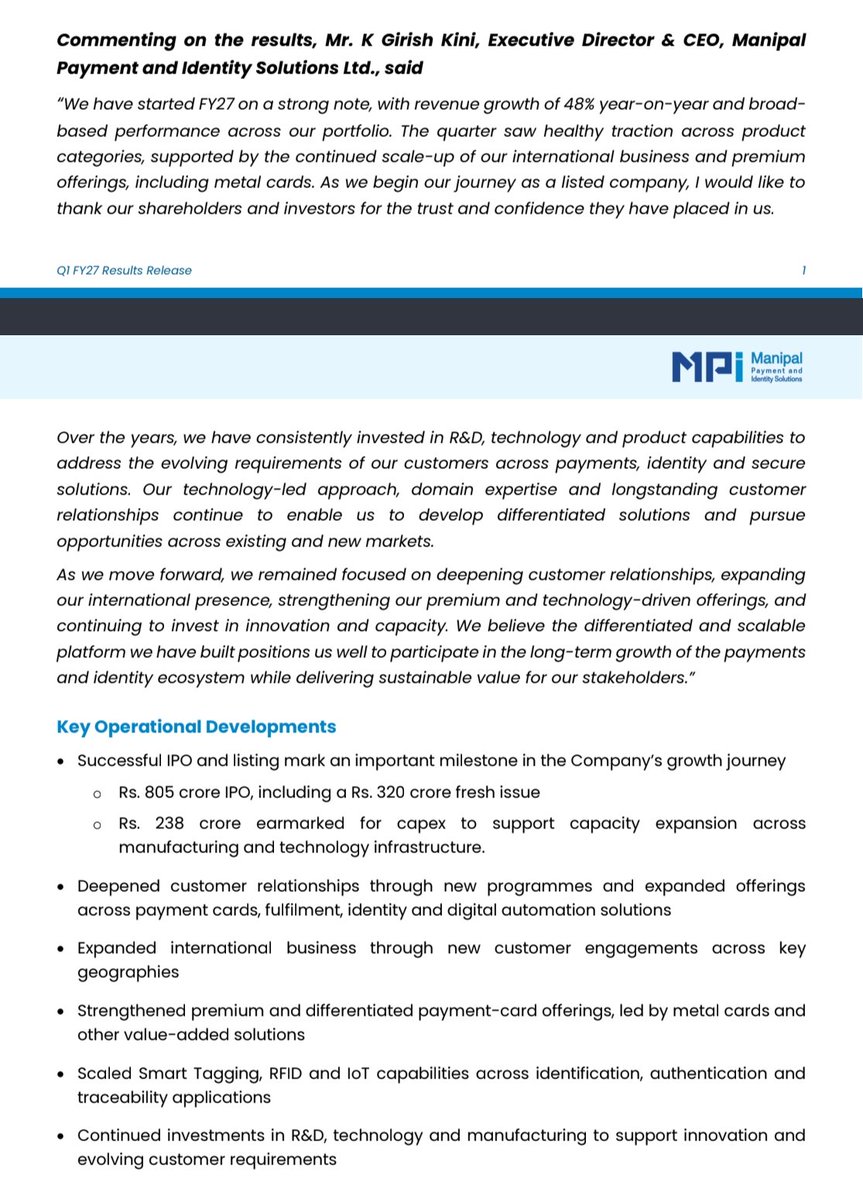
Press release:
Interesting developments wrt capex and exports uptick
Solid Q1FY27 with good QoQ and YoY uptick across all parameters
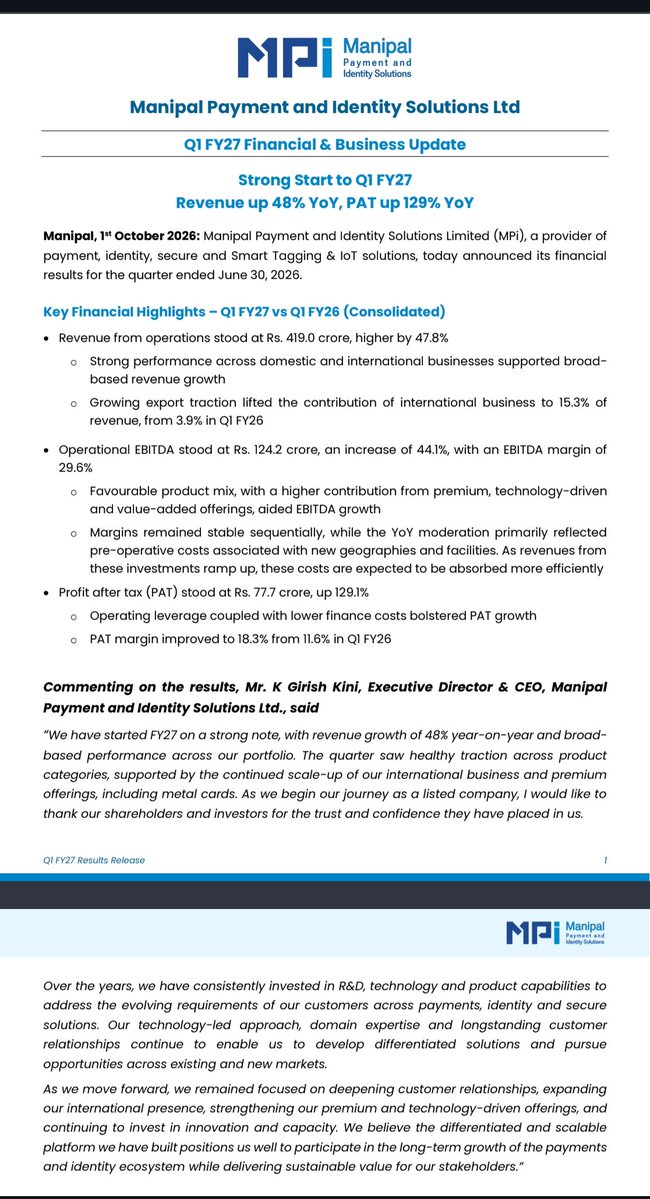
Rev⏫48% at 419cr
Strong performance across domestic and international
Growing exports traction
Exports stood at 15.3% of rev vs 3.9%
EBITDA at 124cr⏫44% with 30% OPM
Higher contribution from premium,tech driven and value added offerings
PAT at 78cr⏫129%
PAT margins at 18.3% vs 11.6%
Some upfront costs due to new geographical foray and infrastructure
Rev Will start reflecting from these going forward
238cr Capex
5-6x asset turns
Scaled smart tagging, RFID and ioT capabilities
#Q2FY27 updates:
V2 Retail and VMart are not exactly comparable YoY as Navratri falls after Q2 vs during Q2 for last year
This year Q3 should be very big due to Navratri and Deepavali both falling in Q3 which is anyways the best quarter for these companies
2/10/26:
Sambhv Steel Tubes
V2 Retail
VMart
Equitas SFB
Post 4pm
1/10/2026
Good:
Purple United Sales
Bharat Coking Coal
South Indian Bank
Atul Auto
Union Bank
Indian Bank
CSB Bank
Punjab and Sind Bank
ESAF SFB
UCO Bank
Decent:
Adani Ports
Knack Packaging
#KnackPackaging#Knack
Significant international order
150cr/annum
3 years
60 million bags per annum
Big capacity addition coming from FY28
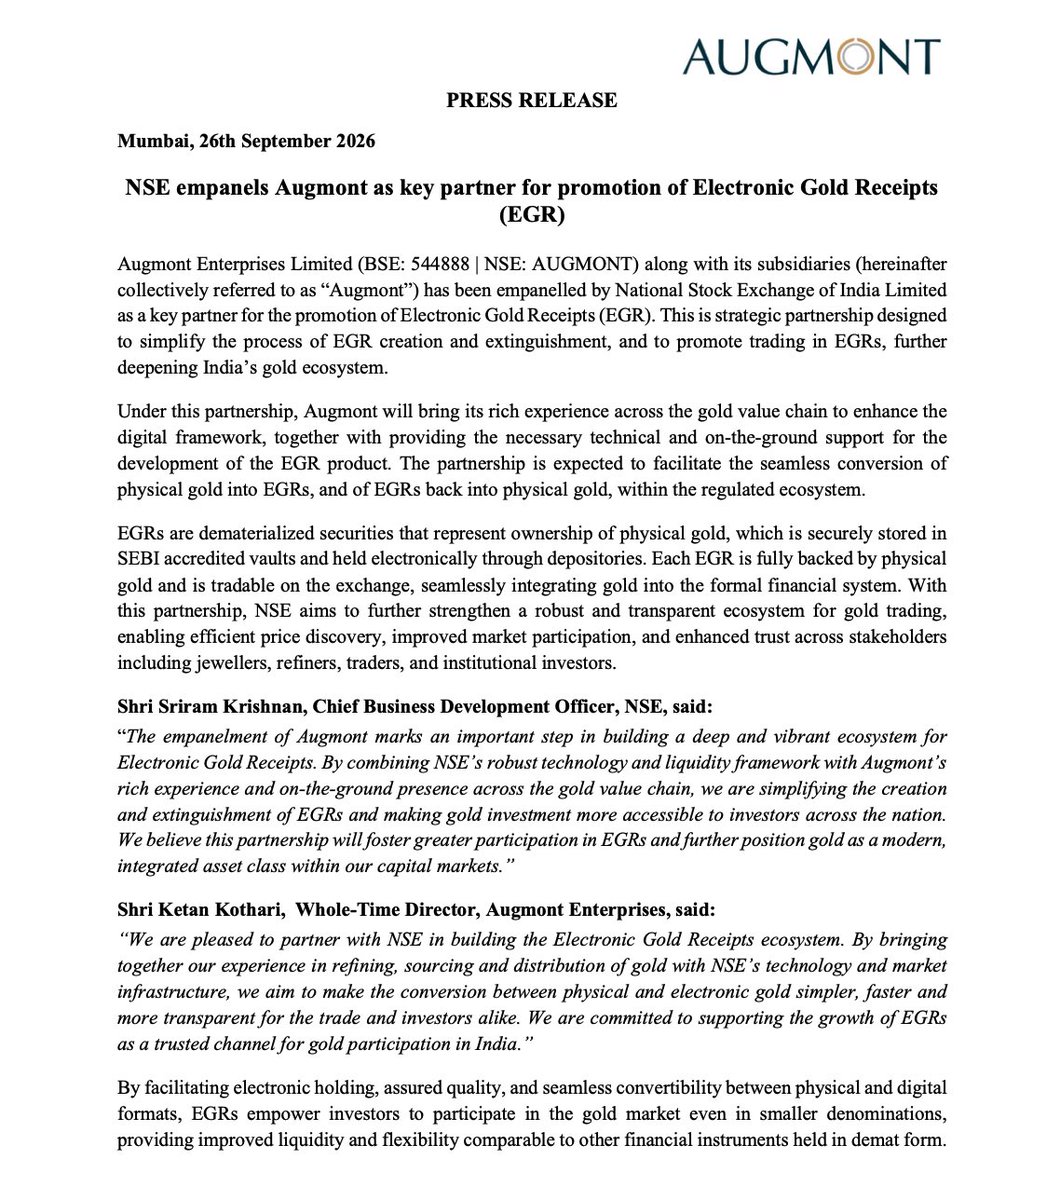
Update on Recently Listed Augmont Enterprises Ltd
The Company has been empanelled by NSE Ltd as a key partner for Promotion of Electronic Gold Receipts (EGR)
Augmont will help NSE convert physical gold into EGRs and vice a versa. They will provide technical & on-ground support for EGR Product Development
Seems like a Good Development
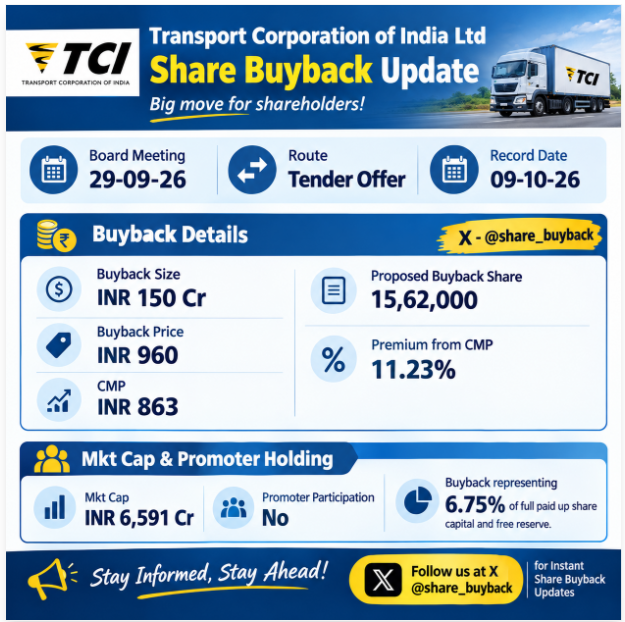
Transport Corporation of India Ltd : In today board meeting, the company announced the following terms and conditions of the share buyback.
Apart from share buyback, company approved setting up a wholly owned subsidiary in China with an investment commitment of up to $2 Million.
Follow us for tracking all updates related to Share buyback - https://t.co/i9wLIb5KlU
#buyback #sharebuyback #nifty #banknifty
Deepa Jewellers
#Deepa#DeepaJewellers
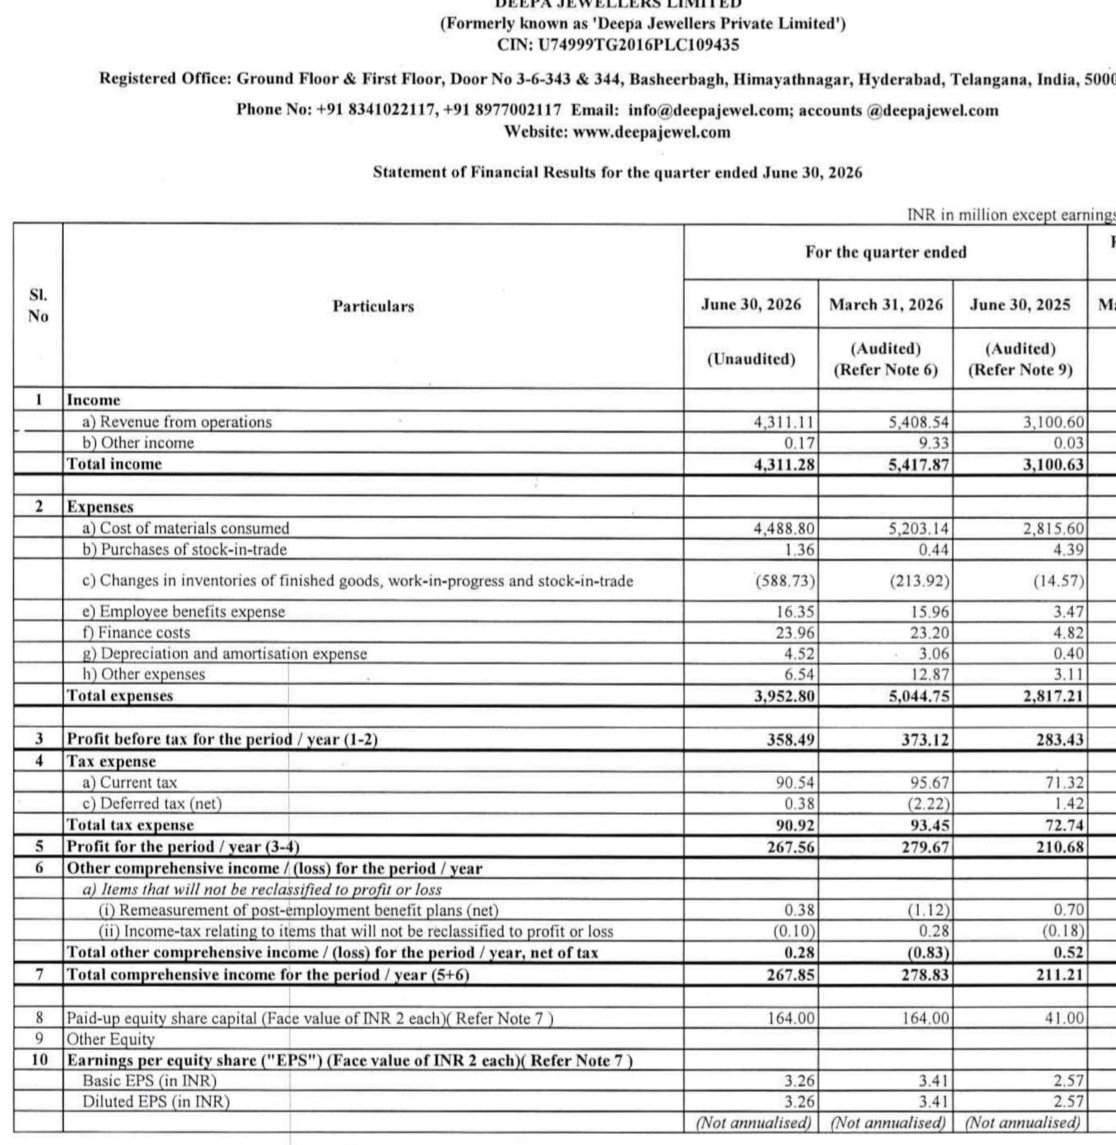
Decent Q1FY27 with 35%+ rev and EBITDA growth
Not comparable QoQ as it is heavily dependent on wedding season due to their products
Rev at 431cr vs 310cr⏫39%
EBITDA at 39cr⏫35%
PBT at 36cr vs 28cr
PAT at 26.7cr vs 21cr
Rays of Belief
#MomsBelief
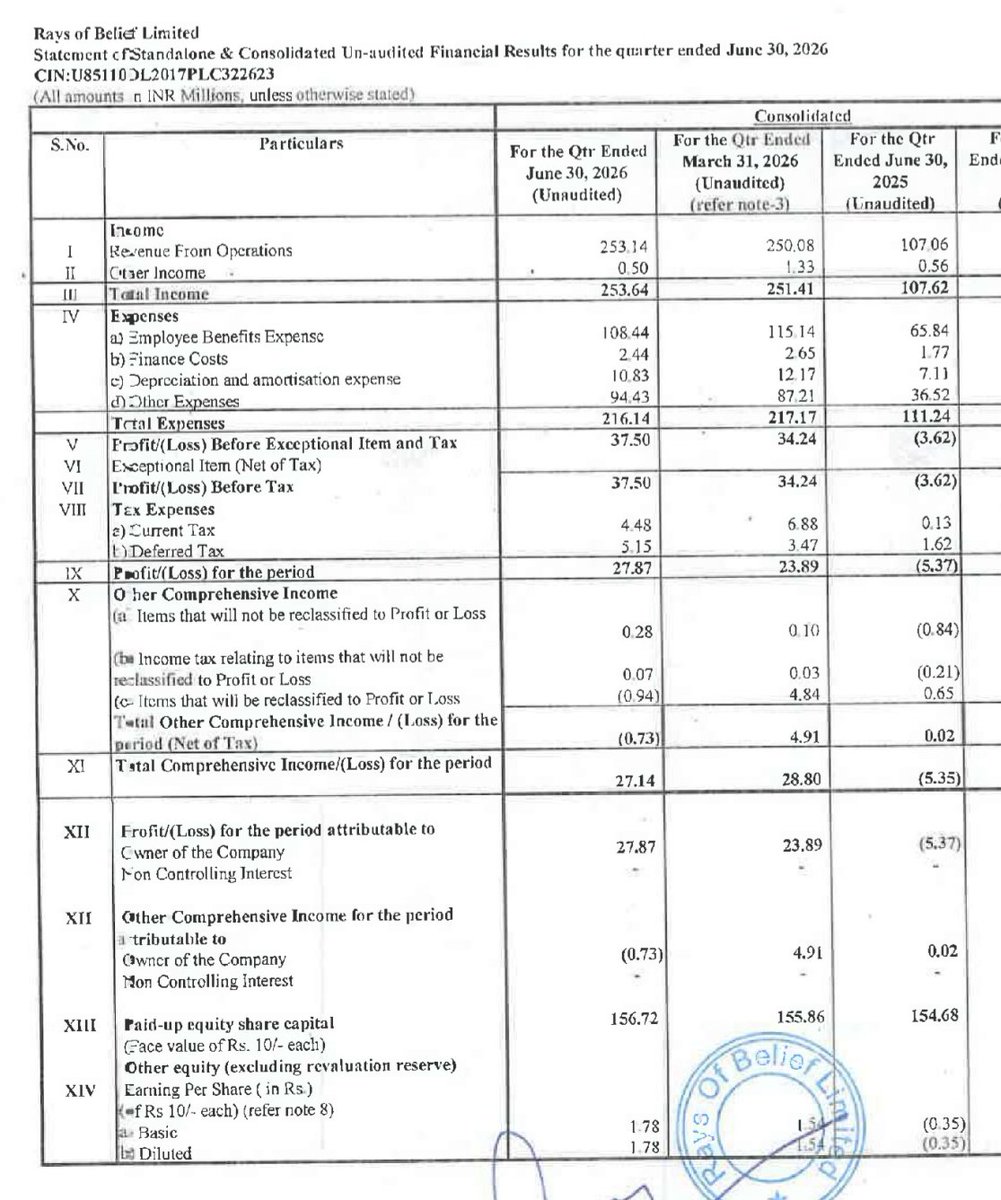
Good Q1FY27 with almost 10x EBITDA growth YoY with good margin expansion
Rev at 25cr vs 11cr
Q4 at 25cr
EBITDA at 5cr vs 0.5cr
Q4 at 4.8cr⏫6% QoQ
PBT at 3.8cr vs loss
Q4 at 3.4cr
PAT at 2.8cr vs -0.5cr
Q4 at 2.4cr
Prasol Chemicals
#PrasolChem#Prasol#PrasolChemicals
Blockbuster Q1FY27 with big margin expansion QoQ and YoY
Big QoQ and YoY uptick across all parameters
Concall at 11am tomorrow
Rev at 434cr vs 320cr
Q4 at 335cr
EBITDA at 92cr vs 42cr
Q4 at 34cr
PBT at 84cr vs 33cr
Q4 at 27cr
PAT at 61cr vs 24cr
Q4 at 20cr
Prasol Chemicals
#PrasolChem#Prasol
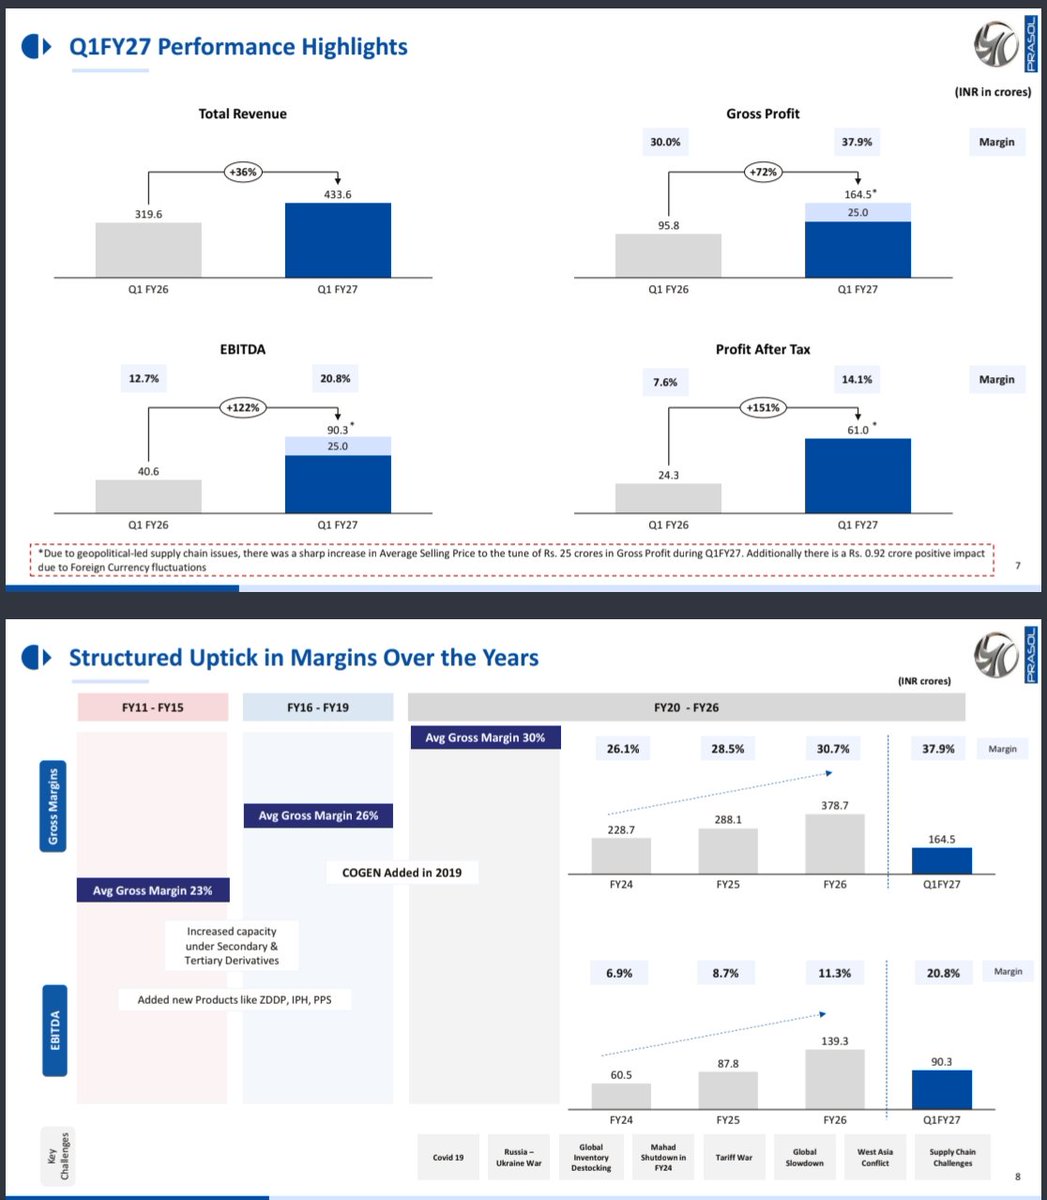
Inv PPT:
Record Q1FY27 on all fronts with big margin expansion QoQ and YoY
Strong guidance for FY27 with 75%+ EBITDA growth guided for FY27
Rev at 437cr⏫36%
EBITDA at 90cr⏫122%
OPM at 20.8%
PAT at 61cr⏫151%
Higher price realizations helped EBITDA by additional 25cr
Normalising and adjusting for realizations benefits, EBITDA would have been 65cr vs 40cr⏫62%
FY27 Guidance:
Rev growth of 34%+
EBITDA growth of 78%+ assuming no benefits of price increases
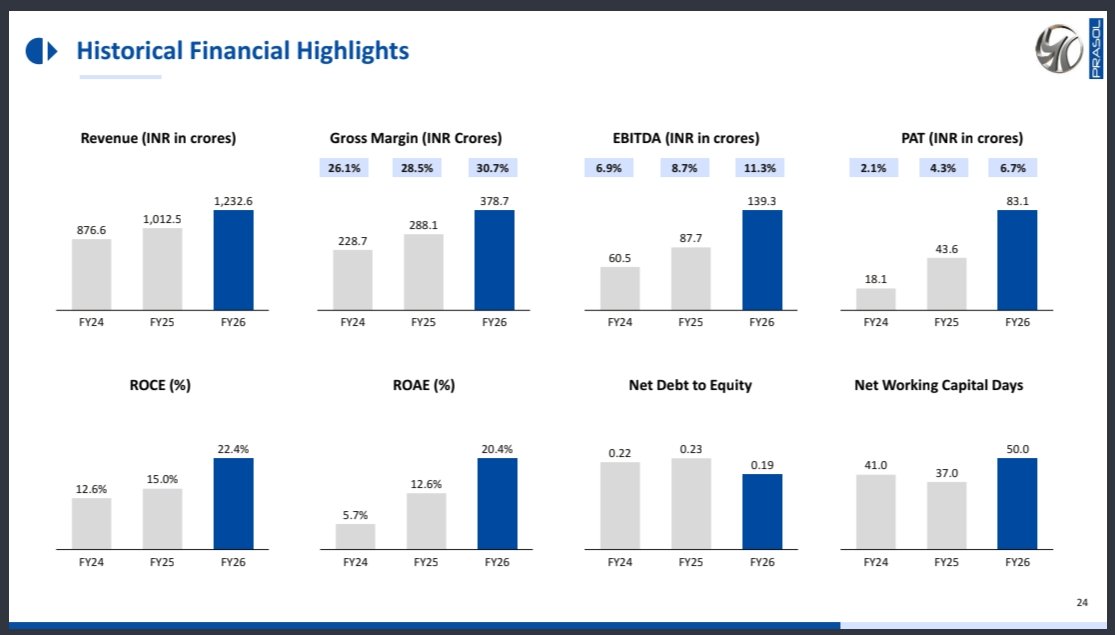
1550-1650cr rev vs 1233cr
240-250cr EBITDA for FY27 vs 140cr in FY26
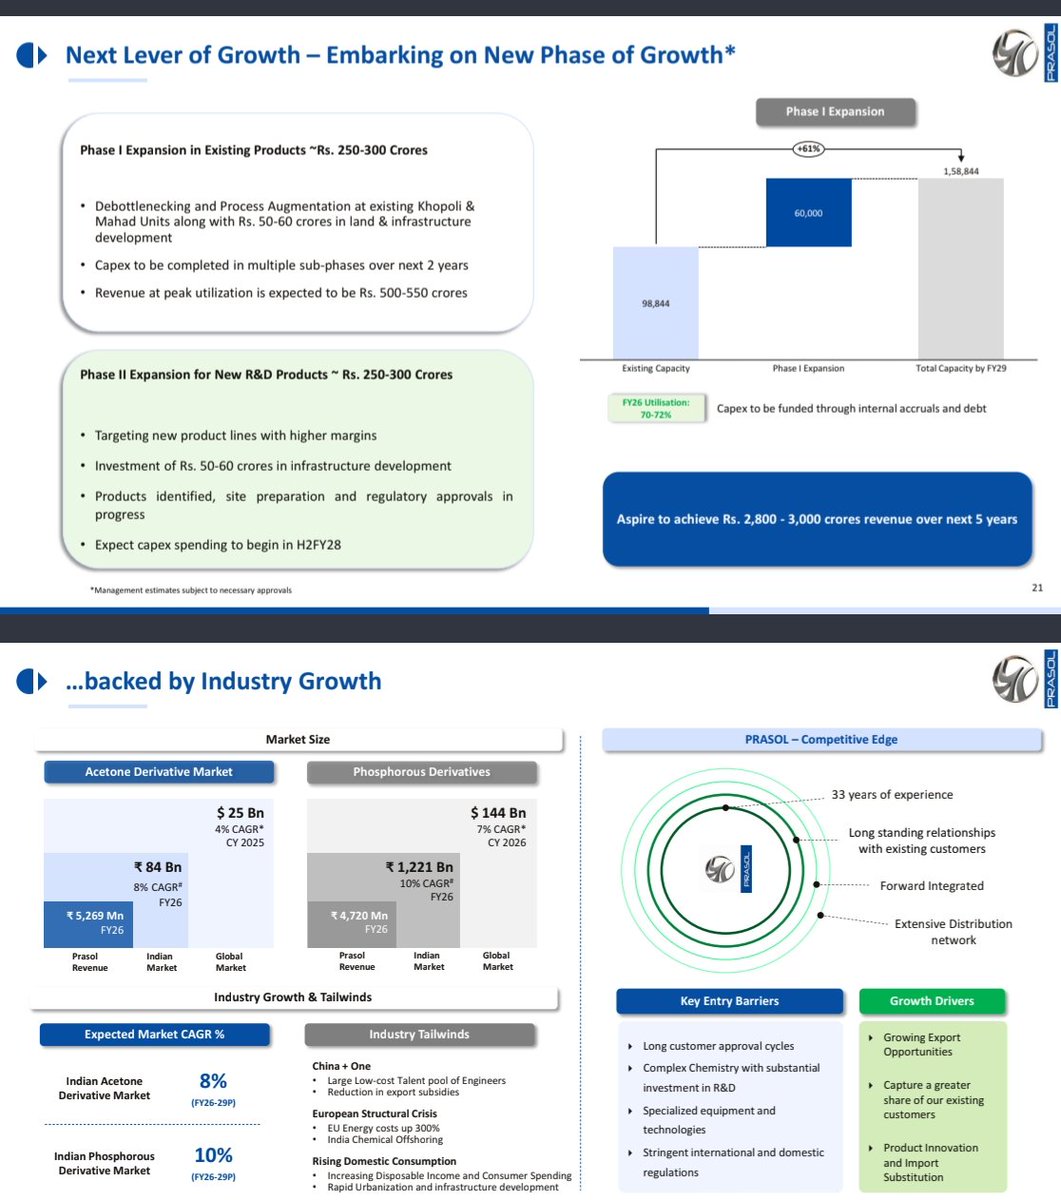
Targetting 2800-3000cr rev over next 5 years
Big margin expansion QoQ and YoY
Higher realizations
Good volume growth
Better product mix
Improved utilization at Mahad facility
Capex:
To come up in 2 phases
1st phase for exisiting products:
250-300cr capex
500-550cr peak revenue over next 2 years
2nd phase:
250-300cr for new products
Higher margins
H2FY28
Demand across acetone based and phosphorus based products remain healthy
Developing more than 40 new products at various stages
Mahad had best ever quarterly performance with improved utilization
Structural margin uptick for last 4 years and 20%+ OPM for Q1FY27
Prasol Chemicals
#Prasol#PrasolChem#Q1FY27 Concall highlights:
FY27 Guidance:
1550-1650cr revenue (35% growth)
240-250cr EBITDA (75%+ growth)
Debt is very small
Repaid 60cr from IPO proceeds
Which should reflect in H2FY27
Directly adds 4-5cr to bottomline
Capex in 2 phases
1st phase:
250-300cr
Existing products
550cr incremental revenue potential
2nd phase:
250-300cr
Speciality and high margin products
H2FY28
Aiming to do 2850-3000cr in next 4-5 years on topline
Capacity to move to 15800 MTPA vs 60,000 MTPA after both phases get commisioned
Exports 27% of rev
Some disruptions due to war
Domestic demand is holding up firm
D/E at 0.19x
Debt free after IPO
Strong internal accruals will take care of majority of capex funds
Wc days stable between 60-70 days
40 new products under various stages of development
Big potential in speciality pipeline of products
Import substitute
Demand for acetone derivatives are steady and strong
Holds 60-70% market share is select high margin products
Core margins to continue at 16-18%
20.7% Q1 margins due to 25cr increase due to price benefits
Guidance for FY27 assumes no inventory gains with normalized 16-18% OPM