The ECB artificially lowered spreads, and these countries have responded by borrowing more!
Where have we heard this before? Those saying that US interest expenses are over $1 trillion a year mean the Fed has to lower rates to relieve this stress.
Lowering rates will NOT, repeat NOT, relieve the interest expense burden. It will allow the Federal Government to borrow even more, as Europe did. And, like Europe, this lowering of rates makes the situation worse.
The only way to relieve the interest expense burden is to borrow less, not artificially manipulate interest rates lower.
Even if the economy and inflation are slow enough to warrant the Fed cutting, the consequence will be even more borrowing, and the subsequent uptick in interest rates will be all the worse.
The only way to fix the US debt interest expense problem is to elect politicians, both the President and Congress, who understand this issue and will work to resolve it.
Are any Hamilton and Jefferson 2.0s on the ballot capable of doing this?
7/8
If I'm right, regional banks, which collectively have about $6.8 trillion in banking assets, no longer understand their deposit base (bank's liability).
This will force them to pull back for expanding loans (bank assets), leading to a credit crunch as lending from the significant segment of the banking industry will pull back.
Restated, the Fed hiked too much, and deposit behavior, super-charged by mobile banking, broke.
Now Regional banks have to compete with market rates to hold deposits. This kills profitability which may explain why the bank stocks cannot really even as fears of failure subsides.
Banks are not cheap, as earnings expectations should be collapsing with net interest margins.
The gov’t has about 48 hours to fix a-soon-to-be-irreversible mistake. By allowing @SVB_Financial to fail without protecting all depositors, the world has woken up to what an uninsured deposit is — an unsecured illiquid claim on a failed bank. Absent @jpmorgan@citi or @BankofAmerica acquiring SVB before the open on Monday, a prospect I believe to be unlikely, or the gov’t guaranteeing all of SVB’s deposits, the giant sucking sound you will hear will be the withdrawal of substantially all uninsured deposits from all but the ‘systemically important banks’ (SIBs). These funds will be transferred to the SIBs, US Treasury (UST) money market funds and short-term UST. There is already pressure to transfer cash to short-term UST and UST money market accounts due to the substantially higher yields available on risk-free UST vs. bank deposits. These withdrawals will drain liquidity from community, regional and other banks and begin the destruction of these important institutions. The increased demand for short-term UST will drive short rates lower complicating the @federalreserve’s efforts to raise rates to slow the economy. Already thousands of the fastest growing, most innovative venture-backed companies in the U.S. will begin to fail to make payroll next week. Had the gov’t stepped in on Friday to guarantee SVB’s deposits (in exchange for penny warrants which would have wiped out the substantial majority of its equity value) this could have been avoided and SVB’s 40-year franchise value could have been preserved and transferred to a new owner in exchange for an equity injection. We would have been open to participating. This approach would have minimized the risk of any gov’t losses, and created the potential for substantial profits from the rescue. Instead, I think it is now unlikely any buyer will emerge to acquire the failed bank. The gov’t’s approach has guaranteed that more risk will be concentrated in the SIBs at the expense of other banks, which itself creates more systemic risk. For those who make the case that depositors be damned as it would create moral hazard to save them, consider the feasibility of a world where each depositor must do their own credit assessment of the bank they choose to bank with. I am a pretty sophisticated financial analyst and I find most banks to be a black box despite the 1,000s of pages of @SECGov filings available on each bank. SVB’s senior management made a basic mistake. They invested short-term deposits in longer-term, fixed-rate assets. Thereafter short-term rates went up and a bank run ensued. Senior management screwed up and they should lose their jobs. The @FDICgov and OCC also screwed up. It is their job to monitor our banking system for risk and SVB should have been high on their watch list with more than $200B of assets and $170B of deposits from business borrowers in effectively the same industry. The FDIC’s and OCC’s failure to do their jobs should not be allowed to cause the destruction of 1,000s of our nation’s highest potential and highest growth businesses (and the resulting losses of 10s of 1,000s of jobs for some of our most talented younger generation) while also permanently impairing our community and regional banks’ access to low-cost deposits. This administration is particularly opposed to concentrations of power. Ironically, its approach to SVB’s failure guarantees duopolistic banking risk concentration in a handful of SIBs. My back-of-the envelope review of SVB’s balance sheet suggests that even in a liquidation, depositors should eventually get back about 98% of their deposits, but eventually is too long when you have payroll to meet next week. So even without assigning any franchise value to SVB, the cost of a gov’t guarantee of SVB deposits would be minimal. On the other hand, the unintended consequences of the gov’t’s failure to guarantee SVB deposits are vast and profound and need to be considered and addressed before Monday. Otherwise, watch out below.
1/6
This chart showing the difference between what the Fed is suggesting they will do (red) and what the market is pricing (cyan).
It continues to be the story for 2023, especially going into tomorrow's CPI
🧵with thoughts
1/3
With Japan expanding the yield curve control band this week, we might be seeing the end of an era.
Negative interest rates are about to disappear.
As this chart shows, we are now down to less than $1 trillion of negative rates, the lowest since this measure began in 2015.
The Fed sees the jobless rate rising +90 basis points from the cycle low. This has marked a recession 100% of the time in the past. No sugar-coating where the economy is heading and Powell knows it.
#RosenbergResearch
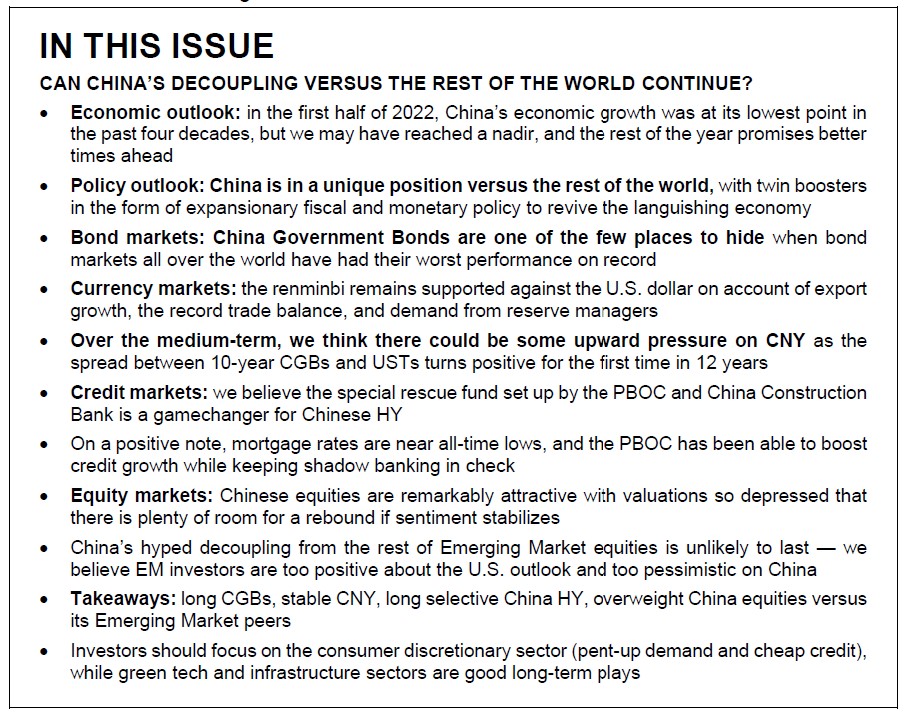
Special Report -- Our contrarian view is that China’s equity markets could outperform both Developed Market equities and its Emerging Market peers over the rest of the year (you heard it right, time to BUY China!).
Purchase the Report: https://t.co/WrGqq9yhjk
#RosenbergResearch
New ADP model showed a sharp slowing in job creation with contractions in the small business sector yet again as well as in the 2/3rds of the private sector that isn't leisure and trade
#RosenbergResearch
Macy's finance chief, Adrian Mitchell, on the consumer: “We're just taking a measured view on bad debts […] monitoring credit delinquencies […] monitoring payment rates […] we see that inflation is outpacing wage growth, that's just not sustainable for the consumer."
If households are stuffed with so much "excess savings" and with such strong balance sheets, why have they blown their brains out on credit card debt (at a 15% interest rate) these past four months -- a record $66 billion or +20% annualized!
#RosenbergResearch#Economy
My new oped for the Financial Times: The dangers for the eurozone are all too real. Italy is one focus of concern with its low potential growth, large deficits and enormous public debt
https://t.co/dnaqHBFeas
.@SecYellen on inflation being transitory: "I was wrong then about the path that inflation would take. As I mentioned, there have been unanticipated and large shocks to the economy [...] that I, at the time, didn't fully understand." https://t.co/AlrXn4kT0r
Shocking chart here from the legacy world.
Maybe market forces have done the Fed's job for it.
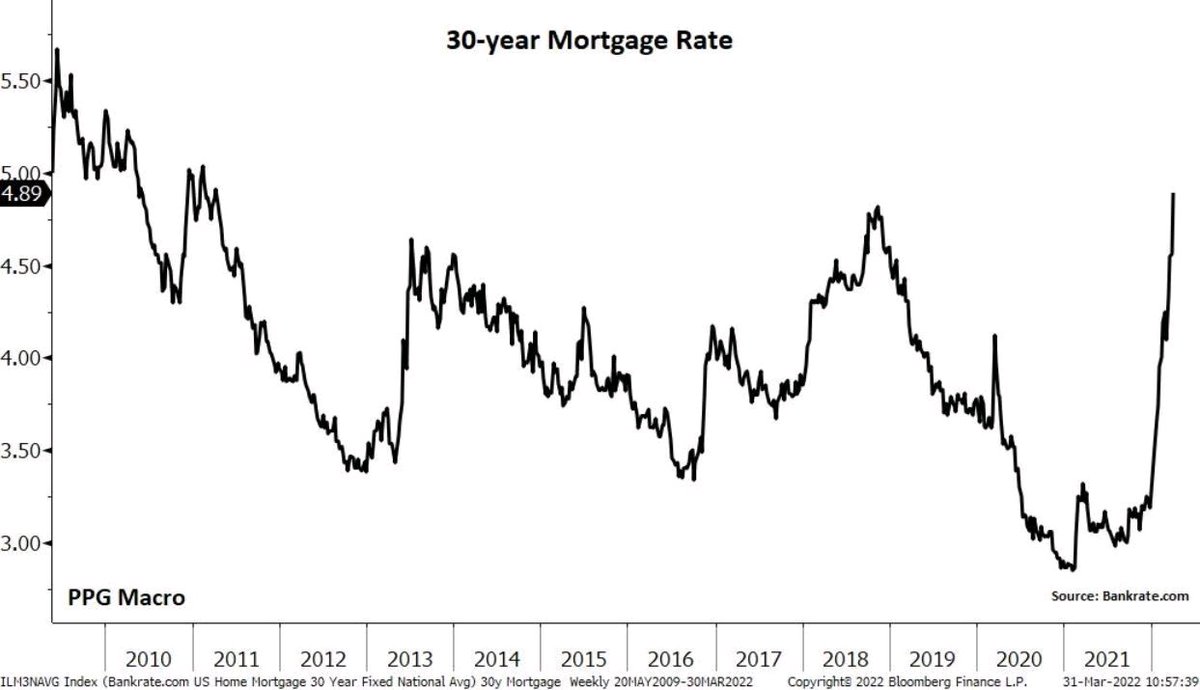
Almost no chance housing doesn't slow in future on severe credit tightness.
Legacy mkt gyrations not expected to negatively impact #Bitcoin or the digital asset ecosystem.
#HODL