@CryptoBankz_65 GQP took a big hit. Read up on them.. their share price listed in ASX has halved too. Same like anyone who went in hard earlier this year. 🥲🥲
https://t.co/0XEQF1vbsb
China simply doesn’t need to do anything to win AI
- US almost banned open weight.
- States preventing data center deployments
- Bernie and crew tried to jail people who accelerate AI development
- Jensen got kicked out, which could give Huawei the biggest kick ever
- and the stupidity continues
Why can’t you leave it alone and let USA win naturally?
All of the above are Chinese spies and must be investigated.
🚨 BOFA REMAINS BULLISH ON $NBIS!
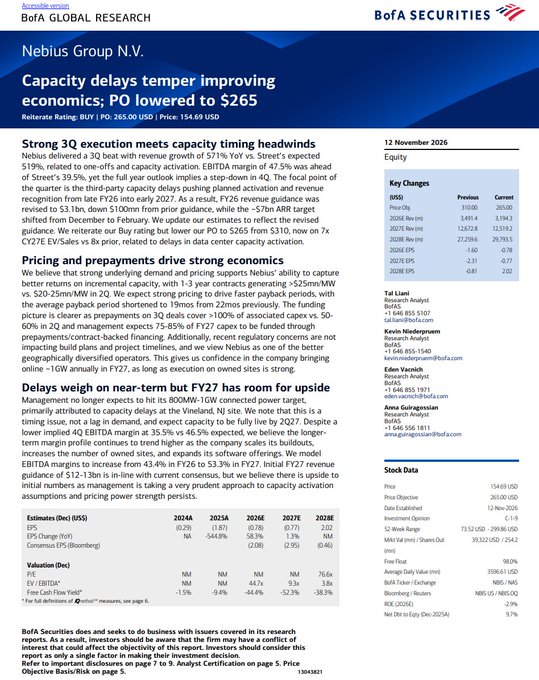
Bank of America reiterates its BUY rating on Nebius, despite lowering its price target from $310 to $265.
Here's what stands out from the November 12 research report:
🔥 Q3 adjusted EBITDA margin reached 47.5%, beating the 39.5% analyst expectation.
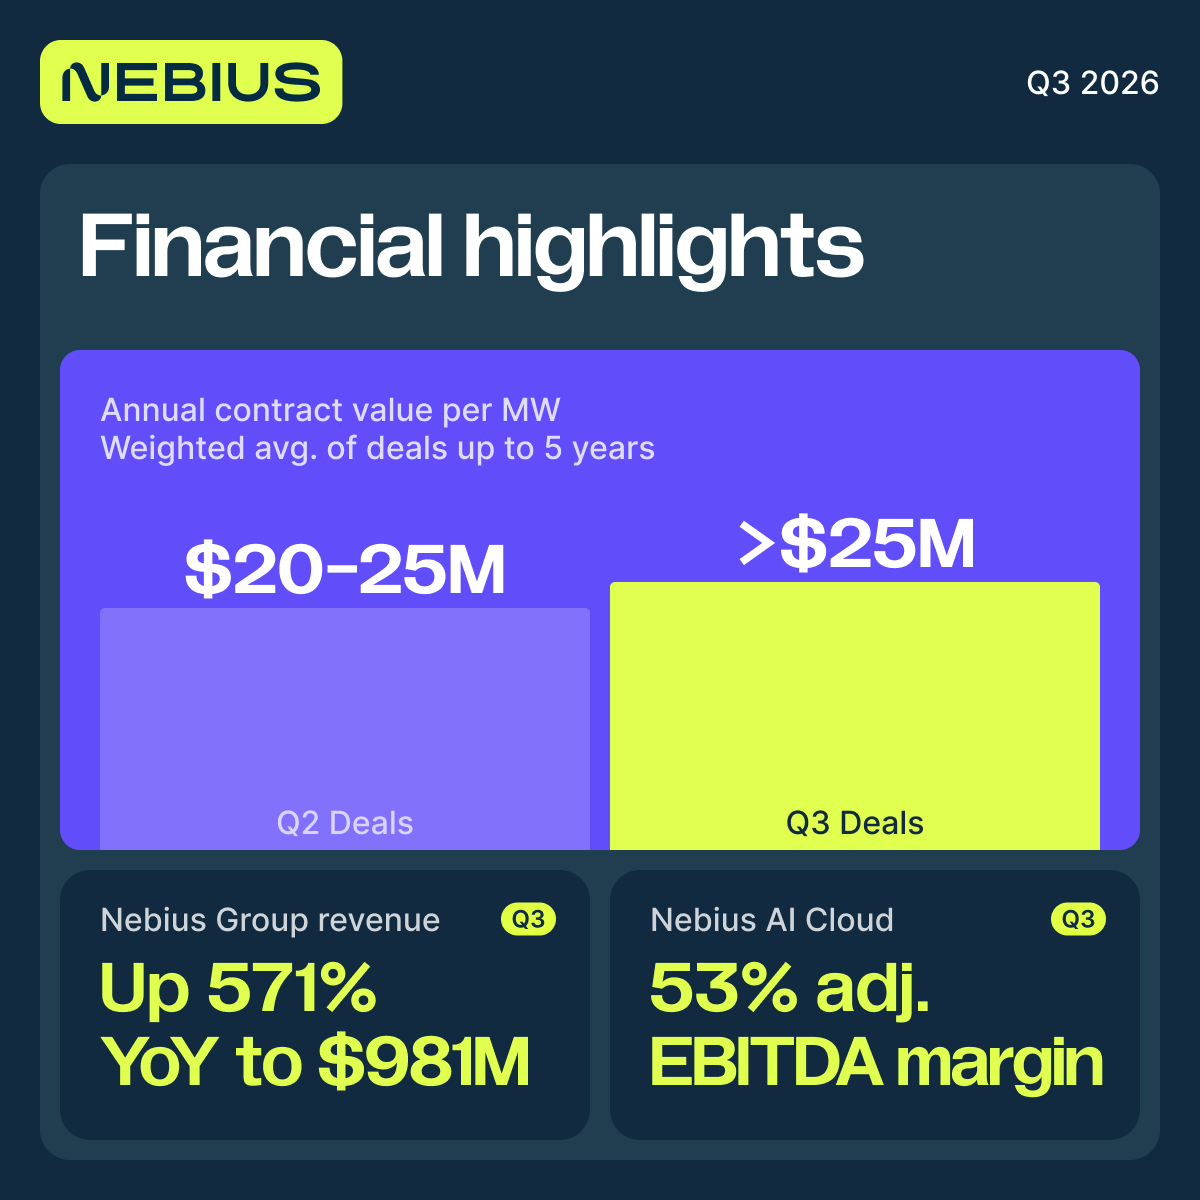
🔥 3-year contract pricing increased to over $25M per MW, up from $20–25M in Q2.
🔥 Customer prepayments on Q3 deals cover more than 100% of associated CapEx, compared with 50–60% in Q2.
🔥 Management expects 75% of FY2027 CapEx to be funded through prepayments and contract-backed financing.
🔥 The target of exceeding $7B in annualized run-rate revenue has shifted from December 2026 to February 2027.
BofA also maintains its view that Nebius could reach 1GW of connected power annually in FY2027, provided execution on owned sites remains strong.
Yes, capacity delays are a real challenge. But improving contract pricing, customer prepayments, and strong underlying demand are important positives.
The short-term execution risks are real, but BofA still sees substantial long-term potential in $NBIS. 🚀
NEW: In a tense late-summer meeting, Jensen Huang called his Chief Financial Officer Colette Kress a “deer in the headlights.���
His concern: Nvidia’s plans to fund the AI boom with its balance sheet were running into problems. He needed to figure it out.
He called her a “reporting CFO,” not someone who could help him define a strategy or make decisions.
With @RWhelanWSJ for @WSJ
https://t.co/V0gmpNYD2z
I’m seeing a lot of investors frustrated by the $NBIS earnings call. IMO, some of that comes down to a communication style that doesn’t always land with American investors.
Arkady is never going to be a hype CEO who excites and overpromises. Eastern Europeans in general tend to be more cautious and understated. That’s how a lot of us were raised. I don’t read this delivery as a lack of confidence.
If anything, I was more annoyed by the CFO and her VERY scripted answers.
But I understand, there are real reasons to be frustrated. NJ capacity is delayed, the $7B ARR milestone shifted from December to February, and 2026 capex went up. But customer prepayments on Q3 deals of at least a year exceeded 100% of the capex tied to those deals. That eases a lot of the financing concerns.
And Nebius now expects to reach pre-tax breakeven in Q4 2027. For a company building at this pace, I think that’s pretty incredible.
2027 will be a great year for NBIS.
BofA reiterated its Buy rating on $NBIS but lowered its PT from $310 to $265.
Still, looking at the changes to its estimates, you can see a massive improvement in EPS.
From a loss of $0.81 to a profit of $2.02 in 2028.
As I said, profitability was the highlight of the quarter.
🚨 $NBIS Earnings:
WE WERE VERY CONSERVATIVE ABOUT 2027 REVENUE GUIDANCE
WE TOOK VERY SIGNIFICANT ASSUMPTIONS AROUND POTENTIAL DELAYS IN THE PROVISION OF CAPACITY.
THE SAME GOES WITH ASSET LIGHT, WE DID NOT ADD ANY POTENTIAL REVENUE IN 2027.
“Our focus remains on building a healthy, profitable business for the long term. We will continue to invest across the business — in our capacity and infrastructure build-out, in our platform and products, and in the team that takes this to market.”
– Arkady Volozh, founder and CEO
Highlights from our Q3 results:
- Customers are paying more up front. Prepayments on Q3 agreements covered more than 100% of the related capex, including data center construction and networking, up from 50���60% in Q2.
- Pricing continues to rise. Annual contract value on Q3 deals topped $25 million per MW, up from more than $20 million in Q2, and GPU-hour prices rose on average by more than 20% from Q2.
- Our customer base is growing. We added more AI-native companies and signed our first agreements with leading enterprise data and AI platforms.
Regarding $NBIS earnings results:
To show you how fast they're growing... from Q2 to Q3:
Revenue: $582.3M -> $980.8M (+68% QoQ)
Adjusted EBITDA: $236.2M -> $465.8M (+97% QoQ)
AI cloud adj. EBITDA margin: 49.7% -> 53.2%
Net Income: −$190.4M -> −$37.5M
ARR has reached $6.4B at the end of Sep. In terms of management commentary:
- Since start of Q3, Nebius signed $12B+ of new contracts
- Average GPU pricing rose 20%+ sequentially, payback shortened from 22M -> 19M
- On Q3 deals, prepayments covered 100% of associated capex, up from 50–60% in Q2 (insane for financing)
- Contract value per MW exceeded $25M+ from Q3 up from ~$20M Q2
- 5GW contracted power year end
With $10B of committed customer prepayments in 2026 and $17B-$20B in 2027. Now, prepayments and borrowing against existing contracts covers ~75-85% of 2027 capex.
On subsidiaries:
1. Avride - 250 autonomous vehicles fleet, over 100,000 passenger rides (with companies like $UBER). Fully driverless robotaxi targeted H1 2027.
2. Toloka - Revenue doubled sequentially
3. Enterprise cloud - Databricks and Datadog selected Neibus. Along with a new agreement with Snowflake.
4. Tavily - Over 3M developers now with $IBM post-training a core partner.
5. ClickHouse - Nothing about new secondary valuations, but we can see valuations growing
6. TokenFactory - Contract value grew 17x sequentially
The primary negative I saw was that 2026 guidance is now on the lower end (near ~$3B), due to $MSFT capacity deliveries slipping to Q2 2027.
Apparently there was an execution miss with a third party partner DataOne. Temporary generators were retired amid permitting issues before enough $BE fuel cell capacity came online.
Capex also increased in 2026 from $20B-$25B to $27B, while revising revenue expectations downward.
So near-term unfortunate headwinds kinda reminiscent of AOI earnings; however long term I think Nebius will take care of you.
For 2027 outlook:
- $12-13 billion revenue, capex of $40-45 billion, pre-tax breakeven by the end of 2027.
Very operationally bullish, as seen with prepayments covering capex, GPU premiums increasing. Main downside is near-term execution risk from third parties, causing near-term delays and revenue recognition.
Great quarter from Nebius overall.
Q3 results and the shareholders' letter are out!
https://t.co/hefWOBYuMp
In short:
- 12B in new contracts with prepayments covering capex.
- Token Factory turned into revenue with hundreds of millions in ARR
- Trust from the best enterprise ISVs: DataBricks, Snowflake, Datadog.
Just started and to remind why we are here:
The market is often described as two separate categories: infrastructure providers that supply compute, and software platforms that turn models into production systems. That is a false choice for customers. Customers need both: a reliable, scalable compute foundation and the software and managed services - all engineered as one platform.
We are building that platform: full-stack AI cloud for the entire lifecycle of compute-intensive AI, from training and post-training to inference, search and agentic execution. We continue to deliver excellence at scale across our core products, while introducing new capabilities that benefit from end-to-end integration across the stack.
FULL INTERVIEW: Nebius ($NBIS) Chief Technology Officer on Nebius not being a neocloud, how data centres in space make no sense, and why great engineers have less time than ever.
1:02 Nebius is NOT a neocloud
6:18 Everything is in demand, everything is scarce
9:49 Data centres in space make no sense
12:07 There's plenty of room for data centres on earth
14:37 30MW was huge, now not enough for one client
15:36 Nebius clients burn 900GB per second
17:24 Just 100 people in the world could work for Nebius
21:09 Enthusiasts v. Engineers
26:22 Great engineers have LESS time than ever
Oil freight costs are falling fast, with multiple routes West of Suez down 50%-75% over the last few days.
Rates are holding better for tankers originating **inside** the Persian Gulf. But the key route from Gulf of Oman to northeast Asia is down ~60% since Oct 15. Crisis over?
You guys don’t understand how evil and malicious Anthropic really is
Their witch hunt against Jensen is just another chapter in the long book of a very misaligned company
Necessary read to fight back against this malicious corporation
My Experience With the Leaders of the Jensen Coup
At the start of 2025, numerous Washington, D.C. based NGOs began spreading the false rumor that DeepSeek smuggled 50,000 H100 GPUs. Speaking from firsthand experience, organized think tanks, PR firms, and lobbyists aggressively personally attacked anyone merely asking them to provide evidence. Call them the Export Controls Deep State, or if that’s too right-coded for you, use the Obama-administration term “Foreign Policy Blob”.
The same charlatans are attempting a coup on Jensen Huang, the most indispensable CEO to America’s AI success. If we lost Sam, we have Dario. If we lost Dario, we have Demis. Nvidia is singular. The gap between Nvidia and AMD would be wider than the gap between OpenAI and Mistral, Europe’s top AI company whose models don’t rank in the top 40. This is an attempt to derail the most important company for the American AI industry.
The entire coup against Jensen Huang can be halted by asking a single question. What evidence is there that Alice Huang is actually a Chinese spy? The answer, unsurprisingly, is absolutely zero. There is not even the pretense of a factual basis for the claim. “We made it the fuck up, and if you have a problem with that, what are you, pro-China?”
Taking away this obvious falsehood, the coup against Jensen boils down to a celebrity tabloid headline. Moreover, without the entirely fabricated ‘national security relevance’, these tabloid headlines would be at best a weekend story in the New York Post. Another basic question: if there is evidence of ‘national security relevance’, why not charge Jensen? The basic answer: they lack even the evidence to justify a warrant.
During my time in DC, I was advised repeatedly to stay on the good side of the Export Controls Deep State. I was added to many groups for boosting content spreading the 50,000 H100s conspiracy theory. In several groups, I asked whether there was any evidence behind this claim. One group administrator, who was and still is affiliated with Georgetown, explicitly told me to “focus on bolstering the narrative”. I later posted Patel’s pseudo-correction and was subsequently removed from all of these groups.
What you need to understand about the Export Controls Deep State is that they have no incentive to be remotely honest, because they are entirely unaccountable. To this day, they provided zero evidence for their claim. Internet historians later traced the origin of this claim to a tweet by Dylan Patel of Semianalysis. Patel later said they lied about his tweet and that his claim counted legally obtained hardware.
Affiliates of universities and think tanks promote these baseless claims and are taken seriously by the national press. In reality, their theories about Nvidia are as kooky as the guy who shot up Comet Pizza. The reason they succeed is not only because they are unaccountable, but because they constantly use their unaccountability to attack others. There are broader foreign policy implications to these observations about political power, but I will stick to what I witnessed firsthand.
After Trump’s election, his administration began lifting the export control cap. Surprising no one informed about this policy, America widened our lead. Deepseek was closest to catching up to American models in January 2025, literally the moment of peak export controls.
Based on communication with members of the administration, the evidence that a) the export controls were net negative and b) the export controls deep state was acting in bad faith, that as soon as the situation was described accurately, the administration began rolling them back.
Part of this is because many of these NGOs are funded by foundations like Open Philanthropy / Coefficient Giving, who explicitly intend to harm American AI companies because they believe American AI will “cause human extinction”. As a result, the BIS under the Biden administration was used as an informal cudgel against AI companies, both to censor in favor of their worldview, as seen in the Gemini scandal, as well as to backdoor regulation to slow down American AI broadly.
While they love to accuse everyone else of being traitors, the Export Controls Deep State makes Americans poorer and the American military, to the extent they use AI, weaker.
Most of the time, the best you can do is ignore them. They really are unaccountable and the personal retribution isn’t worth the cost. But now, they are leading a coup against the AI industry’s most indispensable man based on lies and tabloid gossip. Everyone should understand that the Export Controls Deep State has never provided any evidence for their claims nor any reason for their word to be trusted.