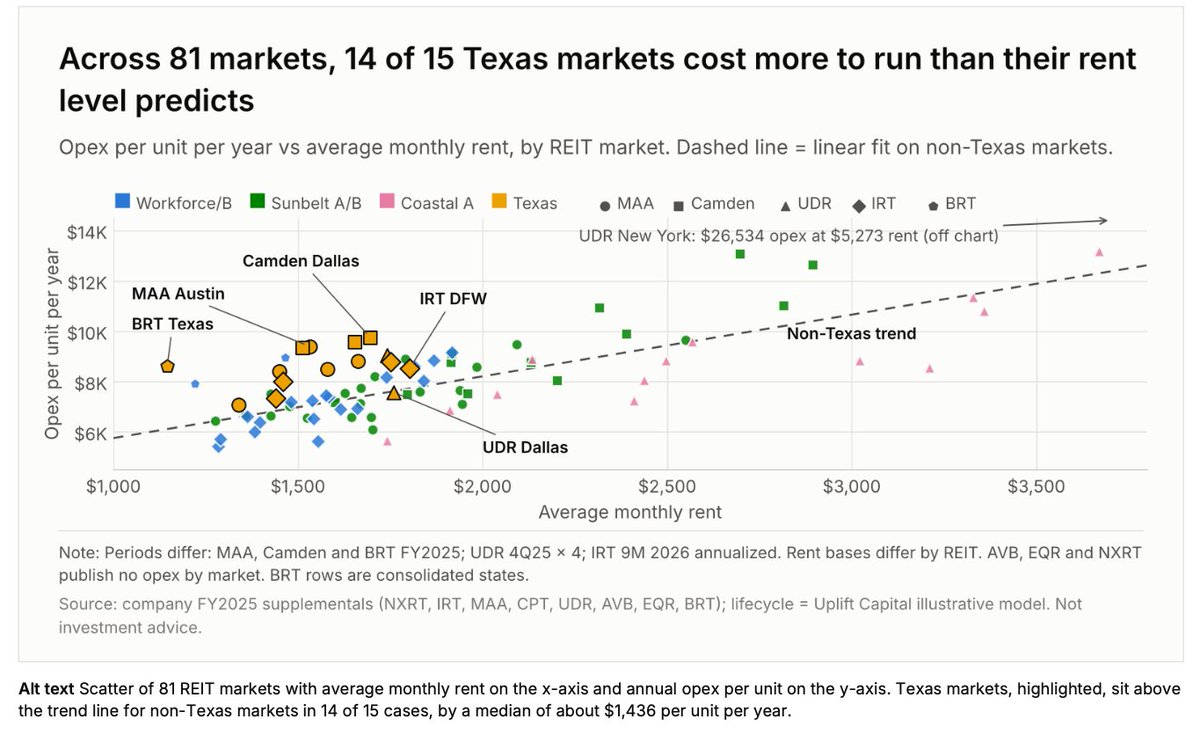
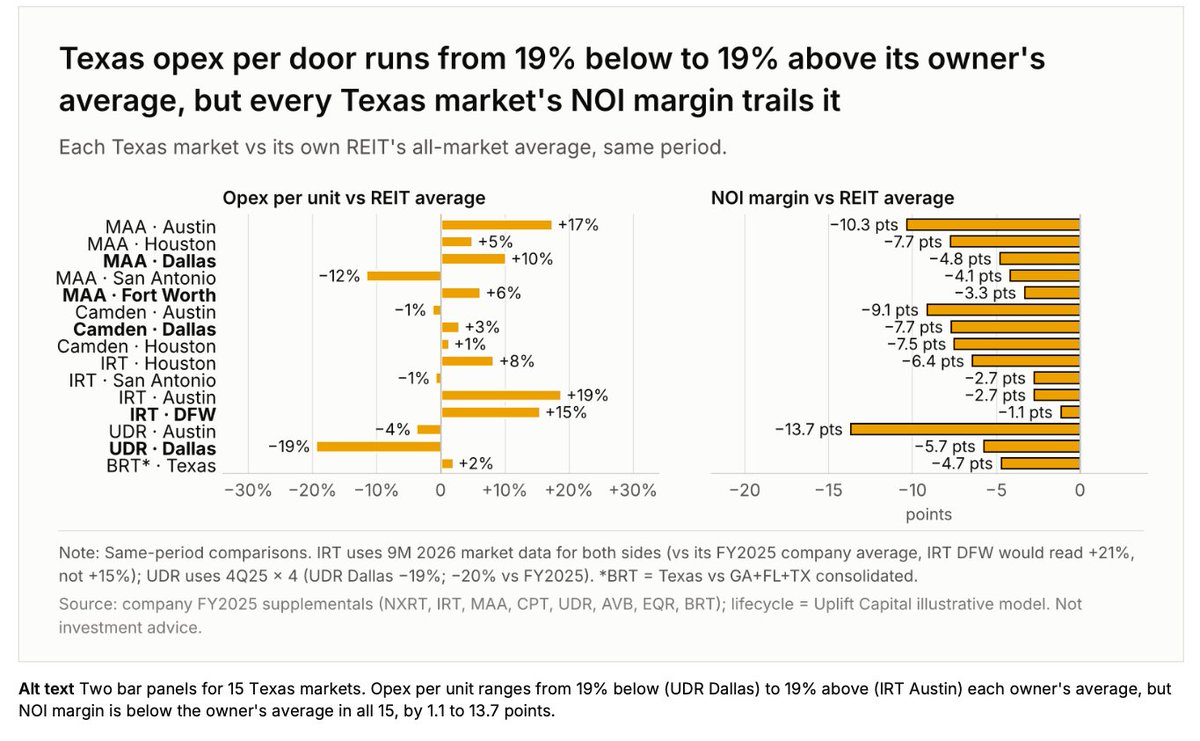
If returns now have to come from price and how you run the building, every renovation dollar needs a clean trail. Code each invoice once and keep every lien waiver tied to its invoice, so the lender sees where the money went.
https://t.co/2k6mNJVZWE
"From 1776 to 2027: Adam Smith, Sam Zell and the Economics of Buying at the Bottom."
I’m knee-deep in writing up our vision for buying in today’s market and the above is the provisional name. The Fed cut in every prior workout cycle. This time it went back to raising before the maturities peaked.
Every prior commercial real estate distress cycle was resolved by an economic event. Time and then a war economy ended the 1930s decline, rate cuts and inflation carried the 1973 to 1980 cycle, a federal liquidator forced loss recognition through sales from 1989 to 1995, and in 2008 and 2020 the Fed cut rates to zero and inflated asset prices.
This cycle has run four years, and plowed through the cutting cycle that should have ended it. Why? Because lenders have learned that waiting pays off and liquidity remained high.
Then, on September 16, 2026, the Fed raised rates for the first time since July 2023.
In 2027, ten-year loans from 2017, five-year loans from 2022, and the 2016 and 2021 extended loans mature with the 10-year T-Bill near 5%. Private credit is facing redemptions and warehouse paydowns of their own. Those funds may become forced sellers like the mortgage REITs of 1974.
Without a rescuer, value moves to what Adam Smith, in 1776, called the natural price. This is Sam Zell's replacement cost plus the cost to modernize it. Buy below that cost, as Zell did in 1974, and you'll undercut new construction and still make money. When the cost to replace can’t earn a market return, nobody builds.
The theory holds only if tenants rent covers the building needs. Where, for example, multifamily rent exceeds a third of renter income, you cant expect rent growth towards a natural price.
Zell’s 1974 trade had three parts. He paid half of replacement cost, he bought from banks that needed a five-year recovery more than cash, and the Fed cut rates 62% during his hold. In 2027 we will seemingly not get a rate cut, so returns must be tied to price and the way you run the building.
Here's a great statistic. From 1982 to 2024 cumulative value growth ran about four times cumulative income growth, but for the year through June 2026, 94% of the NCREIF return came from property income, and only 6% from appreciation.
So, without the engine of inflation, appreciation comes from intense management and intelligent acquisition rather than the benefit of time. So, is it time to buy?
As Walter Deemer put it in 2019, when the time comes to buy, you won’t want to.
Does the draw mean keying every invoice a second time? No. Code it once. Relay pulls the bills your team already coded into the draw package, so nobody keys them twice.
See it on your own draws. Book a demo at https://t.co/rJYTKqpfWj: https://t.co/nq8FhpEsW7
Soft costs like these pile up before anyone breaks ground, and every one still has to show up in a draw. Code each invoice once, with no double entry, and the lender can trace every dollar from the permit fee to the framing.
https://t.co/JI2FlLdIHA
When politicians talk about removing the red tape for developers and homebuilders, I am reminded of a few requirements I have seen lately on a single deal I underwrote:
1. $50,000 in permits
2. $15,000 park fee paid to the city
3. $140,000 line of credit to the city for required landscaping improvements (trees and irrigation)
4. $35,000 line of credit to the city for storm water management, erosion control, and site restoration
Sometimes the better seat is the lender's. What that seat still needs from the borrower is a clean trail each month: every invoice coded once and every lien waiver tied to its invoice.
https://t.co/MSq0hq4GvU
Equity investors get paid for what goes right. Lenders are structured to get paid even when things don't go exactly as planned.
The longer I spend in residential real estate investing, the more I am realizing that sometimes, I would rather be the lender than the equity investor.
Let's use a real world example: a developer comes to me looking for $500,000 to build a single family home.
Option A: invest the equity. The developer targets a 25% return over 12 months. As an investor, you are exposed to construction overruns, permitting delays, a slower than expected sale, and the possibility of generating no profit at all.
Option B: finance the debt. You provide a $400,000 senior secured construction loan at 12% and charge 2% origination. Assuming the builder uses the full note and draws down on a reasonable schedule, you are likely to collected $60,000 in interest and fees. You are secured by the underlying real estate, a personal guaranty, and have priority over the equity. You are not relying on the developer to get his underwritten exit price to generate a return.
Lending is not-risk free. A bad loan can still result in a loss and foreclosure is neither quick or inexpensive. However, sometimes the better investment is financing the person taking the development risk.
When permit-to-start slippage runs this high, the deals that do break ground have less room for messy draws. Nobody picks the lender's portal, but every owner picks what goes into it: each invoice coded once and each lien waiver tied to its invoice.
https://t.co/Aq8EUYqGp9
For a submarket DFW and North Texas example:
Celina/Prosper and Sherman are looking at permit-to-start slippage around 50%
Mckinney/Allen is looking at 38%
Frisco/Plano is around 18%
A completion guaranty gets the loan closed. After that, every dollar still moves draw by draw. Code each invoice once, keep every lien waiver tied to it, and the lender gets a clean package each month.
https://t.co/P0fvIAFj4g
Construction loan. Plans, permits and GC bid all in hand.
Lender wanted a completion guaranty from someone with real net worth.
Borrower's LLC had none.
He brought in his brother in law. Awkward family dinner.
Who's your guarantor?
Fall maintenance wraps up in early November, and the invoices follow. Relay reads each one as it lands, matches it to the property and budget line, flags duplicates, and builds the package.
See it on your own draws. Book a demo at https://t.co/rJYTKqpfWj: https://t.co/PEcgQE5RmU
Sellers can sell "tailwinds." Buyers still need a trail. Once the deal closes, every renovation invoice coded once and every lien waiver tied to it is what the lender sees on each draw.
https://t.co/gTKQcOZl02
Refinance deadlines keep coming for apartments built under cheaper debt. When the next lender asks for the trail, clean records help: every invoice coded once and every lien waiver tied to its invoice.
https://t.co/Ia6zjQuQjs
Good morning.
The WSJ on a risk that industry insiders I follow worry could spread as more debt refinancing deadlines hit:
“Brookfield is exiting the property rather than refinance the building’s roughly $360 million loan, which would have required tens of millions in additional costs because of today’s high rates, according to people familiar with the matter. The lender, Apollo-owned Bridge Investment Group, is now working to sell the loan.
Its cost of debt has effectively wiped out the firm’s equity in the property, giving it little reason to hold on, according to real-estate brokers.”
#economy #markets #RealEstate #debt @WSJ
When starts keep falling, the deals that do fund have less room for messy draws. Nobody picks the lender's portal, but every developer picks what goes into it: each invoice coded once and each lien waiver tied to its invoice.
https://t.co/OFJeWbbyea
Apartment construction starts are already down 50% from peak, and I'm increasingly of the view that they'll decline further here in Q4 and into 2027.
Just a brutal environment for apartment developers these days with high interest rates, frozen equity capital and some construction cost increases -- outweighing improved occupancy/rent trends in most cases.
No one is immune to math.
If you are relying on Census building permits for multifamily construction trends, you are blissfully unaware of realities on the ground.
Budget season is full. Relay matches invoices to the budget line and builds the draw package. 4+ hrs saved per draw (https://t.co/rJYTKqpfWj).
See it on your own draws: https://t.co/QVFaQRQqxO
If deliveries stay this low through 2030, the projects that do break ground matter more. Nobody picks the lender's portal, but every owner picks what goes into it: each invoice coded once and each lien waiver tied to its invoice. https://t.co/cc7bBwG4zk
One of the biggest opportunities in REITs today is the coming recovery in apartment rents. Years of oversupply hurt landlords like Camden ($CPT), but new construction has now collapsed. With deliveries expected to remain depressed through 2030, landlords could soon regain significant pricing power.
"How do I get paid back?" is the lender's question on every renovation bridge loan. The owner's best answer is a clean record: every invoice coded once, every lien waiver tied to its invoice, and each dollar of the renovation budget easy to trace. https://t.co/LPwVy0FpsQ
Dividend suspensions always get my ears perked up. Happy halloween to all - we don't get trick-or-treaters at the farm, so I wrote this up instead. https://t.co/GLMCFJNMSO
When land has outrun build costs this much, smaller projects have little room left. The tools that run the draws shouldn't eat into it: no per-project pricing, every invoice coded once, and a free test draw to see if it fits. https://t.co/tZVEMEiojv
Shift in U.S. homebuilders' costs since 2012, according to AEI Housing Center indices
+286% -> Residential land
+157% -> Home prices
+68% -> Rents
+52% -> Construction costs
+49% -> Construction wages
Funding the reserve account is the easy part. Running it is the work. Relay tracks each community as its own workflow and flags the one below threshold before the next draw is due.
See it on your own draws. Book a demo at https://t.co/rJYTKqpfWj: https://t.co/AByieeQHSz
A construction loan this size funds draw by draw, all the way to delivery. Nobody picks the lender's portal, but you do pick what goes into it: every invoice coded once and every lien waiver tied to its invoice. https://t.co/FNyVbydVl1
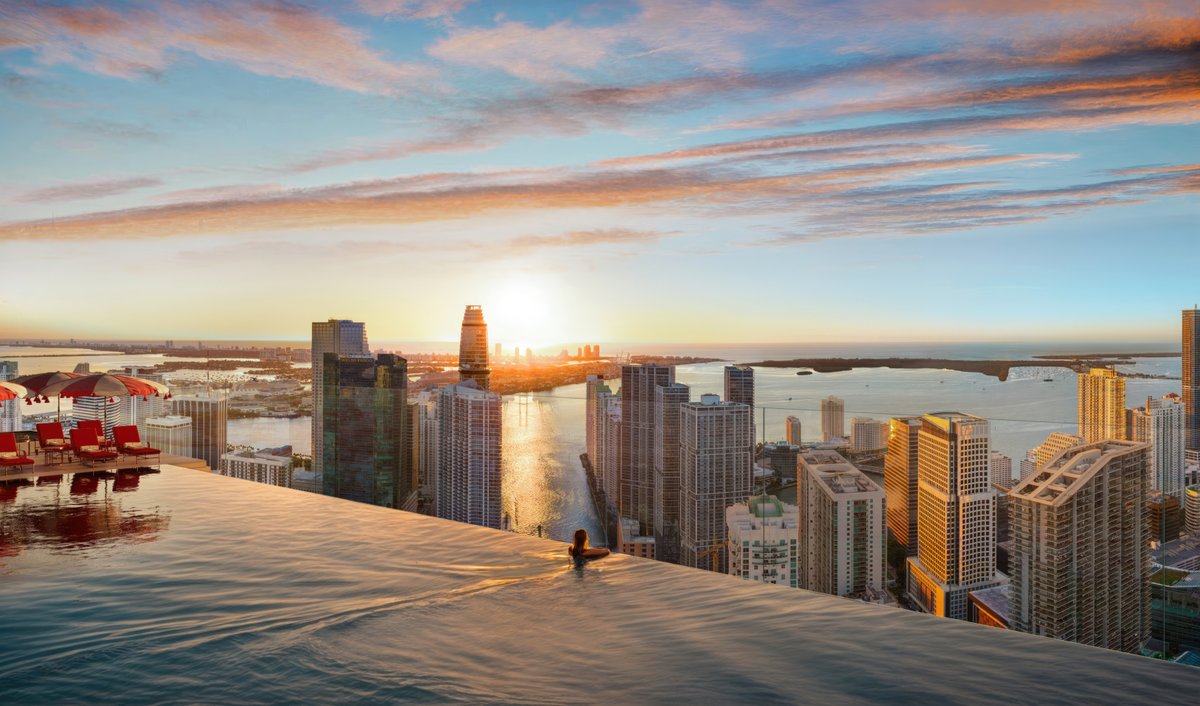
LARGEST CONDO CONSTRUCTION LOAN IN FLORIDA HISTORY JUST CLOSED IN MIAMI!!
The largest condo construction loan in Florida history just went to the Faena Residences Miami.
$817M from Elliott-backed Tyko Capital to build two towers on the Miami River, with a private yacht dock and an infinity pool over the river 👀
~45% sold. One penthouse went for $30M.
Everyone said the Miami wave was over when migration slowed, meanwhile Miami continues to break records.
Delivery in 2030. More info: https://t.co/fB2NE82Giu
When lenders compete to fund most of the cost on ground-up, closing is the easy part. The money still moves one draw at a time, and the borrower who sends a clean package each month, invoices coded once and waivers tied to them, is the one they want back. https://t.co/jkAQWrNQN6
Retail is suddenly the belle of the ball for CRE lenders. Five years ago it was the asset class nobody would touch.
What changed isn't retail. It's everything around it.
Office took retail's seat as the sector lenders are scared of, and credit books need somewhere to go. Retail supply has barely grown in a decade, so the centers that survived 2020 are running at occupancy levels that make underwriting easy. The tenants that were going to fail already failed. And unlike multifamily, nobody has to argue about whether rent growth is real, because the leases are already signed.
So a retail deal that gets shown to 75 to 100 lenders today draws real competition: 75% of cost on ground-up, perm pricing as tight as SOFR + 150. Numbers that would have been a joke in 2021.
The lesson is bigger than retail. Lender sentiment runs five years behind the fundamentals in both directions. The sector everyone is avoiding right now is the one worth underwriting.
One loop, every property. Invoices in. Auto-allocated to the right property and budget line. Waivers verified, duplicates flagged. Package built. Funded. You review once. Then submit.
See it on your own draws. Book a demo at https://t.co/rJYTKqpfWj: https://t.co/A0mgzawH7Z
Transparency is leverage, and it starts long before a workout. A borrower who can show every invoice coded once, each draw reconciled and every lien waiver tied to its invoice gives the lender facts, not promises, to frame the talk. https://t.co/XizstOFxA7
We are releasing a white paper obliterating the notion that a loan workout is somebody making a call to a connection, like a reverse mortgage broker.
Restructuring commercial real estate loans often requires the lender to accept a discount. Asking politely or going over an asset manager to a department head is not the path to them accepting reality. The borrower must show why doubling down on a failed borrower is reputationally sound for the asset manager and financially sound for the lender.
Game theory studies decisions in which the result depends on what the other party decides, so neither side can choose well until it has worked out what the other will do. In a workout, the lender decides whether to modify or foreclose based on what it expects from the borrower, and the borrower’s proposal only works if it reads the lender correctly.
Waiting impacts the two sides of a workout differently. The borrower’s equity is a call option on the property struck at the loan balance. If the market recovers, that payoff is convex, which is why a restructuring that costs the lender a little can be worth a great deal to the borrower.
The lender holds the opposite position. Its payoff is capped at par plus interest however far the asset recovers, and its cost of funds accrues every month the loan is outstanding, so waiting is a negative carry on a non-performing loan.
Economics alone isn’t enough. The Ultimatum Game is when one player holds $100 and proposes a split. If the second player accepts, both keep their shares. If the second player rejects, neither gets anything. A purely rational second player would accept $10, since $10 beats zero. In practice, people reject offers they consider unfair, giving up their own share to deny the other side its $90.
While rejecting a borrower’s discount offer can be wrong economically, a bad borrower, especially under a modification, can be politically damaging to the individual and the firm.
Commercial real estate usually measures success by closed deals. Loan workout aren’t deal and success is built to a crescendo. Each decision impacts the next one in the process, even several moves later.
A borrower skilled in operations is unlikely to also be skilled in loan workout negotiations, and an operator skilled in loan workout negotiations won’t instills confidence in their lender. Out-of-court commercial real estate restructuring is a small and unusual corner of the industry, and its many moving parts are often underappreciated. Its perceived simplicity belies its complexity.
In out-of-court commercial real estate loan workouts, the best way for the borrower to manufacture leverage is to share its institutional knowledge of the property, tenants, market and future potential. Any lender stepping in must start from scratch. Helping the lender with transparency helps frame the negotiation in realistic terms to produce better chances of borrower success.
Buckle up, this is complicated. Stay tuned.
A contractor lien is a lot easier to catch before it's filed. Keep every lien waiver tied to its invoice and each draw shows who has been paid and who hasn't, so the owner and lender see a gap while it's still a conversation. https://t.co/EHpPwA5Xwo
Planned conversion of the former USA Economy Lodge into a 226-unit studio apartment complex in Birmingham, Alabama results in foreclosure and $1M contractor lien.
Phase 1 successfully delivered 60 units in the smaller building by late 2025. However, Phase 2—slated for the former motel’s main building—stalled completely.
Fuse Group provided $13M in bridge/construction financing in 2025. Following the project's stagnation, Fuse Group foreclosed on the property and sold it at auction in October for $5.93M.
-bizjournals
#CommercialRealEstate