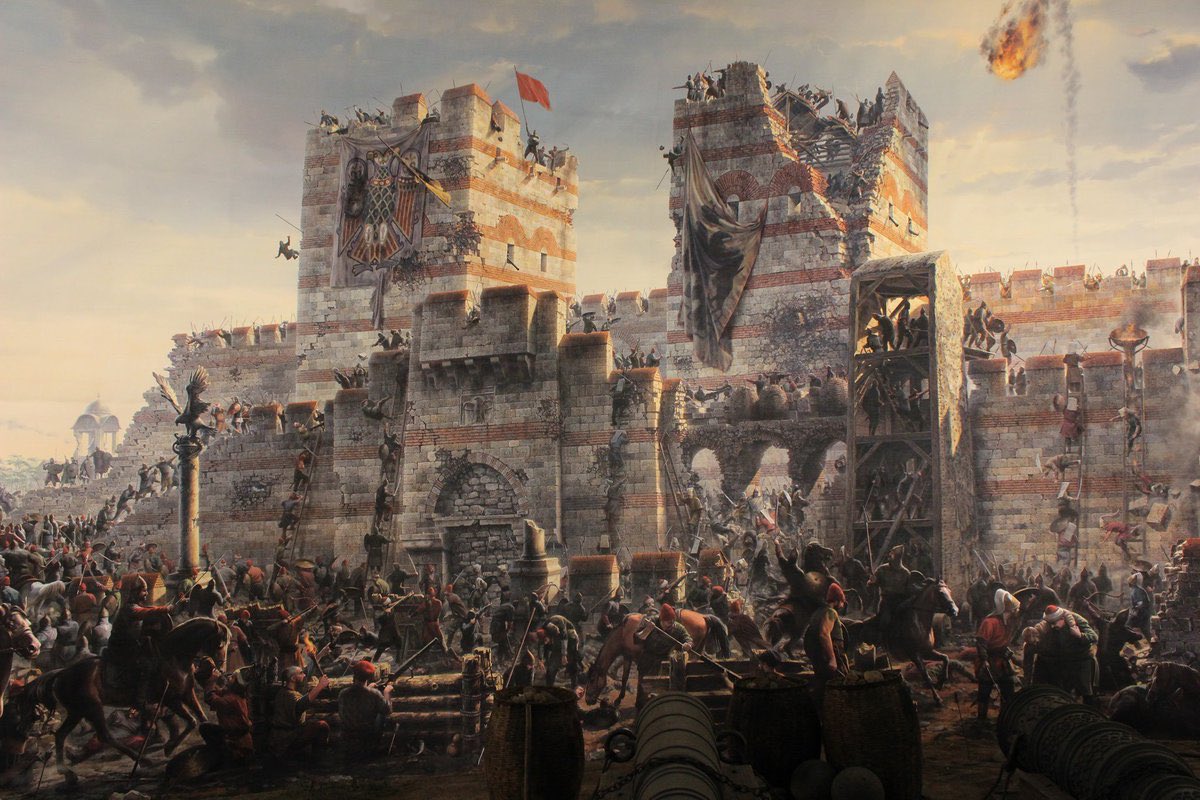
Today, 570 years ago, Ottoman Janissaries poured over the Theodosian Walls. The Genoese fled when their leader, Giovanni Giustiniani, was injured. The Emperor threw himself into the hopeless struggle & died with his men. After over 2,000 years, the Roman Empire was no more.
This past weekend in Austin, @Shopify built a Creator Mart. It was a fully immersive experience filled with the most successful creator-built brands in the world, all powered by Shopify.
Incredibly proud of the @Shopify team behind this.
I have a daily, 30-minute time block dedicated to brainstorming new ways to pitch the ideas I want to land at work.
I started doing this a few months into my first job as an account manager at FB. It’s been on my calendar ever since. Why?
If you’ve ever worked in sales (especially tech sales), you are intimately familiar with “the moment of no return” — when you’re pitching a solution and lose someone’s interest.
What does that moment look like?
Their eyes lose focus. They start looking around. They get really quiet. Their energy and body language change. They deflect responsibility because they don’t want to say that they don’t get the concept (“Ok, let me talk to the team later…” *quickly changes subject*)
Basically, they:
1) Zone out and go somewhere else in their mind.
2) Are self-conscious about not understanding the solution.
Both of these areas can only be fixed by YOU, as the person bringing the idea to life for them.
I’ve found that most people only adopt a new solution, product or strategy when they understand it — or its value — enough to explain it back to you.
They need to feel confident enough to become a short-term ambassador for your solution. It’s the only way you’ll get buy in and resources from other key team members or decision makers.
That’s where the 30-minute time block comes in:
Create as many explanations as possible for the solution and its benefits so you don’t spend months saying *the same pitch* over and over, and get nowhere but “the moment of no return” on loop.
The pitch that resonates most with you… might not resonate with your audience.
Remove yourself (and your bias) from the equation, and figure out how to say the same thing in 10+ different ways.
(You won’t say all of these in one meeting, but you can throw 1-3 around each time until one sticks.)
Coming up with all of these different explanations is not easy, but it pays off.
For me, this 30-minute time block:
• Shaved off *months* of client back-and-forth and made my pitches so effective that I was regularly asked to scale them to the org
• Helped me far exceed my sales goals every quarter for 4 years
• Gave me time back to do fun, outside-of-scope things like: ideate and launch 2 products, create multiple global programs (i.e. ad grants), and build a pilot program that became a new org (accidentally deprecating myself, oops!)
Let me know if you try it out.
It was a game-changer for me in sales, and continues to be one now that I’m in product. (My clients are just in my own company now.)
P.s. A nice little bonus is that actively looking for “the moment of no return” while selling/pitching will also make you a way better conversationalist and storyteller. 👀
The gov’t has about 48 hours to fix a-soon-to-be-irreversible mistake. By allowing @SVB_Financial to fail without protecting all depositors, the world has woken up to what an uninsured deposit is — an unsecured illiquid claim on a failed bank. Absent @jpmorgan@citi or @BankofAmerica acquiring SVB before the open on Monday, a prospect I believe to be unlikely, or the gov’t guaranteeing all of SVB’s deposits, the giant sucking sound you will hear will be the withdrawal of substantially all uninsured deposits from all but the ‘systemically important banks’ (SIBs). These funds will be transferred to the SIBs, US Treasury (UST) money market funds and short-term UST. There is already pressure to transfer cash to short-term UST and UST money market accounts due to the substantially higher yields available on risk-free UST vs. bank deposits. These withdrawals will drain liquidity from community, regional and other banks and begin the destruction of these important institutions. The increased demand for short-term UST will drive short rates lower complicating the @federalreserve’s efforts to raise rates to slow the economy. Already thousands of the fastest growing, most innovative venture-backed companies in the U.S. will begin to fail to make payroll next week. Had the gov’t stepped in on Friday to guarantee SVB’s deposits (in exchange for penny warrants which would have wiped out the substantial majority of its equity value) this could have been avoided and SVB’s 40-year franchise value could have been preserved and transferred to a new owner in exchange for an equity injection. We would have been open to participating. This approach would have minimized the risk of any gov’t losses, and created the potential for substantial profits from the rescue. Instead, I think it is now unlikely any buyer will emerge to acquire the failed bank. The gov’t’s approach has guaranteed that more risk will be concentrated in the SIBs at the expense of other banks, which itself creates more systemic risk. For those who make the case that depositors be damned as it would create moral hazard to save them, consider the feasibility of a world where each depositor must do their own credit assessment of the bank they choose to bank with. I am a pretty sophisticated financial analyst and I find most banks to be a black box despite the 1,000s of pages of @SECGov filings available on each bank. SVB’s senior management made a basic mistake. They invested short-term deposits in longer-term, fixed-rate assets. Thereafter short-term rates went up and a bank run ensued. Senior management screwed up and they should lose their jobs. The @FDICgov and OCC also screwed up. It is their job to monitor our banking system for risk and SVB should have been high on their watch list with more than $200B of assets and $170B of deposits from business borrowers in effectively the same industry. The FDIC’s and OCC’s failure to do their jobs should not be allowed to cause the destruction of 1,000s of our nation’s highest potential and highest growth businesses (and the resulting losses of 10s of 1,000s of jobs for some of our most talented younger generation) while also permanently impairing our community and regional banks’ access to low-cost deposits. This administration is particularly opposed to concentrations of power. Ironically, its approach to SVB’s failure guarantees duopolistic banking risk concentration in a handful of SIBs. My back-of-the envelope review of SVB’s balance sheet suggests that even in a liquidation, depositors should eventually get back about 98% of their deposits, but eventually is too long when you have payroll to meet next week. So even without assigning any franchise value to SVB, the cost of a gov’t guarantee of SVB deposits would be minimal. On the other hand, the unintended consequences of the gov’t’s failure to guarantee SVB deposits are vast and profound and need to be considered and addressed before Monday. Otherwise, watch out below.