🚨10X Stocks - My New Book Published worldwide on April 6th
Happy to share it’s already #1 New release and #9 Best seller in Business/Valuation on Amazon 😊
The book as the title says is about:
8 Frameworks on ‘How to Pick Multibaggers’
Order 👉 10X Stocks: How to Pick Multibaggers https://t.co/aZTJWnj7c2
$META Q3
/THE PRINT/
- Revenue $64.6B
- GAAP EPS $3.83
- Q4 guide $73–76B — above $73.6B consensus
/THE TWO NUMBERS TVST STANDS OUT/
1. 2026 capex guide: MOVED UP —
$130–145B → $135–145 billion
2. Muse Monetization: adoption is awesome —
10M+ US/CA setups, shopping the top use case. But still no revenue reported: no enterprise contracts, no API traction number, no transaction fees. Need to track usage curve 📈
My take: The ad engine is strong enough to fund the capex creep for now, and "personal superintelligence" got its first usage datapoints.
$META Preparing for funds raising in 2027, through dilution:
Meta's board approved a new non-voting Class C, issued as a one-time stock dividend: one Class C share for every Class A and Class B share you own, debuting January 19, 2027.
That step is economically neutral — same as Alphabet's 2014 GOOG split. Your slice of Meta's earnings doesn't change; it's just re-sliced across two tickers, and your Class A votes are untouched.
Reuters is explicit: the class exists so Meta can fund the AI expansion — acquisitions, talent, capital raises — without diluting Zuckerberg's voting control.
Every future Class C share Meta hands to an acquisition target, an AI hire or the market is a real economic claim on the same earnings — borne entirely by existing holders, while control stays exactly where it is.
Shareholders absorb 100% of the economic dilution of future issuance; Zuckerberg absorbs none of the control dilution.
🚨 The AI-trade rotation is on: cash-rich Mag 7 in, debt-funded neoclouds out.
$CRWV hit a 52-week low Tuesday ($57.23, HSBC Reduce $39 PT) while $META is +2% into Q3 tonight.
My take: funding is key differentiator now !!
🚨The Gigawatt Economy —
Jensen Huang's rule of thumb is now the most important ratio in markets:
“ 1 GW of AI data center ≈ $50B to build → $40B of revenue a year”
So I counted the GWs 🔋
Across every neocloud and AI host I track — listed, private, and the colocation landlords underneath them —
There will be 45.9 GW contracted/targeted or in pipeline for 2027
At Jensen's math, that is $1.8 trillion of potential annual revenue
1. $SPCX : The Super Intelligence (SI) segment (the xAI business)—
Nameplate compute: 1.7 GW up from 0.6 GW a year ago
SI capex in the quarter alone: $16.4B
But the real proof is in the leases:
• Anthropic pays xAI ~$15B a year for Colossus capacity, through May 2029
• Google pays ~$11B a year for 110,000 GPUs at Colossus II, through June 2029
2. Do the per-GW math per Anthropic S1:
Anthropic's deal works out to ~$37.7B per GW per year.
Google's works out to ~$55.2B per GW per year.
Per S1, Anthropic Infrastructure commitments: $518B over the next decade — 80% of it non-cancelable, owed mostly to Google ($111B), Amazon ($110B), and Microsoft ($31B) $AMZN $GOOGL $MSFT
Neocloud and COLOC GW availability and potential revenue $NBIS $CRWV $IREN $CIFR $APLD 👇
$CRDO is the biggest beneficiary of $SPCX xAI Buildout
And $CRDO is just up 18% last 1 year inspite of gross profits doubling to $300 million during this time
🚨Elon Musk just Said
“Our belief is that the value of compute per watt will increase over time, not decrease”
And the reason that for that??
He attributes to the useful intelligence per watt. And that's why you see things like even old computers like H100s renting for more than they rented when they were new.
Here’s the rental price increase/watts $CRWV $NBIS $SPCX
BREAKING NEWS🚨🚨: TODAY META CONFIRMS THEY ARE RUNNING TPU INFERENCE IN PRODUCTION. What does this mean for the CUDA moat?
For those who read our public newsletter, this is not a surprise, as on Nov 28, 2025, we publicly wrote that Meta is a TPU customer & has lots of engineers working on TPUs. Our accelerator supply chain model has details about Meta's TPU procurement!
SpaceX's Q3 was the quarter the rocket company became an AI company
AI accounts for 52% of consolidated revenue, up from just 15% a year ago $SPCX 👇
https://t.co/0Z9Mmmfruf
$SPCX earnings in 1 slide.
The optionality of AI Cloud has explosive growth potential 📈
SI segment now accounts for 52% of consolidated revenue, up from just 15% a year ago, powered by new cloud services agreements
SI also swung to its first operating profit ($431M, even after absorbing $1.2B of Cursor stock comp !! )
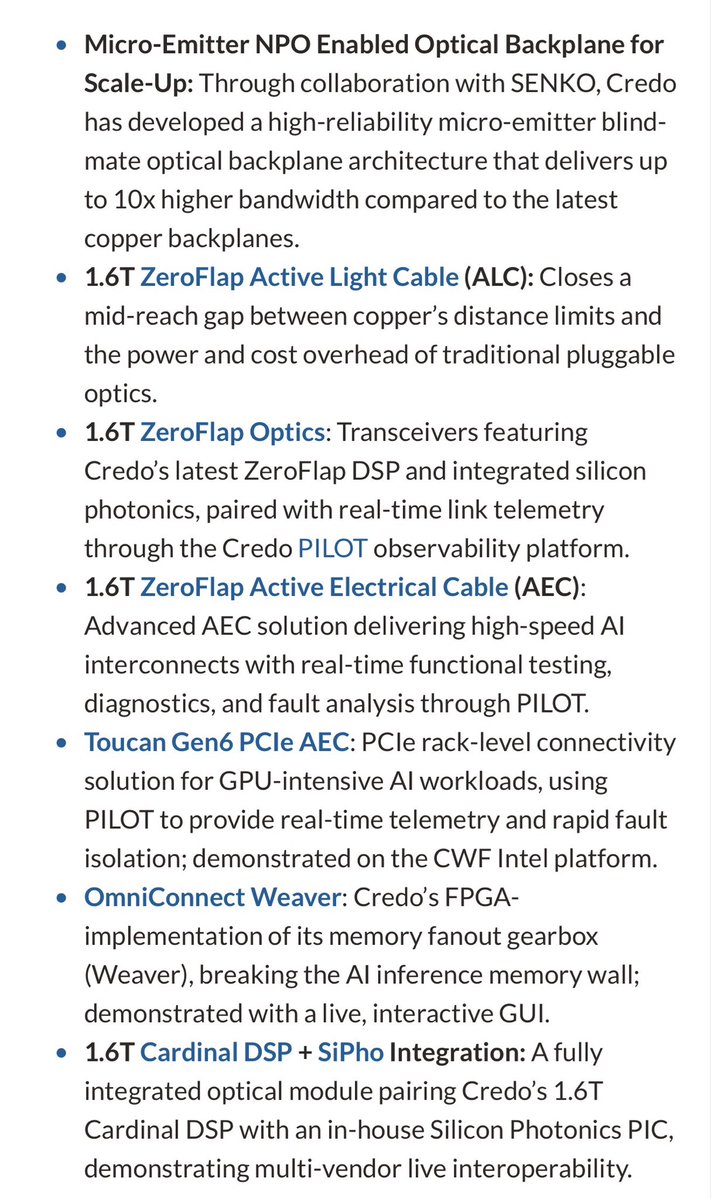
$CRDO at #OCPSummit2026 is showing it’s no longer just a copper-cable story.
🚨New launches include
✅ 1.6T ZeroFlap Optics with in-house silicon photonics
✅ 1.6T Active Light Cable bridging copper’s reach limits and pluggable optics’ cost
✅ A micro-emitter optical backplane with up to 10x copper bandwidth and
✅ Cardinal DSP + SiPho fully integrated modules.
Optics as a share of revenue:
Optics should be roughly 24–25% of FY27 (ending Jan 2027) revenue.
$600 million in optical revenue in fiscal 2027 and with that ramp Crefo’s total revenue will grow >> than 85% from fiscal 2026.
FY26 revenue was $1.335 billion. so FY27 comes to about $2.47B and $600M of that is about 24% <ZeroFlap offerings, silicon photonic PICs and optical DSPs>
🚨 GPU rental prices are RISING. Demand is real—
/COMPUTE PRICING PULSE/
Silicon Data's neocloud rental index stood at $2.82/GPU-hr for H100 vs $2.37 for H100 when the index launched in May 2025
📈 $NBIS raised the card on Oct 1 —
H100 to $4.50/hr (+17%)
H200 to $5.40 (+20%)
B200 to $8.50 (+19%)
B300 to $9.50 (+21%).
A cloud raising prices by a fifth is the purest evidence compute is scarce, not glut !
Nebius reaffirmed its $3–3.4B 2026 revenue guide — same volume, more per hour is nearly higher margin.
Hyperscalers are marking up too. AWS raised reserved capacity-block rates effective Oct 7: H100 $5.191 → $5.97 /hr (+15%), B200 to $14.208, B300 to $16.1
Cloud(neo) companies raising prices 20% into a market where its own cost of capital is double digits is not showing distress — it's showing a seller's market.
My take: The credit selloff has repriced the financing, not the core GPU/TPU Datacenters !! $NVDA $GOOG $CRWV
🚨: TPUv7 FP8 submission showing better performance / dollar is indicating an inflection point for TPU adoption curve 📈
Especially in the rapidly evolving agentic world — $META Muse, Dots, Grok, Instinct
Bullish for $AVGO $GOOGL
ALERT🚨: NVIDIA has been working overtime, nights, and weekends after being shocked 🤯 by last week’s TPUv7 FP8 submission showing better performance per dollar.
Unfortunately for NVIDIA, its first GB300 FP4 counter-submission is still 1.64x worse in performance per dollar than TPUv7 for external customers across most of the end-to-end performance curve.
The x-axis of the graph below uses end-to-end latency, so a higher curve is better. The TPUv7 curve has higher perf per $ across most of the E2EL Pareto frontier.
This initial submission looks like NVIDIA’s first attempt to close the gap, but the gap is still massive. We expect more counter-submissions from NVIDIA as they continue trying to narrow the difference.
🚨 $LITE:LUMENTUM SOLD OUT TILL 2029
I don’t know whether Memory demand is structural but I for sure can see ‘AI Optics’ is a secular trend for foreseeable future 🚀
CEO Michael Hurlston says “DEMAND GOING UP EVERY DAY!! “
Lumentum has increased core production capacity in the Tokyo area , 12X over two years and plans at least $350 million in further facility expansions 📈
Lumentum is working with Astera Labs on PCIe optical interconnects and demonstrated PCIe-over-optics connectivity with Astera and Corning at the OCP Global Summit $ALAB $GLW
$LITE is also a founding contributor to the Open Compute Project’s short-reach micro-emitter optics standardization effort.
They also announced demonstrations at ECOC 2026 of an 8-wavelength laser module and a die-to-die optical interconnect developed with Qualcomm Technologies and Corning $QCOM $LASR
🚨 Retail bought a RECORD $700M in neocloud stocks the week ending Oct 11 while $CRWV bonds priced in distress at 16% yields — Citadel
hedge funds dumped AI names at the 2nd-fastest pace in a year — per Goldman
Institution is selling the leverage. Retail is buying when momentum has broken — who is right?? $NBIS
$META Muse Wonder models made “Active Memory” the headline feature last week
‼️You won’t make money from here on, being on the wrong side of the memory trade.
Training made memory the ‘bottleneck’ but Agents use memory in a completely different way. Let’s see how ??
/ Agentic era: An agent loops: plan → act → observe → replan. Each loop re-sends the full working context. The weights are frozen, so the intelligence lives in state, and state lives in memory.
1. Meta’s Muse runs in its own cloud VM and keeps working after you close the app.
> Active Memory is Meta’s Muse Wonder feature that saves the important details from your past conversations and pulls them back into the prompt when they become relevant.
> Every recalled memory becomes extra tokens in the context window, and every token adds keys and values to the KV cache sitting in HBM for as long as the session stays live.
> Will it drive more HBM demand? Yes, but only modestly on its own, since the recalled memories are small. The real HBM driver is what memory enables: always-on agents running longer, multi-step loops with huge contexts across millions of users at once.
2. OpenAI’s Dots are always-on agents inside ChatGPT. They inherit your ChatGPT memories and keep their own private notes between conversations.
HBM will still be the toll booth. Every loop needs the weights plus the KV cache. Agents don’t run one giant batch; they hold thousands of always-on sessions, each with a big working set. $MU $SKHY Samsung hasn’t peaked yet !! $DRAM 📈
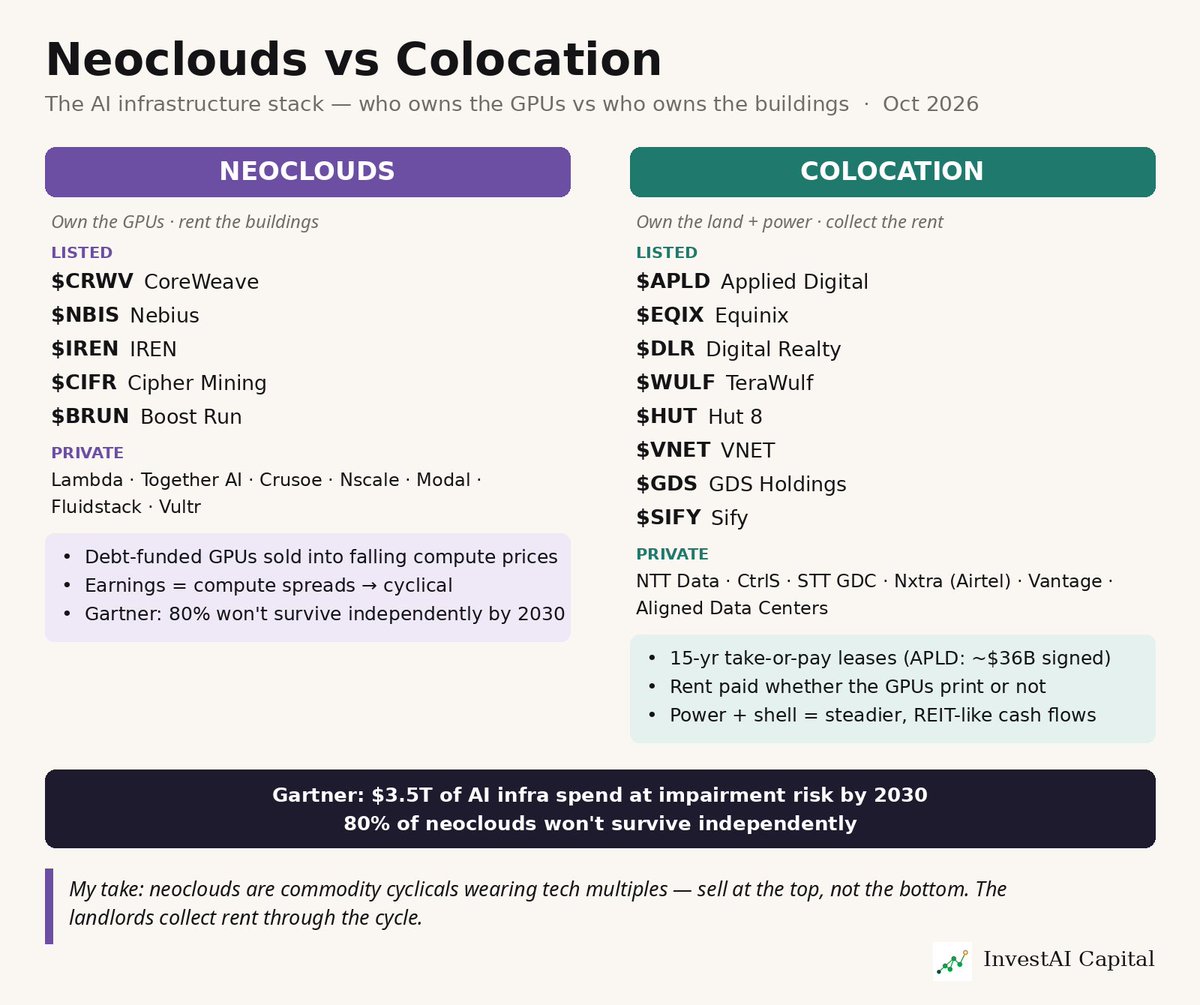
🚨 Gartner: over $3.5T of AI infrastructure spending could face impairment by 2030 — owners need $8.5T in revenue to justify the buildout, but only $3.6T is forecast.
And 80% of neoclouds won't survive independently. The math is the trade now. per Gartner
1/ My take: neoclouds are commodity cyclicals wearing tech multiples. They buy depreciating GPUs on leverage and resell compute into falling prices. Colocation like $APLD is the landlord — $36B of 15-yr take-or-pay leases, rent paid whether the GPUs print or not.
2/ Neocloud may have earnings peak in 2027 or 2028— that's one or 2 years of runway. $NBIS $IREN $CRWV $CIFR $BRUN get sold like cyclicals: at the top, not the bottom. $BRUN is already -79% from its high.
3/ See both sides of the coin: Neocloud vs Colocation. For ex:
$BRUN — Boost Run, AI-neocloud listed May 2026, now $8.89, -79% from its $42 high
And now $APLD is contrast: take-or-pay leases (1.4GW), rent paid whether the GPUs print or not.
(One flag: $APLD isn't risk-free either — debt jumped $5B→$6.3B in a single quarter per Reuters, stock -49% from its high. The long side has leverage too)
DYOR, NFA
🚨 In global AI carnage, 🇮🇳 India euphoria:
Sensex +2.11% (biggest day in 4 months), Nifty +1.66% to 22,997. Jio IPO filing lit up Reliance.
TCS +15% profit, $3.1B AI run-rate;
WIPRO Q2 revenue +9.1% to ₹24,753cr, beat estimates; shares +4% Friday to a 6-week high.
Nifty IT +1.8% led Thursday's +1,534-pt Sensex surge. AI isn't killing India's coders — it's unlocking new revenue. per BusinessLine, Reuters
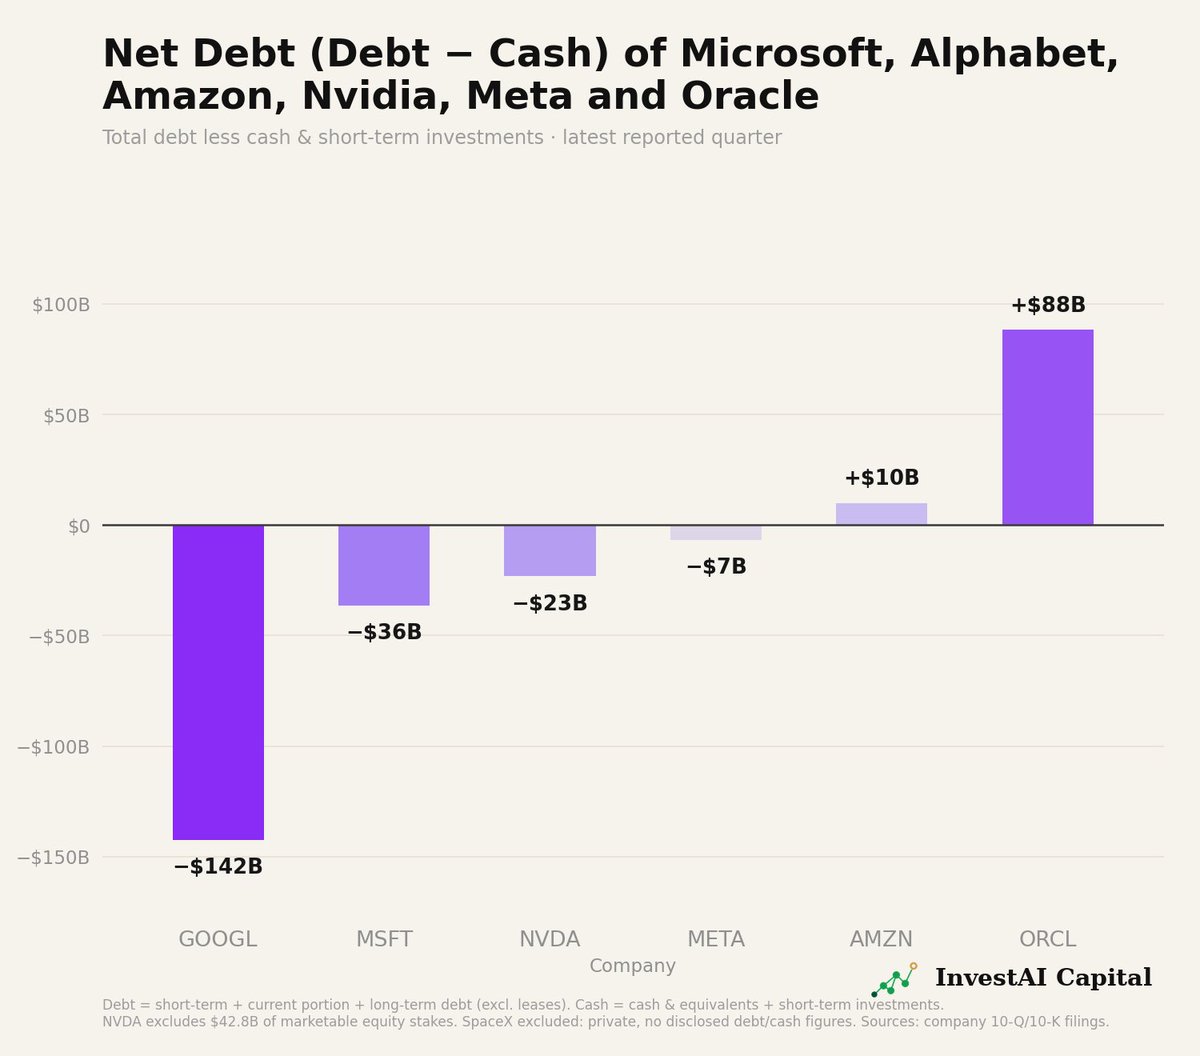
🚨 Oracle is the ‘only’ real net debtor in the group at +$88B —
All other Hyperscalers are still net cash ➕
, even after the borrowing binge.
Google raised $100B in debt and still sits on $142B of net cash.
Note: Debt excludes leases; NVDA's $42.8B of equity stakes excluded from cash.
My take: AI is becoming the "who survives the capex cycle" chart. But we are far from peak of a bubble !!
There are no excesses anywhere and all-around negative sentiment at institutional level.
Today could well be the bottom before Q4 rally 📈 $NBIS $CRWV $NVDA $CRDO $LITE