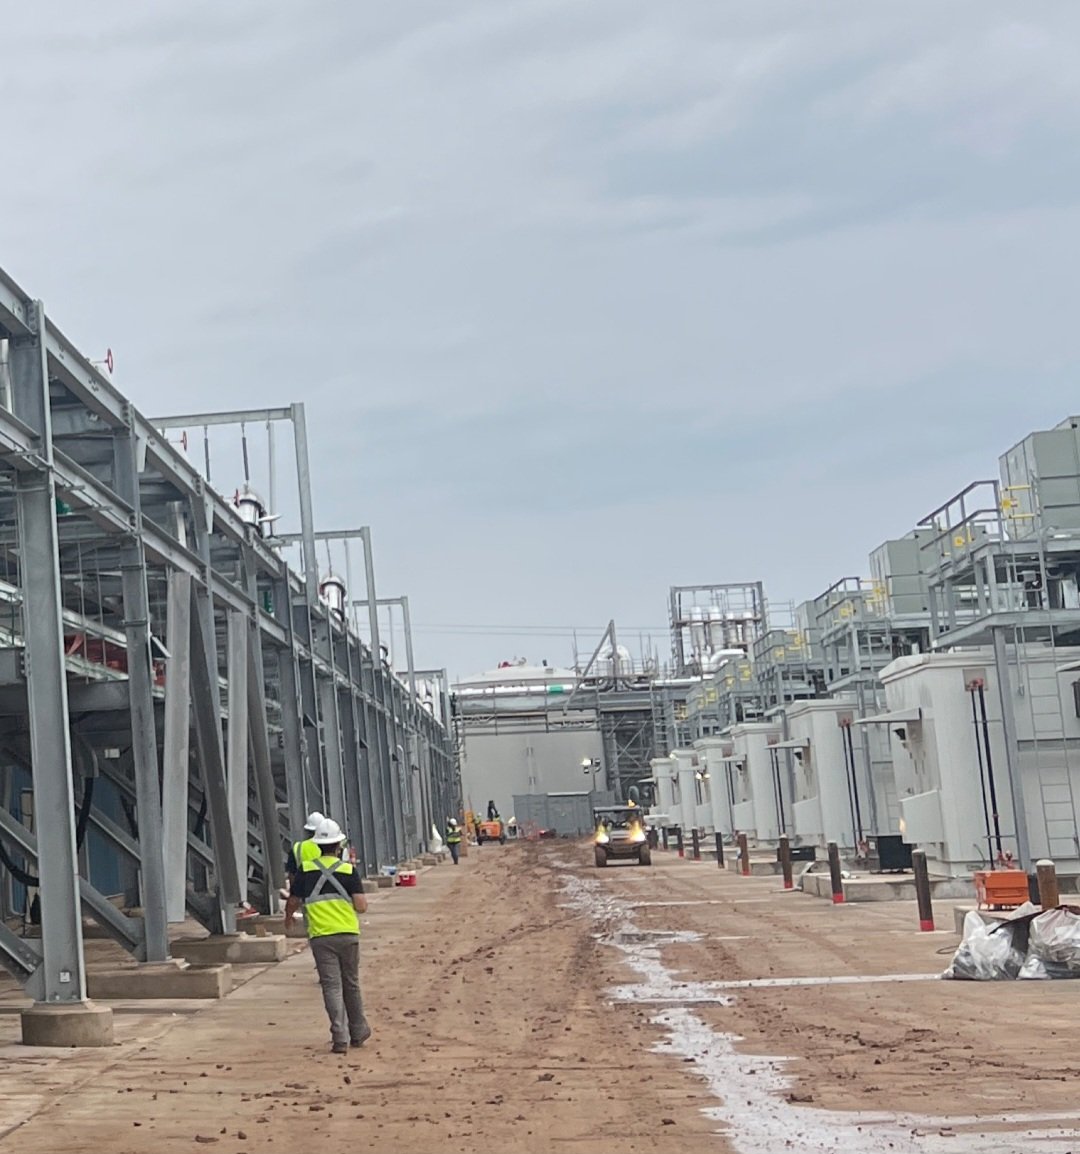
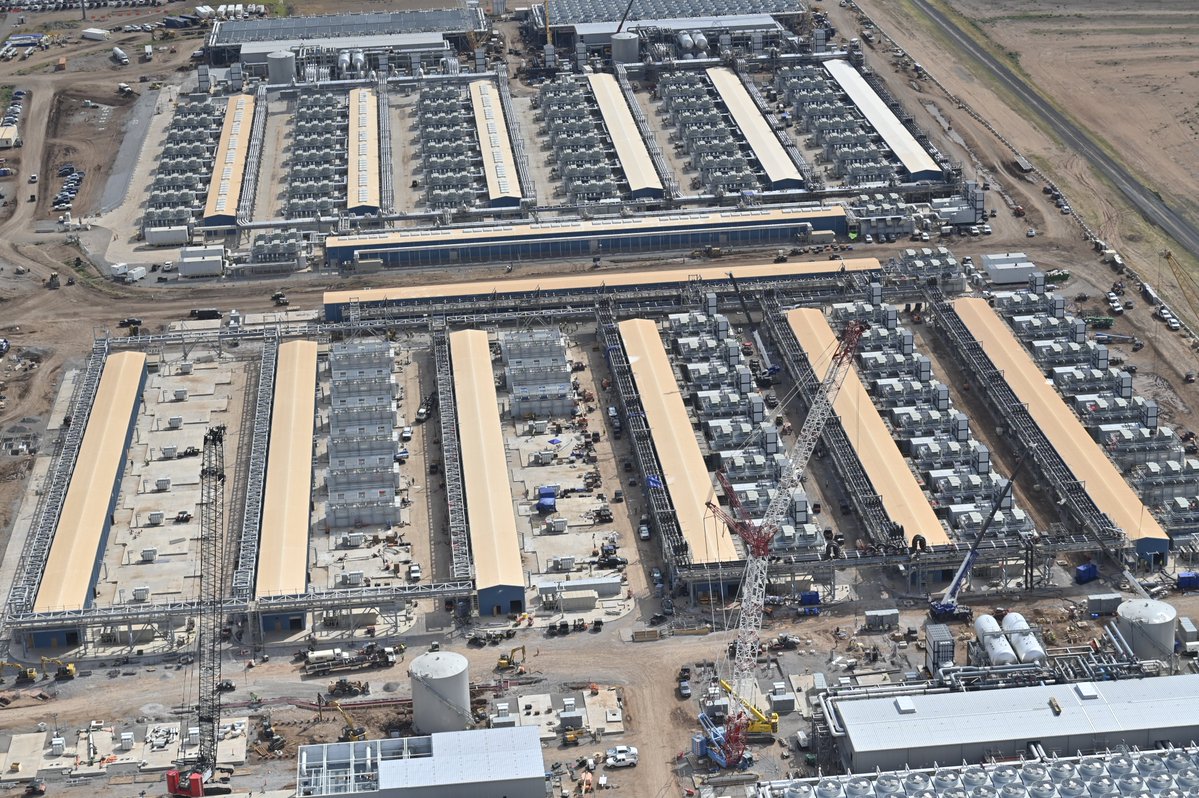
What's that?
$IREN's Horizon 2 has no scaffolding?
Could it be almost ready perhaps?
Surely they need to make way for the paving so Microsoft can drive their security carts around?!
But execution risk and shit bro!
Imagine worrying about copy-pasting the 2nd time around 😂
So if the situation isn't clear, I'll spell it out for you once more.
- $IREN will build their 2026 ARR capacity inside the given time frame. (Source: me).
- Iren will monetize their 2027 capacity (Source: demand environment).
- Iren IS CHOOSING their 2nd cycle clients now, THIS IS A POSITION OF STRENGTH YOU FUCKING RETARDS.
- Stickiness is baked into the cake you idiot hedge funds.
Have a good weekend.
1/ $CIFR announced Sept 25: Barber Lake goes from 10 years of contracted term to 20. Fluidstack keeps the front decade. A leading AI lab (unnamed) signed a binding commitment for a separate 10-year lease after that, on terms "substantially consistent" with the existing one.
2/ That second decade adds ~$5.2B of contracted revenue. Site total goes from $3.8B to over $9B. Halls now deliver in phases, Q4'26 through Q1'27, with rent starting as each hall delivers. First rent expected Q4'26.
$IREN is a vertical integrated AI cloud provider, who's signing contracts with clients that are shaping the foundation of AI adoption.
This is not a 1 cycle play
Stickiness matters in a demand limited environment, but game theory is not in force as long as power is constrained.
1/ $IREN is down ~16% from its Sept 22 close ($48.55 to $40.65). AI demand is not the issue. Funding a $25-30B FY27 capex plan with the 10-year at its highest since 2002 is.
2/ They have ~$14B of cash, committed GPU financing and prepayments against that plan, and are targeting ~$8B more of the same. 2026 capacity looks largely sold ($4B contracted ARR, ~$1B operating as of late Aug).
Citadel disclosed ~4.7% of $IREN (~18.6M shares). Goldman and BofA already there. GPU reserved pricing climbing ~15%. Power is still the bottleneck. We're 40% of the book, multi-year. Not advice.
6/ Our thesis hasn't changed: energized power and land are the AI bottleneck, and Cipher keeps turning megawatts into long-dated leases with hyperscale and AI-lab tenants.
We remain long $CIFR, ~28% of our book. Not advice.
1/ Follow-up to our Sep 3 $CIFR post on Cipher's gas laterals: enough fuel for up to 2.5 GW of on-site generation, with new power targeted before end-2027.
Four weeks later, here's where the numbers stand.
5/ Texas is the swing factor. On Sep 21 Abbott told TCEQ to halt data center permits until ERCOT's audit is done (report due by Dec 10). How that touches on-site gas generation is still unclear.
Dates we're watching: Oct 12, Oct 19, Dec 10.
I’ve been running a continuous excel sheet of research on $MSTR, Bitcoin, Treasury Co’s, credit, corporate earnings reports, broad market valuations, buyback history, etc.
Started in 2022. It’s 147 sheets and 1.2 MB of data.
I’m loading into SuperIntelligence platform.
Will inform context, build dashboards, run bot analysis, develop brain, etc.
Big data consumption.
@bitcoinbutcher1@StreamDataCentr $NUAI In-house build vs JV is a real risk/reward split. Their own 8-K says a direct lease without a dev partner raises cost + execution risk, but they keep more upside. Watching the Texas permit pause more than headlines