The paper is joint with Ester Faia and is about the business cycle statistics of 16 HANK and RANK models. We find very similar performance of HANK models in comparison to their RANK cousins. The Laffer curves are different. The video is available here https://t.co/PNCmrEzWZ1 2/2
It was a great pleasure to take part in @nberpubs SI Impulse and
Propagation Mechanisms Workshop. Huge thanks to @christiano3 and @EichMartin for putting together a stellar program and inviting our paper "What Central Bankers Can Learn from Models with Idiosyncratic Risk" 1/2
Excited to see our session on Macroeconomic Implications of Labor Supply and Reallocation in Heterogeneous Agent Economies in the latest 𝐀𝐄𝐀 𝐏&𝐏. Joint work with @DavidWiczer and Ester Faia! https://t.co/a6g6zvqxY6
Exciting news! I will join the Reserve Bank of Australia, Research department this September [conditional on visa, etc.]. I am looking very much forward to working with this talented group of researchers and economists at the @RBAInfo!
I owe a huge thank you to my fantastic advisor, Ester Faia.I am deeply grateful to @MariannaKudlyak, Alex Meyer-Gohde,and @DavidWiczer, who helped me enormously throughout the job market and with whom I had the pleasure to coauthor. I look forward to the new chapter of my career!
In the IMFS Working Paper 175, Alexander Meyer-Gohde & @ShabalinaKate show that including higher frequency information improves the forecasting performance of DSGE models, specifically with their new method that combines existing methods.#financialmarkets https://t.co/RVGiEhAzFw
You can find my JMP, other papers, and more info about me on [email protected]. I am very grateful to my advisors and co-authors Ester Faia, @MariannaKudlyak, Alex Meyer-Gohde, and @DavidWiczer for incredible guidance and support!
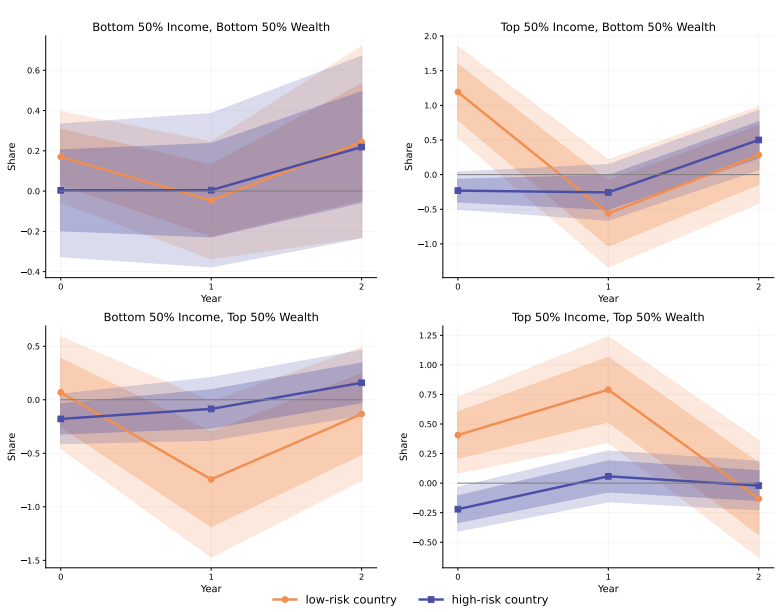
Hi #EconTwitter and #EconJobMarket! I'm a macroeconomist working with heterogeneous agent models, and I apply them to study international macro questions and the labor market. In my JMP, I ask what impact market incompleteness within a country has on international risk sharing.
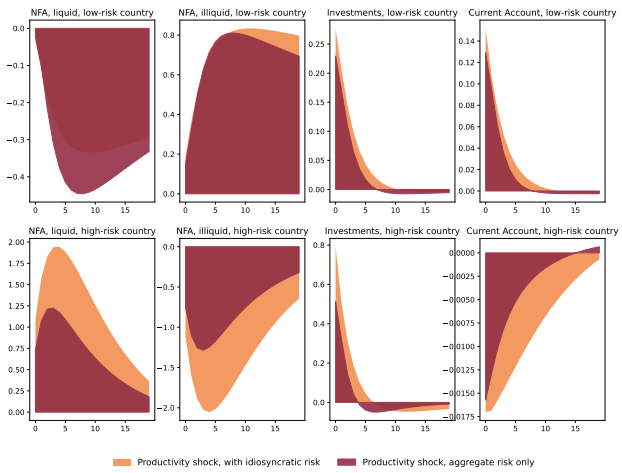
A key insight is that while individual MPS depend on risk and wealth, endogenous changes in wealth distribution are driven by risk and amplify savings responses to business cycles when risk is high, dampen them when risk is low. The latter result is also confirmed empirically.
Check out the presentation of our new paper "Monetary Policy and Wage Inequality: the Labour Mobility Channel" with @MariannaKudlyak, @DavidWiczer and Ester Faia. Ester presents at #QCGBF#VirtualSeminarSeries.
Registration link:
https://t.co/4TUvVHb628
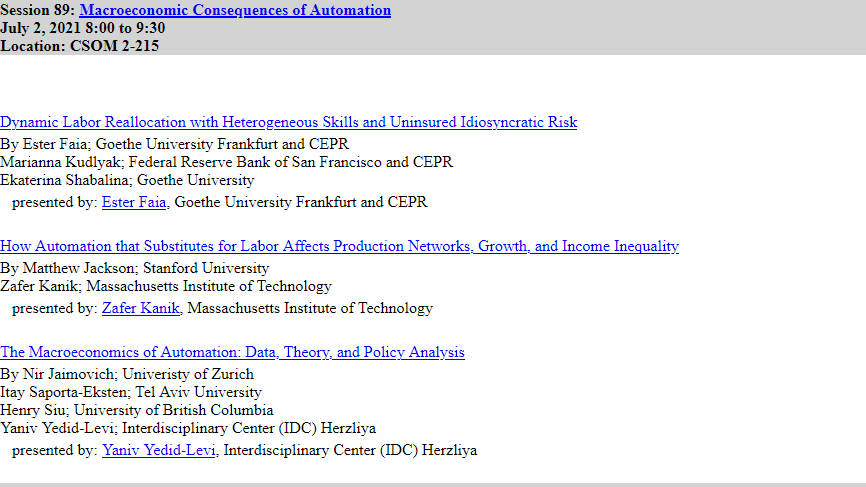
.@SEDmeeting My fabulous coauthor Ester Faia will present our work (w @ShabalinaKate) on dynamic labor reallocation with heterogeneous skills and uninsured idiosyncratic risk. Looking fwd to the Macroeconomic Consequences of Automation Session w @zafer_kanik@YedidLevi & others
Ester Faia @ShabalinaKate & I are motivated by
- Human capital is task-specific
- Wealth relative to potential earnings matter
- Reallocation shocks are often occupation-specific (automation, restaurants going from in-dining to delivery) and rarely shut entire sectors
1/3