Businesses no longer need a new payment system
to accept stablecoins.
We’ve raised strategic investment from @movement_xyz on this bet
Just add stablecoins. Keep everything else
go: https://t.co/kjVc0F027A
🚨 Pay with stablecoins. No Visa. No Mastercard.
We built a true stablecoin account that works on the POS terminals merchants already have.
Tap a card at a POS running our SDK and the payment settles in seconds. It goes stablecoin to stablecoin, without touching a card network.
What changes for the merchant:
→ better economics, with less card-network fees in the middle
→ same-day settlement
→ global coverage
→ they get paid in stablecoins or supported local fiat, whichever they choose
What changes for the customer: they pay straight from their stablecoin balance, and the tap feels exactly the same.
Underneath, @stableyardfi handles the whole flow, from account to acceptance to settlement.
For fintechs, wallets and banks, this is infra to offer stablecoin accounts people can actually spend.
I have shown in the demo how it works
If you're building in stablecoin fintech, DMs are open
global money, powered by Stableyard.
unified payment identities, vaults, on/off-ramps, deposit addresses and identity modules
all handled under the hood.
so money moves globally, while paying feels familiar.
biggest fintech insights i found at token2049:
> a lot of stablecoin fintechs are building the same thing with more or less the same partners. if one shared provider goes down, everyone relying on it feels it
> doubts about stablecoin adoption feel like yesterday’s conversation. stablecoins are becoming boring, which might be the clearest sign they’re going mainstream
> everyone was selling to everyone. more integrations are opening up, but who handles the local payout still matters
> showed @stableyardfi merchant acceptance demo to @DinersClub and @BVNKFinance and got a really good response
> met a few partners we’re onboarding this coming week for business accounts and other business offerings
> relevant inbound for @stableyardfi and @dopepayme, with potential integrations and partnerships to work through
> met folks from @Ripple , @circle and @NiumGlobal at their offices,
and the @JamieZammitt from bvnk team. also caught up with friends @0xAishwary from @0xPolygon , @_ryandesouza from @arbitrum and @AhaanRaizada from @base .
great catching up with old friends and meeting new faces.
came back with stronger opinions on which payment products people will keep using, and how much will change as the industry matures, regulations develop and banks get more involved. glad i made the trip.
Your business is global.
Your payments should move like it.
Introducing the Stableyard USD Business Account
for businesses, neobanks, remittance apps, and payment platforms.
Collect, hold, and move USD globally.
Give your users access to Fedwire, ACH, FedNow, and SWIFT through Stableyard.
→ USD ↔ USDC / USDT at 1:1
→ seamless on/off-ramps
→ local payouts in supported currencies
from customer collections to supplier payments and remittances, connect your users to global money movement through one integration.
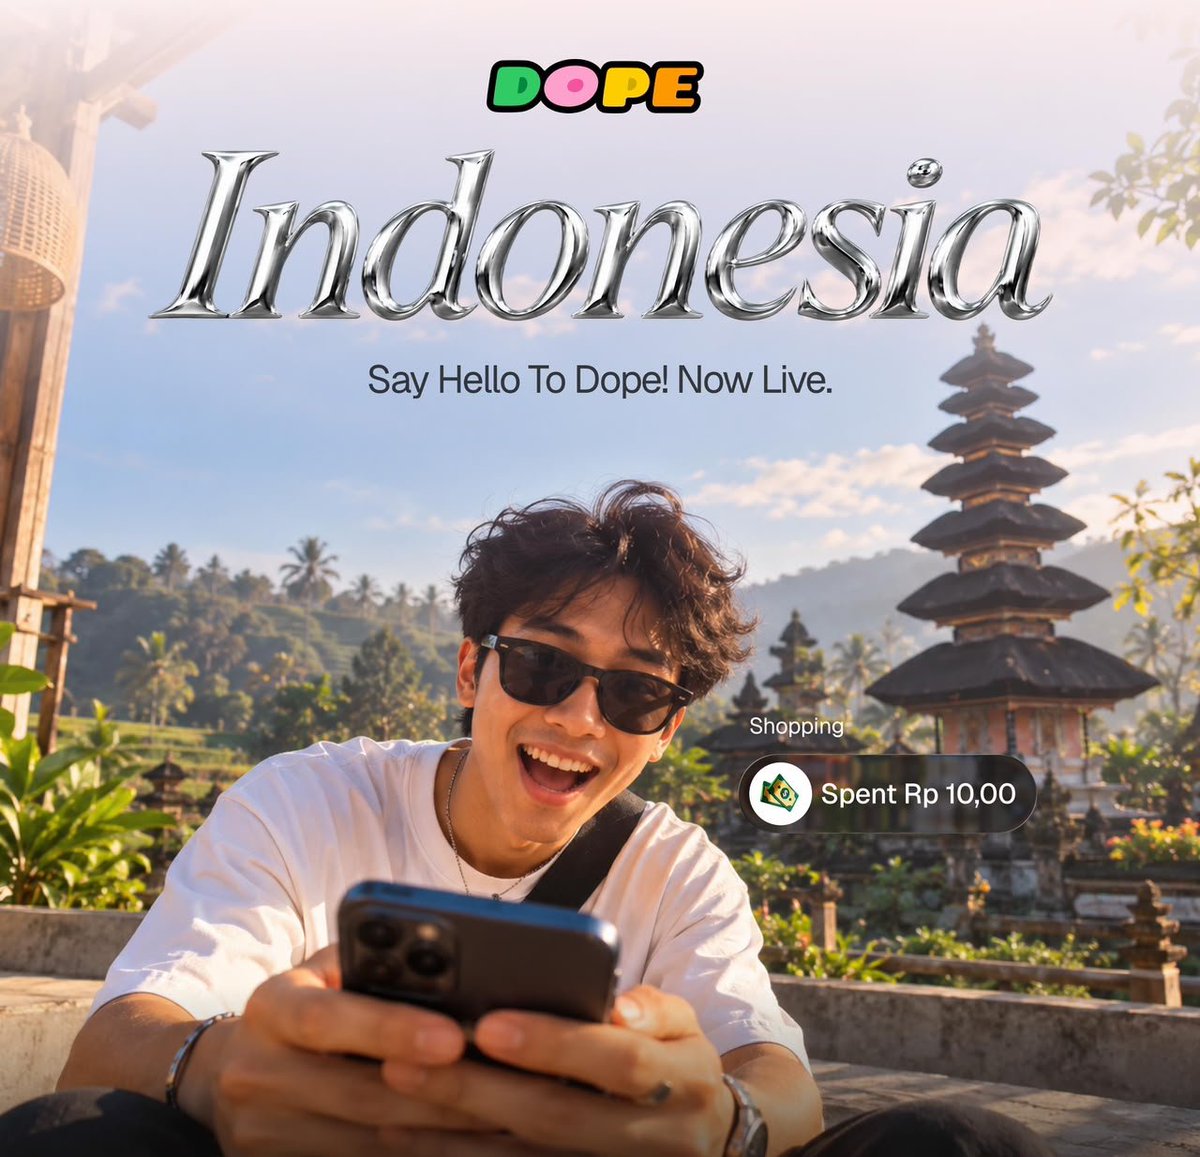
Dopepay is live in Indonesia 🇮🇩
→ send and receive money globally
→ convert crypto into IDR
→ pay like a local, without a local bank account
→ scan local QR codes and pay with crypto
Digital nomad, freelancer, or getting paid from abroad?
dope is your new favourite twin
(get up to $10: pay with dope in Indonesia & quote this tweet with your payment screenshot)
4 randomly selected users
if you’re in singapore, grab these two:
@0xavinash & @Rjparab
if you wanna know how Stableyard is solving the last-mile payment problem
and building a network advantage by making global payments work locally through existing systems.
and if you’re a payment business or exploring stablecoin payments in any way,
just talk to them. grab them for a coffee.
hey singapore 🇸🇬
I'm in town for @token2049
let’s grab a coffee if you’re looking for:
> better cross-border payments and remittances
> a fintech looking for on/off-ramps
> virtual accounts connecting fiat and stablecoins
> easy stablecoin infrastructure for payment operators, POS, and acquirers
> multichain and fiat deposit for crypto products
or just exploring stablecoin payments for your business.
Let’s talk. dm us
Team Stableyard is on the ground in Singapore for TOKEN2049.
if you wanna know more about Stableyard and our market thesis,
grab these two: @0xavinash & @Rjparab
stablecoins could take over finance without replacing the companies running it.
> are we watching fintech’s early days repeat?
> who wins when everyone can use the same rails?
> does cheaper settlement mean cheaper payments? https://t.co/yvRk5f2YgU
Stableyard is coming to token2049 singapore 🇸🇬
(ft @0xavinash & @Rjparab)
if you’re building in stablecoins, fintech, settlement, defi or payments, let’s meet.
would love to exchange cool ideas & market insights.
also: shill us the side events we absolutely shouldn’t miss
dms open.
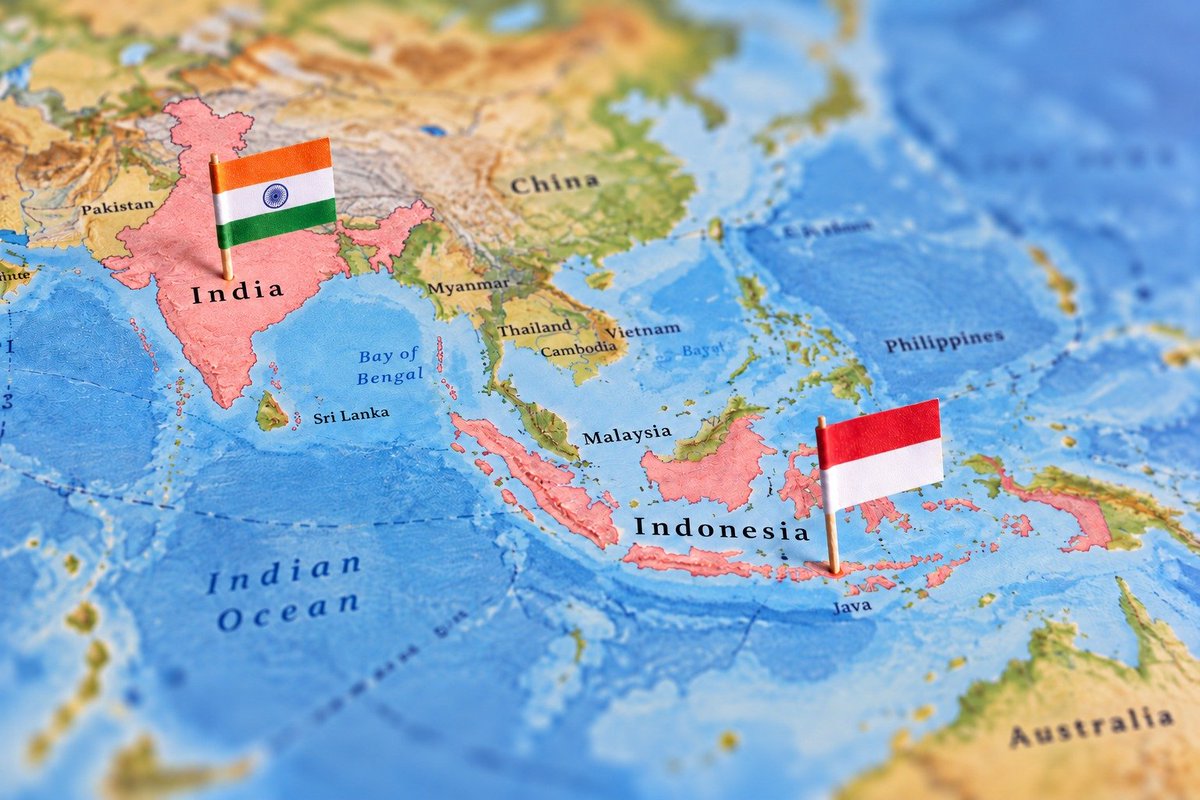
$2.5B in value is exposed to payment inefficiencies across 5 ASEAN countries every year.
to most of the outside world, these countries look like one trade corridor.
but the money still moves through fragmented systems.
businesses have to deal with:
> 3–8% in FX and payment costs
> different compliance rules in each country
> settlement taking up to 14 days
we’re working on this at Stableyard: connecting money movement across these countries while giving businesses local ways to pay and get paid.
coming soon. DM for early access.
We have integrated @stableyardfi into MoneyMoves.
Stableyard provides stablecoin payment infrastructure that makes it easier to move stablecoins across different chains and payment rails.
For MoneyMoves, this means we can support more assets from more chains and give users more ways to receive and move crypto directly within MoneyMoves.
It also gives us a stronger foundation as we expand our B2B and B2B2C infrastructure.
More assets. More chains. More ways to move money.
Busting 5 Stablecoin Payment Myths
that are costing businesses money:
myth 1: you need to become a crypto business.
fact: you don’t. stablecoins can work quietly underneath while your work with your existing currencies.
myth 2: your team needs to understand chains, gas & crypto.
fact: the infrastructure handles the wallets, chains & gas underneath.
myth 3: customers & suppliers must accept stablecoins.
fact: they can pay using the methods they already use.
myth4: suppliers need crypto wallets.
fact: they can receive local currency in their bank accounts.
myth 5: stablecoin payments are completely free.
fact: they still involve conversion, compliance and payout costs, but fewer middlemen can mean lower fees and faster settlement.
in some high-cost corridors, moving $10,000 can cost $400–$700.
businesses don’t need to adopt crypto.
their payment infrastructure just needs to work better.
that’s what we’re building at @stableyard.
pay globally. settle locally
if you wanna know more, let's chat
https://t.co/3zVH03cL6f