A detailed 4 min that explains complete BESS industry in detail and how money flows in this value chain.
Could BESS be the next growth frontier?
Disclaimer - Not a recommendation to buy/sell
@Pavan_07goyal Big players play the game to suck the money of retail investors. They have long term survival capacity . I hope they are not sucking SIP money.
US military picked 5 companies to build small nuclear reactors at 5 army bases in America
Westinghouse, General Atomics, BWXT, Radiant, and Antares will receive up to $2.2 billion over next 5 years. First reactor should be working by September 2028. Eventually more than 20 such reactors are planned for military sites.
Companies working on nuclear energy startups raised $6.2 billion worldwide in 2025 that was 93 companies, and most of them were American. In first half of 2026, another $4.5 billion went to 81 companies.
India put ₹20,000 crore aside for its small reactor program, but spread over many years. In US, Westinghouse built microreactor that can run 8 years without needing new fuel and produces 5 MW of power. Radiant built one that delivers 1.2 MW.
Daratha Atomics recently became first Indian startup working on microreactor design
India wants 5 small nuclear reactors by 2033 and 100 GW nuclear capacity by 2047. Right now India has only 8.78 GW, built over 6 decades.
Getting to 100 GW means adding 91 GW in 21 years. US Army expects its first microreactor working within 2 years of picking companies. India opened space to private firms in 2020. Within 4 years, Skyroot and Agnikul attempted rocket launches.
Nuclear can move at similar speed if new laws pass and private money enters quickly
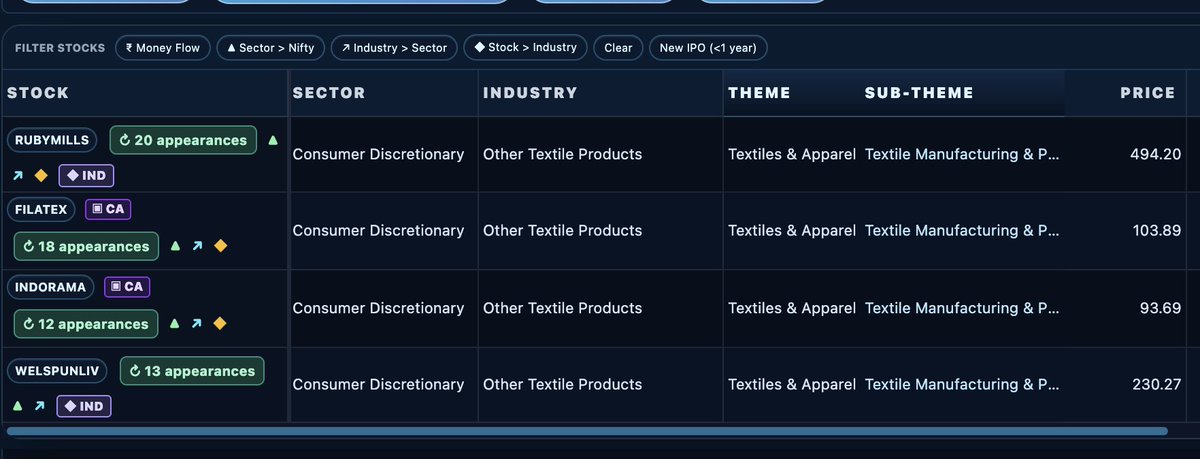
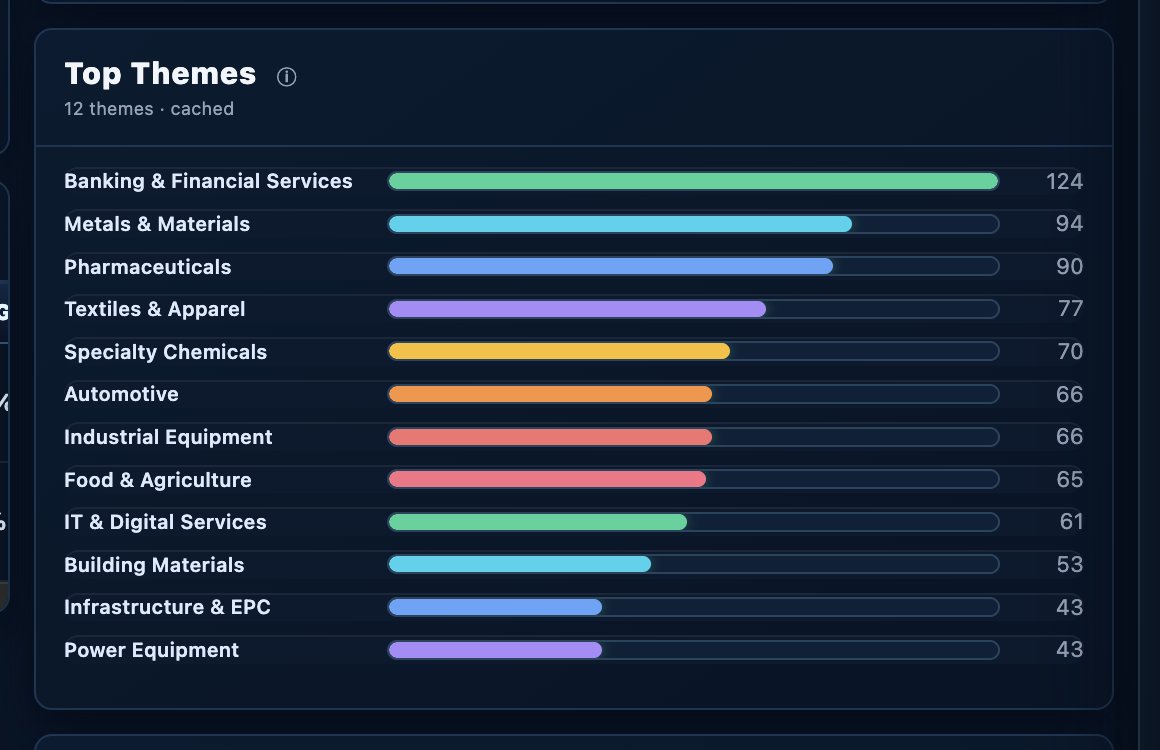
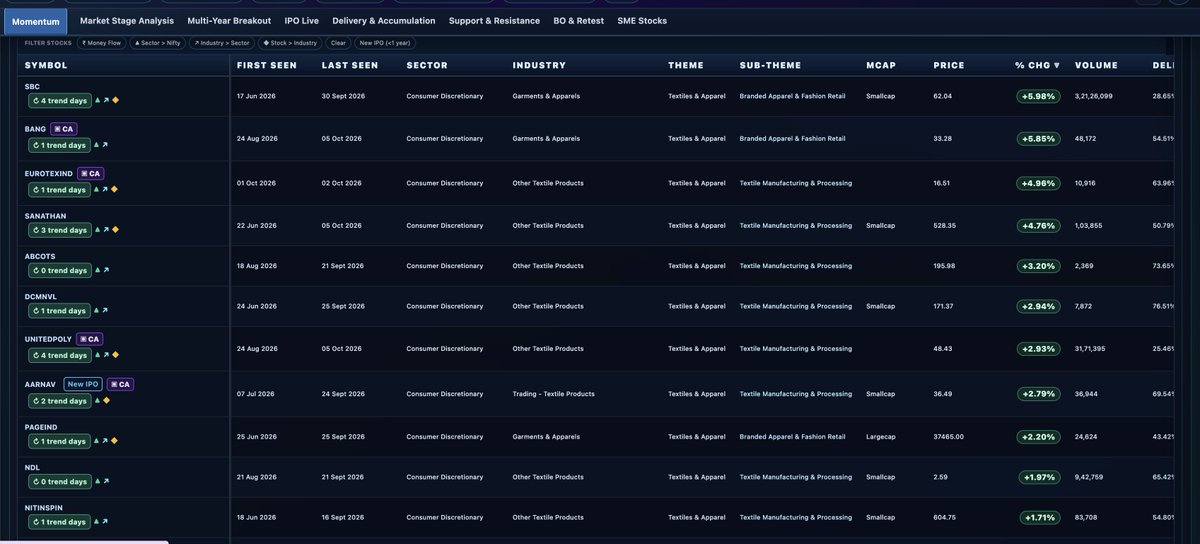
After Pharma and Industrial Products, I am now closely watching the next possible sector rotation:
Textiles & Apparel 👀
This theme is slowly moving up in my dashboard’s Top Themes list.
Few textile stocks have already started hitting new highs, while a few others are showing early reversals from lower levels.
This is how sector rotation usually begins.
First, only a few strong names move.
Then the theme starts expanding.
Then delivery, volume, and price action begin confirming participation.
Why Textiles & Apparel looks interesting now?
✅ India’s textile and apparel exports are improving.
Exports touched around ₹3.25 lakh crore in FY26.
✅ Ready-made garments, man-made textiles, cotton textiles, and apparel exports continue to remain key growth areas.
✅ Government support is strong through PM MITRA Parks, PLI, RoSCTL, RoDTEP, and export-promotion schemes.
✅ PM MITRA Parks can create a strong integrated textile ecosystem across multiple states.
✅ India-UK CETA, EU trade opportunities, and market diversification can support export-oriented textile companies.
✅ Cotton duty exemption and MMF input support can help improve competitiveness for textile manufacturers.
✅ On charts, many textile names are trying to come out of accumulation, move above key moving averages, and show better delivery participation.
So, for me, this is one theme to keep monitoring closely.
Pharma already gave a massive move.
Industrial Products also performed well.
Now Textiles & Apparel looks like a sector where early momentum + delivery + sector breadth + fundamental triggers are slowly aligning.
Keep this theme on your radar. 📌
#Textiles #Apparel #SectorRotation #StockMarket #Investing #KenshoDashboard
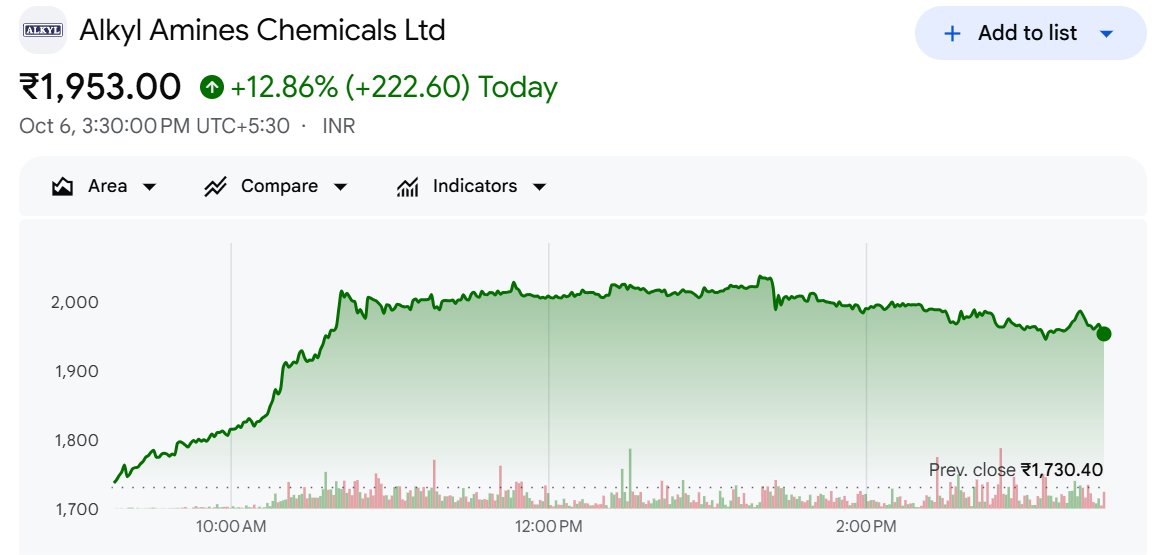
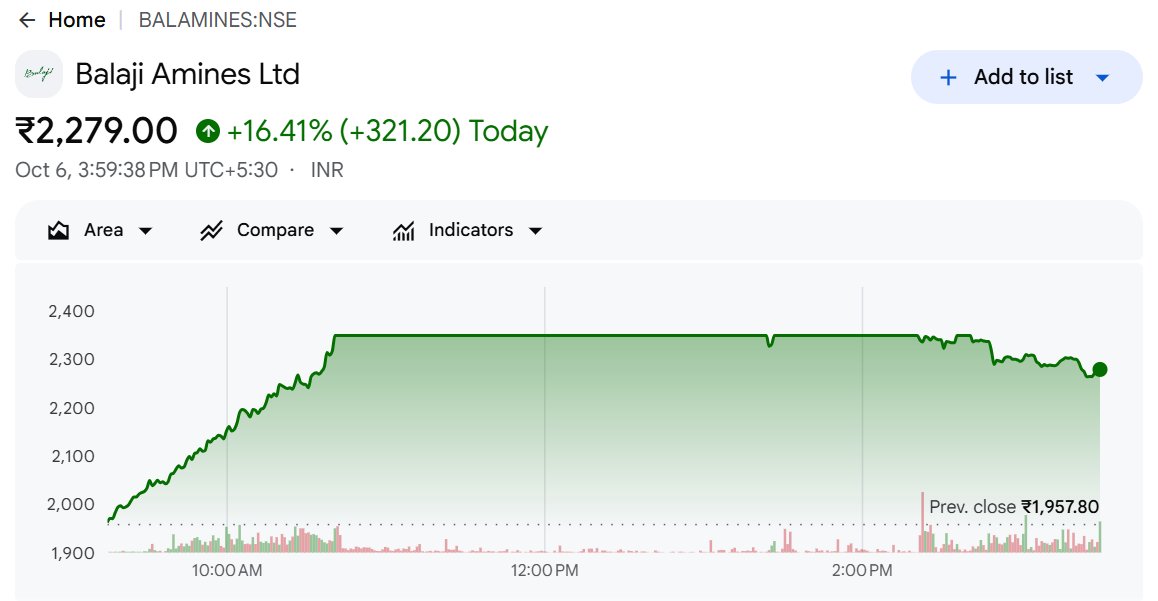
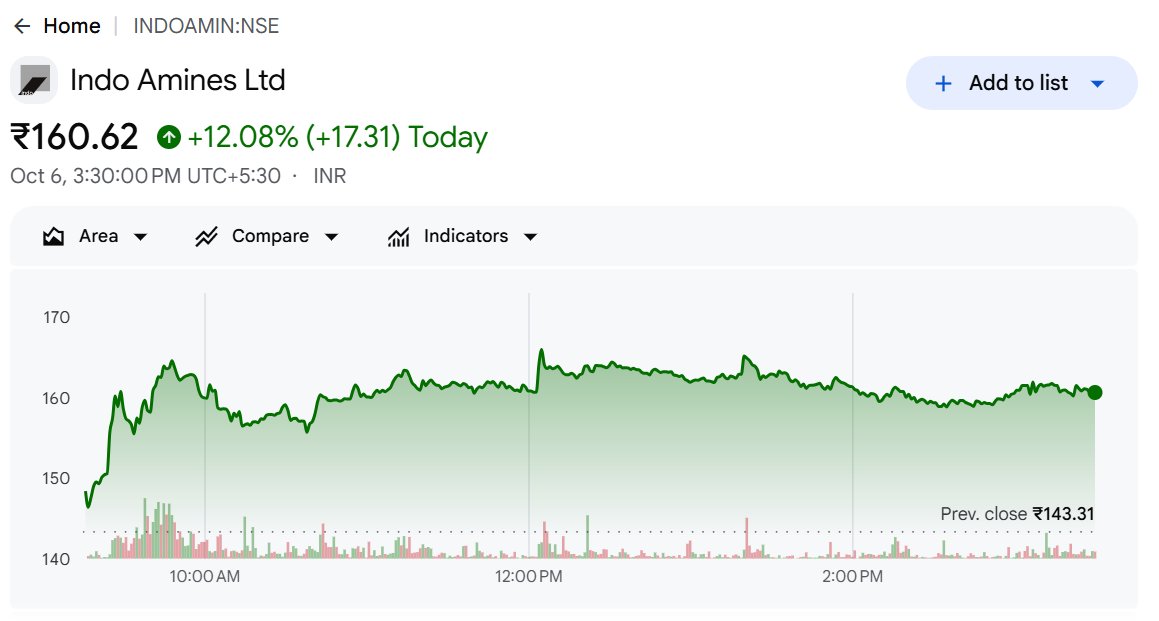
Why India's Amines Industry Is Suddenly Interesting — And Why Today's Rally Needs a Closer Look | Detailed
Amines are not a glamorous part of the chemical industry.
But they sit quietly inside some very important products - from pharmaceuticals and agrochemicals to polyurethane foams, water treatment and specialty chemicals.
And this week, the sector suddenly came into focus after the US started trade proceedings against certain amine compounds imported from China.
The market's immediate interpretation was simple:
China could become less competitive → Indian manufacturers could gain share.
But the real story is more nuanced.
First, what exactly are amines?
Think of amines as chemical building blocks.
They are used either directly in products or as catalysts that help other chemicals react in the right way.
One interesting application is polyurethane (PU).
PU is used in things like insulation, refrigerators, construction materials, mattresses, automobile components and spray foams.
Certain amines act as catalysts that control how the polyurethane reaction takes place.
So these chemicals may be small in quantity, but they can be critical to the manufacturing process.
Why is China suddenly relevant?
US producers have initiated anti-dumping and countervailing-duty proceedings against certain Chinese amine compounds.
The important word is “certain.”
This is NOT a blanket action against every amine exported from China.
The proposed scope is product-specific, based on chemical characteristics and specifications.
That distinction matters enormously for investors.
A headline saying “US imposes duties on Chinese amines” could make the entire Indian amines sector look like an immediate beneficiary.
But actual earnings benefit depends on:
Which products are covered → Who manufactures them in India → Existing US sales → Available capacity → Customer approvals → Incremental orders.
So who could benefit?
The obvious names being discussed are:
Balaji Amines, Alkyl Amines and Indo Amines.
Balaji and Alkyl are major Indian amines players, so investors are naturally extrapolating a China-substitution opportunity.
But there is an important reality check.
The US proceedings do not automatically mean these companies will receive large new orders.
At this stage, the earnings impact is not established.
Indo Amines is particularly interesting because its product portfolio includes polyurethane catalysts such as Bis-DAPA, DMDPTA and DMDEE. That gives it a more direct product-level connection to the PU catalyst opportunity.
But even here, we don't yet know the exact US revenue exposure, capacity available for exports or how much of its portfolio falls within the final legal scope.
This is where investors need to be careful
The market often jumps from:
Trade action → China substitution → Indian capacity → higher earnings.
There are several steps missing in between.
The actual chain is:
US trade case
↓
Final product scope
↓
Duties actually imposed
↓
Chinese competitiveness changes
↓
US customers seek alternatives
↓
Indian suppliers qualify
↓
Orders increase
↓
Capacity utilisation rises
↓
Margins improve
We're currently much closer to the beginning of that chain.
So today's stock-market reaction should be treated as a potential structural catalyst, not yet as a confirmed earnings upgrade.
What makes the theme interesting beyond today's rally?
The larger structural story is China's dominance in chemicals versus India's opportunity to become an alternative manufacturing base.
If Western customers increasingly want:
China + 1
then Indian specialty-chemical companies with the right products, quality certifications, manufacturing capability and customer relationships can potentially capture incremental volumes.
But this will not happen simply because a tariff is announced.
What should investors watch now?
For the amines companies, I would focus on five things:
1. Exact product overlap - Which Indian products actually fall inside the US case?
2. US revenue exposure - How much are companies already selling into the US?
3. Capacity availability - Can they take additional orders without major capex?
4. Customer qualification - Are existing Chinese customers actually approaching Indian suppliers?
5. Realisation and margins - Is China substitution creating sustainable pricing power—or simply more volume?
The bigger investment lesson
Today's rally is interesting.
But the opportunity is not the headline.
The opportunity, if it develops, will come from actual product substitution and incremental volumes.
That's why I would not treat every Indian amines company as an automatic beneficiary.
The next few months should tell us much more.
US trade action → product-level overlap → customer enquiries → orders → utilisation → earnings.
Until that chain starts becoming visible, the right approach is to separate sector excitement from company-level fundamentals.
Because in specialty chemicals, being in the right industry is not enough.
You need to be making the right molecule, for the right customer, at the right cost.
#Amines #SpecialtyChemicals #BalajiAmines #AlkylAmines #IndoAmines #Chemicals #Investing
Proxy of BESS🔖🔖🔖
✅ Battery chemicals company
- Acutaas chemical
- Sudeep pharma
- HSCL
- Neogen chemical
-Tatva chintan
-GFL & Many more
✅ power equipment & EPC company
- Quality power equipment
-Hitachi energy
-kec international
-siemens engineering
-kalpatru project
- T& D Power
- Tata Power
-JSW energy
-SPML infra & Many more
✅ Battery company
- Amar Raja battery
-exide industry & many more
✅ Solar pannel manufacturing company
- Waaree energies - Biggest player
✅ Wire & Cable company
- Havells
- Polycab & Many more
✅ Transmission company
- Advait energy
-adani energy
-powegrid & Many more
Dis- only for study purpose
#HFCL#equity #
Mgmt raised full-year top-line growth guidance to minimum 60% over FY26 (up from 40% guided earlier).
Targeting defense revenue of ₹500 Cr in current year, ₹1,500 Cr next year, and ₹4,000-5,000 Cr by FY30.
Board approved ₹1,250 Cr capex for 600 MT preform capacity by Oct 2028. OF capacity expanding to 34M fkm by Dec 2026 and 43M fkm by Jul 2028; OFC capacity to 43M fkm by Dec 2026.