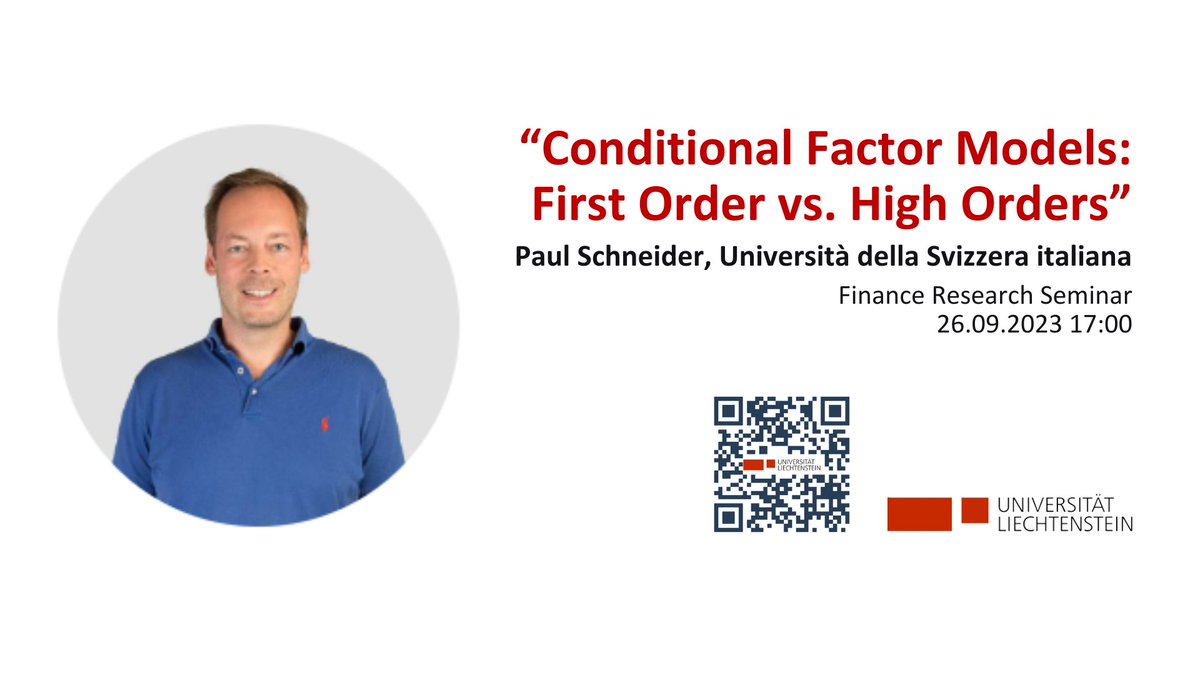
Tomorrow, Paul Schneider from
@USI_university will present his paper "Conditional Factor Models: First Order vs. Higher Orders" (joint work with Mirela Sandulescu and Michael Weber) in our #financeresearchseminar at @uni_li at 17:00 in S2! You are welcome to join!!
Excited to be in beautiful San Antonio to connect and exchange ideas with fellow deans about the future of education in the @AACSB community #AACSBDeans
@mdancho84@hadleywickham Hi @mdancho84 it works flawlessly for me. But what happened to me before is, that the server gets you blacklisted really quick for trying too many times.
@hadleywickham Cryptocurrency data on https://t.co/BxdKVWgglA is such a bugger, especially for bitcoin the "load more" loop is almost infinite. Note that this can be scraped in a different way, as is made available in my crypto2-package.
Do/are you:
-often use Fama-French Asset Pricing datasets?
-bother bay having to manually download those files?
-mind meddling with their complicated structure?
If *yes* use my free R-package *FFdownload* (available on #cran and #github)
Tomorrow, Prof. Dr. Raimond Maurer from @goetheuni will present his paper "Life-Cycle Portfolio Choice with Stock Market Loss Framing: Explaining the empirical evidence" in our #financeresearchseminar at @uni_li at 17:00 in HS5! You are welcome to join!!