Interesting how HYBE AMERICA, the North American subsidiary of South Korean entertainment giant HYBE Corp, is getting the shares of Dunamu, crypto firm currently operating Upbit through in-kind contribution. 2.47% may not seem significant but still.
Lot of mediation efforts (Saudi, UAE, and Qatar) for “temporarily” opening the Strait of Hormuz in exchange for one time payments to the Iranians.
How does this resolve anything?
This seemingly trivial reform will have significant implications for biotech firms—including 차바이오텍 (085660), 네이처셀 (007390), 박셀바이오 (323990), and 오가노이드사이언스 (476040). This isn’t a recommendation to buy; the risks are high, but it will be worth reading into.
South Korea is classifying certain cultured autologous immune cell therapies as “low risk”. Once safety is proved, providers may apply for treatment-plan review without first completing a separate clinical research study. Gonna be quite a news for some biotech firms. 🧬🇰🇷
Just for everyone’s knowledge, SK HYNIX ($SKHY) explained how the “special dividend” from the profit made from sale of Kioxia shares is not confirmed yet.
(Source: https://t.co/aaFDUZtiie)
Perhaps. I mean, I saw how the futures market was acting strangely one day. The Nasdaq and SKHY was going down while KOSPI 200 overnight futures went positive very briefly two days ago.
Though, be careful when using the one wish willow.
어제 장을 보면 특이사항이 하나 있는데
디램 > 반도체> 나스닥> 에센피
순으로 장이 좋았다는 겁니다
제가 언제올린건지는 확실하지 않은데 한 한달전쯤애
에센피>나스닥>반도체>디램 순으로 장이 좋다고 올렸고
그게 사실 하락의 전조증상이었습니다
가장 큰 하락은 디램이
저저번주에 이미 끝났고 (물론 목요일에 저점이 나오긴했지만)
반도체가 그저께 끝난것이 아닐까 추측하고 있습니다
저는 다음주에 하락이 한번 더 있을수 있다고 생각하는데
반도체들은 저점을 깰수도 있겠지만 하락폭이 지수들보다 크지 않고 회복속도는 더 빠른 형태가 될거라고 생각합니다
그리고 그게 상승의 전조증상이라고 생각합니다
상승이 시작되면 디램 > 반도체> 나스닥> 에센피 이 순서로 가장 빠르게 오를거라고 생각합니다
국장도 내릴때 자비없이 내려서 그렇지 오를때도 항상 미장 반도체보다 상승폭은 컸습니다
저번 여름 최대 상승폭이 국장이 30프로때 후반
미장에 20프로대 후반입니다
(지금 정확한 수치는 기억에서 삭제됨-_-)
저는 그게 이번에도 반복될거라고 생각합니다😉
가장 힘든 시절은 거의 다 지나가고 있습니다
다음주에 하락이 있다면 그게 마지막이 아닐까 생각합니다!
$LPTH — 𝗔𝗚𝗚𝗥𝗘𝗦𝗦𝗜𝗩𝗘 𝗘𝗫𝗣𝗔𝗡𝗦𝗜𝗢𝗡. 𝗜𝗦 𝗚𝗢𝗩𝗘𝗥𝗡𝗠𝗘𝗡𝗧 𝗙𝗨𝗡𝗗𝗜𝗡𝗚 𝗢𝗡 𝗧𝗛𝗘 𝗛𝗢𝗥𝗜𝗭𝗢𝗡?
Something I've been thinking about since @skrubin's recent interview with @RADHardTech.
Sam outlined substantial expansion plans across virtually every major LightPath location:
• Orlando: An entire wing dedicated to glass manufacturing, along with additional clean-room and camera assembly capacity.
• Texas: Plans for a significantly larger 60,000–90,000-square-foot facility focused on glass and related products.
• New Hampshire: Additional manufacturing space to accommodate growing G5 camera production.
• Latvia: A move into a larger facility as optical manufacturing, coatings and assembly capabilities expand.
These aren't simply facility expansions.
LightPath is redesigning production flows, introducing automation, improving manufacturing efficiency and preparing for significantly higher production volumes.
All of that requires substantial capital, equipment, personnel and long-term planning.
Which brings me to the real question:
Is LightPath preparing to finance this entire expansion program with its own capital, or could management be moving forward with the expectation that substantial government financing is on the horizon?
Sam has previously discussed potential government financial support, including conversations with the Office of Strategic Capital and other agencies. The possibilities he has referenced include grants, loans or even a direct government equity investment.
Those are three very different financing mechanisms, but each could potentially accelerate LightPath's manufacturing expansion while preserving some of the company's existing capital.
HERE'S WHAT STOOD OUT EVEN MORE.
In that same interview, Sam revealed that LightPath recently walked away from two relatively large acquisition opportunities because management considered the valuations too expensive. He also indicated that other acquisition discussions remain active, including with companies LightPath has evaluated for years.
With approximately $93 million in cash at fiscal year-end, management has meaningful financial flexibility. Yet Sam emphasized that they're not interested in spending money simply because they have it.
That reflects financial discipline but it also raises another question.
How does management intend to finance such an ambitious expansion program across four locations? Could anticipated government financing be part of that equation?
That doesn't mean government funding is assured. But the combination of aggressive expansion, substantial cash reserves and management's emphasis on financial discipline makes the question particularly intriguing.
NOW CONSIDER THE BROADER BACKDROP.
The Pentagon is aggressively pursuing domestic manufacturing capabilities, reducing dependence on foreign optical materials and strengthening the defense industrial base.
LightPath's BlackDiamond technology, domestic glass manufacturing capabilities and expanding infrared camera production appear particularly well aligned with those priorities.
And consider the timing.
Management is simultaneously discussing major expansions across four locations while pursuing opportunities in missile defense, counter-UAS, infrared imaging and other defense applications.
Could LightPath already be further along in government funding discussions than shareholders realize?
Or does management simply have sufficient confidence in its growing order pipeline to justify committing significant amounts of its own capital?
Perhaps both.
To be clear, I'm not suggesting government funding has been approved or that an announcement is imminent. This is speculation on my part.
But I find it difficult to ignore the magnitude of these expansion plans, particularly when viewed alongside the government's increasing emphasis on domestic defense manufacturing.
MY TAKEAWAY
LightPath isn't building infrastructure to support yesterday's revenue levels. Management appears to be preparing for a business substantially larger than what exists today.
Four locations. Substantial manufacturing expansion. A management team emphasizing financial discipline. And ongoing discussions about potential government financing.
Perhaps these developments are entirely independent. But I can't help wondering whether they're more closely connected than shareholders realize. Could a meaningful government funding announcement be closer than the market expects?
#LPTH #Pentagon #DefenseFunding #CriticalMinerals #MadeInAmerica #NationalSecurity
The fact that the current government stopped the “National Pension Service of Korea” from selling some during the summer while pressing investment firms to create leveraged ETFs adds flavor to the popcorn. 🍿
I mean, the individual investors also demanded such.
I am sorry, but the KOSPI is on the verge of crashing hard again, 3rd time this week, and there is a high chance that tomorrow will be Black Friday in Korea if a miracle does not strike here
I don’t care if it is 200 or 2000 days moving average that you are lookin at. Data centers gobbled up more debt in real terms compared to the mortgage crisis in 2008… For Christ sake.
https://t.co/gxH43nmgm5
Sometimes, Korean asset managers launch ETFs focused on stocks or themes that have already surged.
It is as though someone’s trying to do a pump-and-dump with ETFs. Maybe I’m paranoid, but it does feel that way too often.
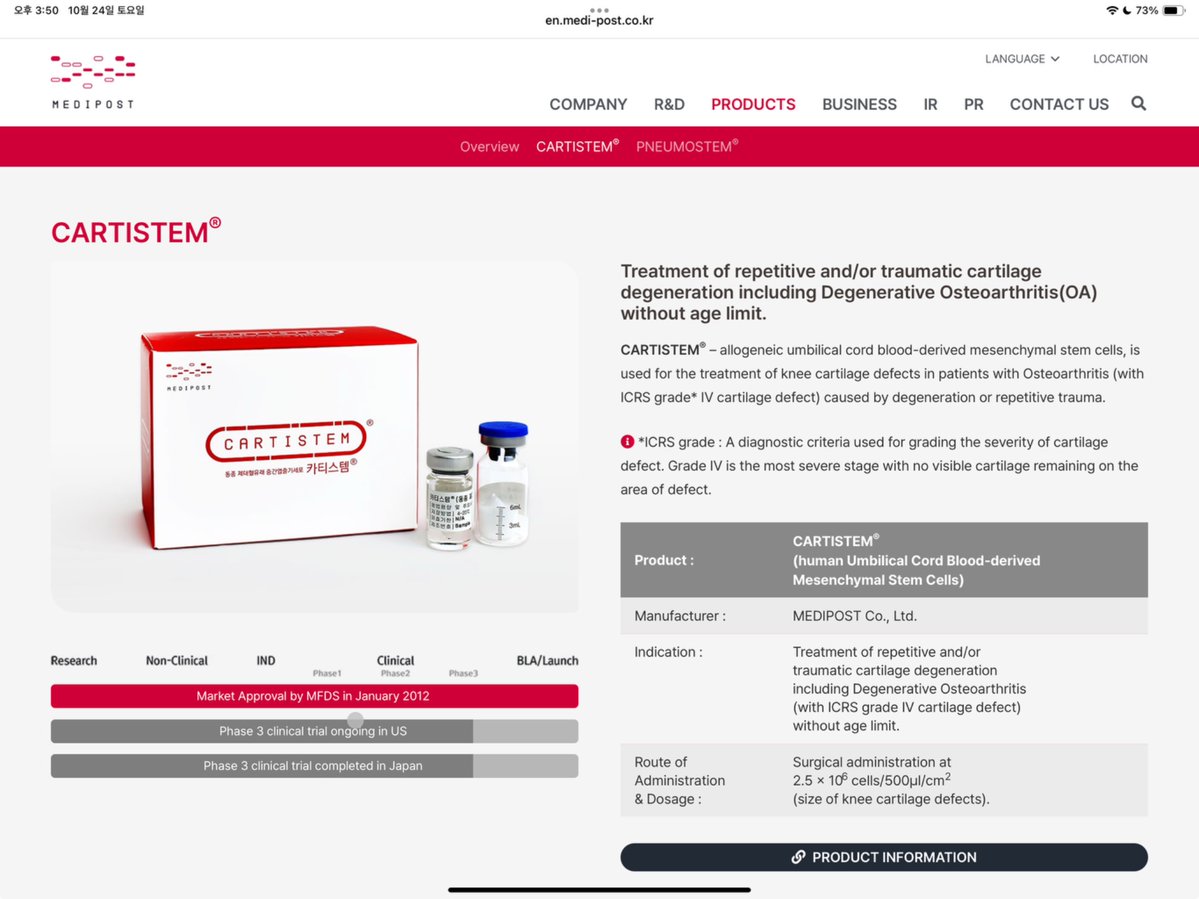
Remember how Korea Investment & Securities calculated the DCF based NPV of profit that Medipost’s allogeneic, cord blood-derived stem cell therapy for knee cartilage defects generated from Japan to be 513 million USD, yet the company valuation is 264 million…
South Korea is classifying certain cultured autologous immune cell therapies as “low risk”. Once safety is proved, providers may apply for treatment-plan review without first completing a separate clinical research study. Gonna be quite a news for some biotech firms. 🧬🇰🇷