My life is all about Traveling ✈️🧳hiking🏔️🥾🎒, photography 📸, life partner & of course swing trading 💲. I post my opinions which is not financial advice.
@QQQ275Soon Hmmm 🤔 if you liked it at a higher price, why would you NOT like it now? DCA next time instead of going all in? Good luck on your next investment though. $IREN
https://t.co/7DIR7lZRbp
Lets not forget the partnership announcement in May with $NVDA . They have the option to exercise to buy up to 30 million worth of shares at $70 a share for 5 years. In my opinion that's super bullish. $IREN
🚨 $IREN: THE INFRASTRUCTURE STORY IS AHEAD OF THE SOFTWARE STORY
A bad first build does not mean a bad final product.
I was finishing my bagel and coffee while I saw $IREN bulls and bears fighting.
Did you all see how SemiAnalysis report is treating one weak part of $IREN’s current cloud product like it invalidates the whole company? 😂
Well, it doesn’t.
The Canadian GPU cloud has real issues and yes, we should take them seriously. But Childress, Sweetwater, $MSFT and $NVDA are different and they should be judged separately.
1. WHAT CLUSTERMAX ACTUALLY TESTED
ClusterMAX 3.0 reviewed 77 GPU cloud providers and tracks 323 across the wider market. Only 19 received a medallion rating, with $CRWV and $NBIS near the top. IREN landed near the bottom.
But the important thing is ClusterMAX is measuring the quality of the managed GPU cloud experience. It is not measuring IREN’s power position, land, data center buildout, long term contracts or ability to deliver dedicated infrastructure to hyperscalers.
$IREN was also not tested under the same standard protocol as the top providers. Kent Draper said IREN did not have a live managed Slurm or Kubernetes cluster available to hand SemiAnalysis, so the assessment relied more heavily on reseller access and customer feedback.
It does not make the criticism irrelevant but it does make the comparison less clean. A $CRWV score based on a standardized managed cluster test is not exactly the same thing as an IREN score built partly from reseller access and customer anecdotes.
So the ClusterMAX result tells us something important about IREN’s live cloud product. It does not tell us everything about IREN.
2. THE CANADIAN OPERATING ISSUES ARE REAL
Prince George, Mackenzie and Canal Flats were originally built around Bitcoin mining. An ASIC hall and a serious managed AI cloud are not the same thing operationally.
So the SemiAnalysis complaints around outages, storage, networking, XIDs and production upgrades are believable in that context, especially since IREN itself has said the software and managed services side is still being built out.
There is also a harder technical point from the older ClusterMAX work. SemiAnalysis found an NCCL performance issue tied to ACS being enabled on the PCIe path which forced traffic through the CPU root complex instead of allowing a cleaner GPU to NIC path.
This issue is fixable but the bigger concern was that $IREN could not quickly retest and prove the fix at scale.
So yes, I think the Canadian criticism is fair. I just would not extend it beyond the Canadian cloud product.
3. CHILDRESS IS NOT PRINCE GEORGE
Now, Horizon 1 at Childress is a purpose built 50 MW liquid cooled AI deployment running GB300 NVL72. $MSFT accepted it on August 13 and $NVDA gave it Exemplar Cloud status after testing it.
It does not prove five years of perfect uptime. It does not prove the software layer is finished and it surely does not guarantee Horizons 2–4 arrive exactly on schedule.
But it does prove something important. $IREN can build and deliver a very different class of AI infrastructure than the converted Canadian mining sites people are criticizing.
IREN also said Horizon 2 was commissioning and Horizons 3–4 were in late stage construction for Q4 2026.
So I would not use British Columbia as a verdict on Texas and I also would not use one accepted 50 MW hall to pretend the Canadian issues never happened.
They are different assets, built differently and they should be judged separately.
4. THE $MSFT CONTRACT VALIDATES THE INFRASTRUCTURE SIDE
The Microsoft deal is five years and $9.7B across four 50 MW Horizon deployments and Horizon 1 has already been delivered and accepted.
This is major validation of IREN’s ability to build and deliver infrastructure.
IREN can be very good at giving a hyperscaler the power, cooling, hardware and dedicated capacity it needs while still being weaker at running a polished multi tenant managed cloud for everyone else.
Those are two different businesses. So a weak ClusterMAX result and a very valuable Microsoft contract can absolutely exist at the same time.
IREN’s infrastructure business is further ahead than its managed cloud business.
5. THE $NVDA DEAL MATTERS FOR MORE THAN THE $2.1B NUMBER
NVIDIA and IREN announced a strategic partnership that could support up to 5 GW of AI infrastructure over time.
As part of that, $NVDA got the right to buy up to 30 million IREN shares at $70 over five years, which would be worth as much as $2.1B if exercised.
That does not mean NVIDIA already handed IREN $2.1B in cash. It is an equity right.
But I also think people miss the bigger signal when they stop there.
NVIDIA is aligning itself with IREN’s future infrastructure buildout at multi gigawatt scale.
So yes, do not treat the $2.1B like cash already sitting on IREN’s balance sheet.
But also do not act like the partnership is meaningless because the equity has not been exercised. The strategic validation is already there.
6. THE SOFTWARE LAYER IS WHERE SEMIANALYSIS HAS ITS BEST POINT
$IREN’s FY2026 10-K says it owns and operates all three layers of the AI Cloud Services stack including managed services and enterprise support. It also says they offer both bare metal and managed cloud.
Now put that next to August.
$IREN bought Mirantis because they clearly knew the software side still needed work. Orchestration, monitoring, deployment, managed services is exactly the stuff Mirantis is there to improve and even IREN’s own filing says the integration is still ongoing.
So yeah, I get why SemiAnalysis is pushing back on the wording.
The 10-K makes the software layer sound further along than it really is today. In reality, IREN is still building a lot of that out.
This is a fair criticism.
7. MIRANTIS IS THE PIECE THAT CAN CHANGE THE STORY
$IREN paid $544M for Mirantis and brought in around 580 people. You all can see where management knows the gap is.
IREN already has the land, power, data centers and GPUs. The difficult part is turning that into a proper managed cloud with orchestration, monitoring and support.
This is what Mirantis is supposed to fix. So the next test is whether $IREN can get a managed cluster live that a third party can actually test against $CRWV, $NBIS or Lambda.
1. $IREN deal with $NVDA is the very first software deal.
2. $IREN has never claimed to have “active managed services".
3. Instead of apologizing for misleading investors, SemiAnalysis is repeating the same blatant lie once again.
Many people are saying we're in a bubble.
Here's what the 2000 and 2007 tops had in common. Different causes, same sequence:
1. Yields topped first
2. Stocks topped second
3. Commodities topped last
If something bigger is coming, this may be the order to watch.
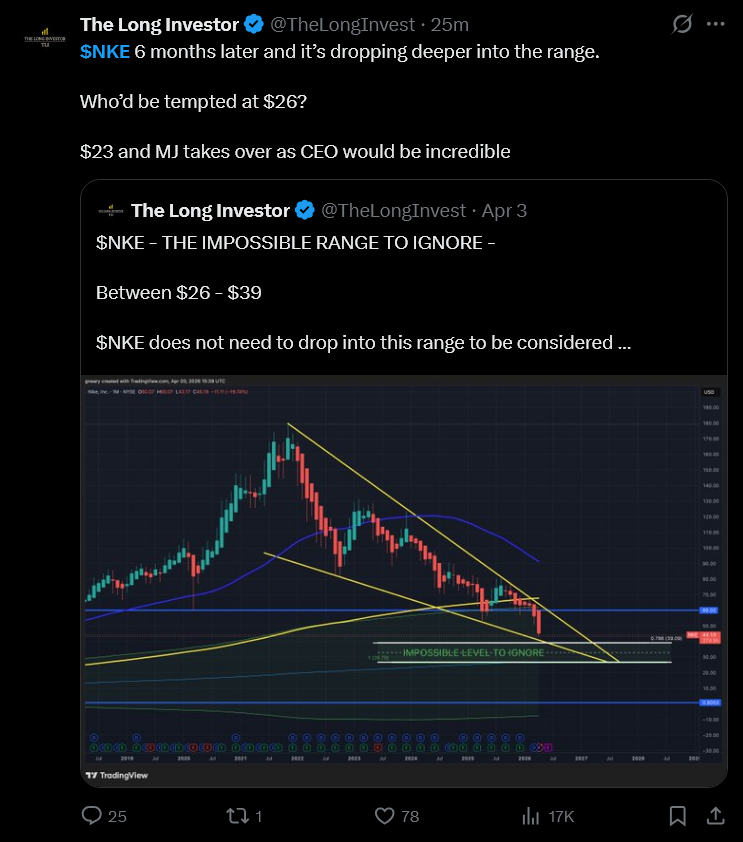
The Long Investor @TheLongInvest sharing stocks like $NVO $UNH and $NKE makes me wonder whether his name implies that he simply wants to turn his followers into long-term bag holders?
If these names would've bottomed, he would've claimed the fame for it.
If they go down further, which all of them are doing, he simply says "think long term" or "holding long term wins".
Pretty good strategy for always being "right" and luring people into the overpriced subscription where you get 3 charts a day.
I post 20+ charts a day, every day, for free.
@TheLongInvest You just can’t accept this and $NVO have been terrible calls… everyone gets it wrong sometimes and it’s alright. Be accountable and stay humble.