Central banks are likely buying way more gold than official figures suggest:
World central banks acquired +44 tonnes of gold in July, +158% above the pre-2022 average of +17 tonnes, according to Goldman Sachs.
This brings the 3-month average of purchases to +91 tonnes, near its highest since mid-2025.
By comparison, the 12-month moving average has oscillated between +50 and +60 tonnes over the last few months.
Meanwhile, official central bank purchases of gold stood at +23 tonnes in July, or 21 tonnes below actual levels.
Furthermore, official monthly purchases have not exceeded +60 tonnes in any month since November 2024, also representing a wide discrepancy.
Central bank gold demand may be much greater than official figures suggest.
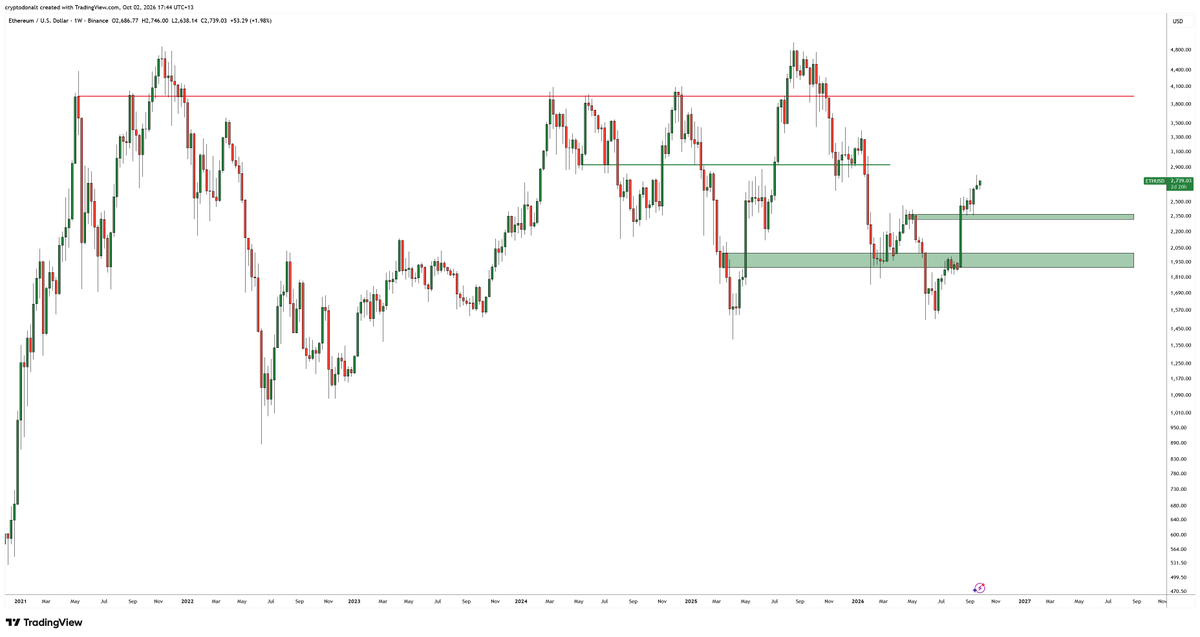
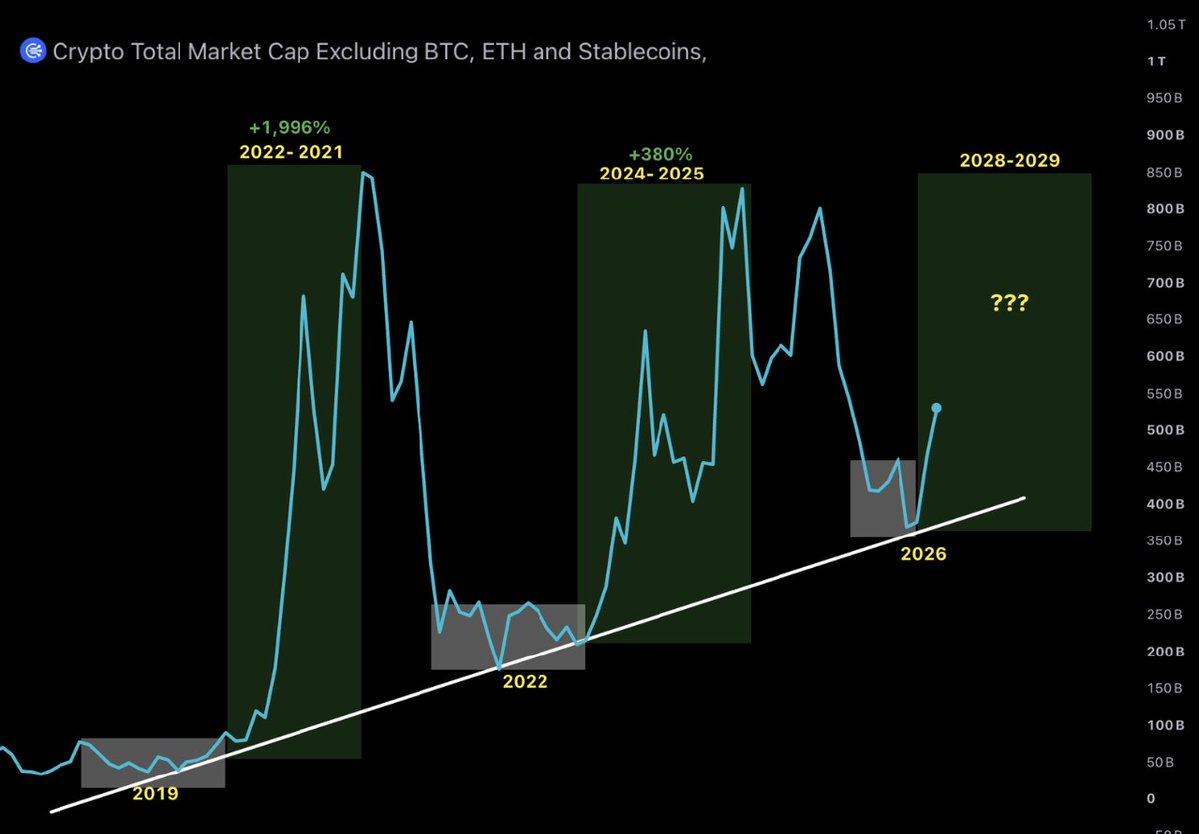
Altcoins are bouncing from important multi-year support levels.
Once Bitcoin confirms the bull-market trend and BTC dominance drops below 58%, altcoins could follow with a much bigger move.
$BTC is above all its key levels, which confirms a cycle bottom.
But that doesn't mean up-only.
IMO, Bitcoin will have an 8%-10% correction from here to flush out late longs.
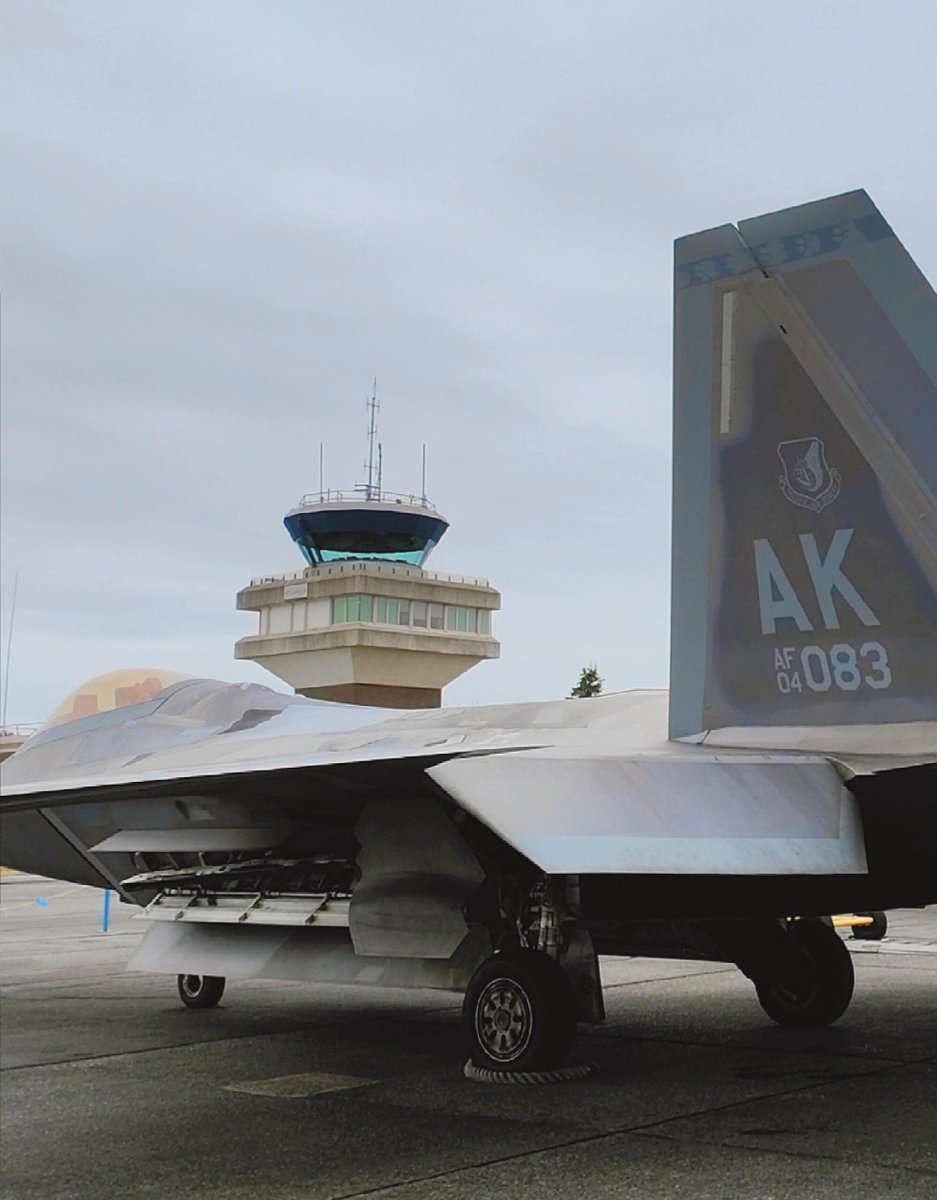
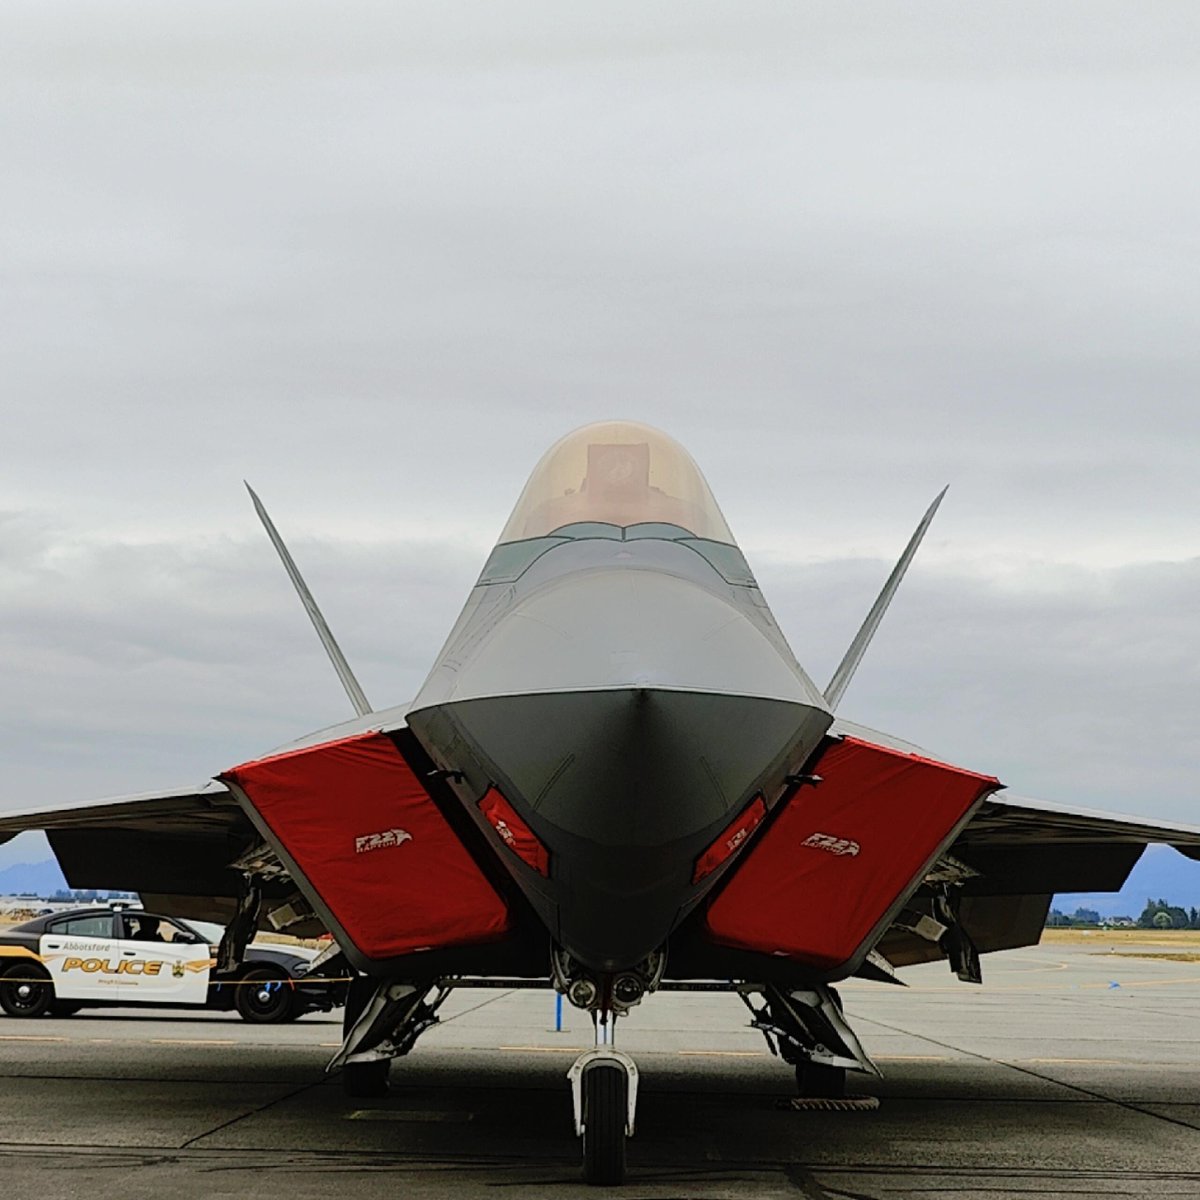
The Alaskan F-22 Raptor, even up close, possesses a striking, industrial, and brutal beauty; its massive control surfaces give it a Transformers-like feel.
The copper market is facing a severe supply squeeze:
The LME’s front-month copper spread surged to a $370 per ton premium on Friday, the widest one-month spread since the 2021 supply squeeze.
This means traders are paying a historic premium for copper available in the near term versus delivery a month later, signaling that physical supply is extremely tight.
At the same time, the widely followed cash-to-three-month spread rose to $434 per ton, also the highest since 2021, prompting the LME to tighten its market controls.
This comes as LME copper stockpiles have fallen for 42 consecutive days, the longest streak since 2014, to 204,975 tons, with nearly half of the remaining metal already scheduled for withdrawal.
All while traders and producers are redirecting copper to the US, where expectations of tariffs on refined copper are pushing prices above LME levels and creating arbitrage opportunities.
The supply crunch in the copper market is far from over.