Stripe acquired OpenRouter. Ramp launched Router.
Both are leaning into stablecoins.
Cloud, mobile, and APIs are now table stakes, not an investable category.
The next era of finance is something else. https://t.co/tSlI1xTKkT
Next week we’re co-hosting an event with @a16z and @typesafeai called ‘Jev and the Future of Fraud Fighting.’
When Jev came out a month ago, I tested it on an actual fraud incident at a Sardine customer. What I found shocked me:
- Jev outperformed LLMs in fraud applications and slightly beat traditional rules based approaches.
- Jev classified best at 93% recall, followed closely by the velocity rules our Data Analyst Agent proposed at 90%, with an LLM making the classification decision trailing at 62%.
After that test, I shared the results internally and we started incorporating Jev into the Sardine platform. I also reached out to the team at TypeSafe, the company behind Jev. I had to get to know them, and I’ve been incredibly impressed since.
I’m happy to share that Erik Spock Gafni, CTO of TypeSafe AI, will be joining me on a panel at this event to discuss Jev and where it fits into the future of fraud fighting.
Yoko Li from a16z will be moderating our discussion. More details on the event:
- November 4th, next Wednesday, from 5-8:30 pm
- In San Francisco’s Financial District
- Panel with myself, Erik, and Yoko
- Drinks and conversation to follow the panel
Claim your spot here: https://t.co/BuxLAAg9JC
My goal is to give risk teams weighing AI for approve-or-decline calls a straight read on what Jev looks like with real fraud running through it.
Meta's @Muse answers questions very differently from ChatGPT or Anthropic.
It cites more sources but uses far fewer words and tables, and doesn't try to ask a follow-up.
This short-form content is designed for dealing with tasks rather than continuing a conversation, and frankly, it's far less exhausting to read. This speaks to a really well designed AI experience and its so different from the base LLMs.
Great study by the AirOps team 👇
gg @alexandr_wang
@noyesclt Tempo is designed to solve for settlement friction
Cards solve for auths and liability, which is especially important for consumers in an age of scams IMO
Your agents shouldn’t need a new account and a credit card for every service they have to use.
@MPP enables them to discover services, get a price, and pay all in a single request flow. No separate API keys or billing for each provider.
@brendan_j_ryan from Tempo Labs explains:
“Why have you designed your organization in the way that you have, in a world where computers can think?” –@eglyman
“The best thing about AI is it's allowed us to look at every process and question it. And a lot of the benefit was just changing the process.” –@velez_david
Ramp is worth $60bn and 70% of its R&D team is working on products it hasn't released yet.
I sat down with @eglyman in New York to discus
Why he thinks of @tryramp as a productivity company more than fintech
The 7,000 pull requests their non-engineers wrote last quarter
The trust charter, stablecoins, and whether an AI agent would choose your business.
Full conversation 👇
00:00 Introduction
03:16 Is fintech dead? And why Ramp considers itself a productivity company
04:41 Why AI token costs are turning software into financial products
07:27 How Ramp's Inspect lets non engineers ship code using AI
11:51 Why AI is becoming the third major category of business spend
18:43 What justifies Ramp's valuation and its accelerating revenue growth
27:07 How AI is transforming employee productivity and customer support workflows
39:54 Why Ramp applied for an OCC national trust bank charter
43:15 How stablecoins enable faster cross border payments and protection against currency volatility
47:23 Will autonomous AI agents replace Ramp or choose its financial infrastructure?
51:01 The future of agentic companies and Ramp's mission to eliminate waste
Find the full conversation here on YouTube:
https://t.co/d3ERoLG2A3
Or wherever you get your podcasts.
And remember to subscribe at https://t.co/YwvwqgnocF if you want more like this
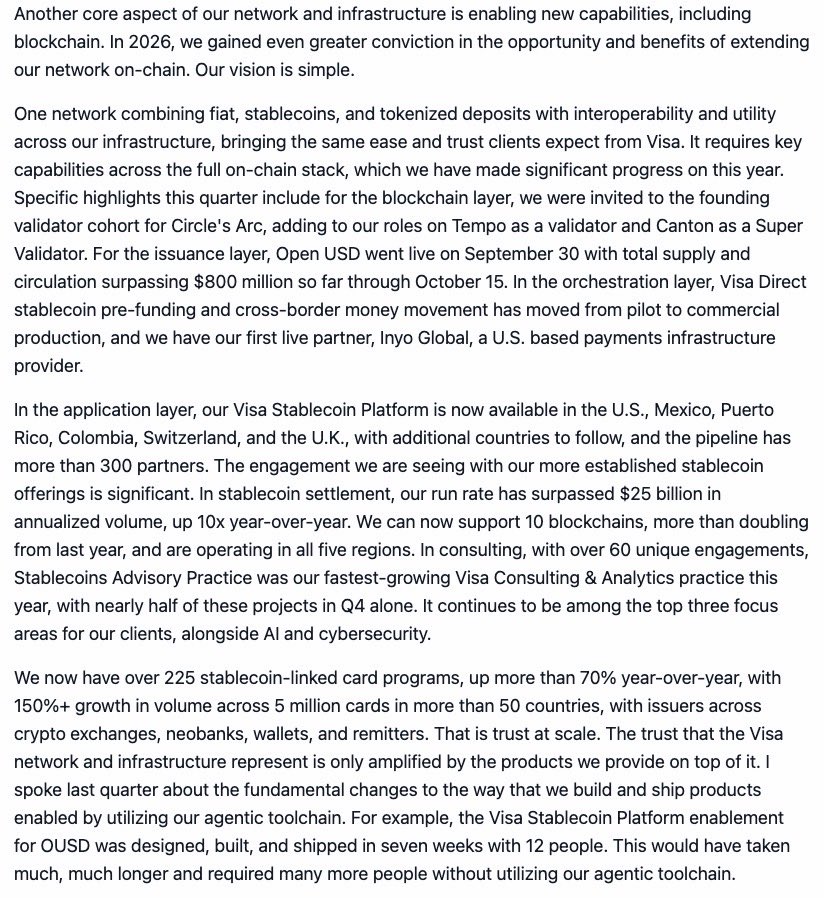
It’s an exciting time for Visa’s stablecoin business. Visa CEO Ryan McInerney shared some updates on our strategy and traction on yesterday’s earnings call.
For a decade, we've built credit for people the financial system couldn't see.
Now there's a new kind of thin-file borrower: the AI agent.
Here's my take👇 https://t.co/8lwpBamimL
1/ Stablecoins provide banks with an opportunity to grow deposits.
As businesses get paid in stablecoins, they'll move idle balances into tokenized deposits, which count as cash and support credit lines. Banks that offer them early win that business.
Deposit tokens vs stablecoins got framed as a fight. From where we're looking it looks more like a stack. Deposit tokens make good reserves, both for the banks and sensitive holders like corporate treasuries: they pay interest and stay inside the bank perimeter. Stablecoins make good bearer money: anyone can hold, no account needed.
Put one under the other and an issuer can rebalance reserves in code, at 3am on a Sunday, instead of through wires and cutoff times, leading to a better experience for everyone involved.
Instinct just gave AI agents a budget they can spend without asking you.
Each agent gets a stablecoin wallet, but the purchases themselves still run on card rails.
Here's how it works
1. You load a balance into the wallet
2. Set a per-purchase limit
3. Tell the agent what to buy, and it draws down from that balance.
The demo shows a user adding $700, asking for their favorite lunch every day for a week, then concert tickets.
Under the hood, each agent holds OUSD (a stablecoin) in a Privy wallet on Tempo. So you’d be forgiven for thinking the card schemes are cooked.
But actually, here's how it works for a $50 purchase:
- The agent initiates a card purchase against the user’s balance.
- Stripe sells $50 of stablecoin and converts it to dollars.
- The dollars fund a prepaid card account at Lead Bank.
- The purchase runs through Visa and the merchant gets paid the way it always does. The merchant needs no wallet.
It’s a card in all but name. The stablecoin step still buys three things.
1. The balance can earn yield for Stripe or its partners while it waits to be spent.
2. One balance can fund many cards, plus wire, ACH and stablecoin payments. A card only ever draws from that card’s balance.
3. Once enough users hold a stablecoin balance, agents can pay other agents or any stablecoin endpoint directly.
Cynics will say we can already do all of this, and they’ll be right. Banks and card networks are watching anyway, because a wallet competes with the account as the default place to hold a balance.
Everyday spending is the consumer wedge for AI. Cash App, Chime and Revolut peeled off everyday spend first and won the paycheck later. Consumer agents are starting in the same place.
Zuckerberg said during earnings that shopping is Muse’s most common use case, with an average purchase over $200.
A balance is the first step toward agents managing budgets, and then money more broadly.
We're heading to a world of everything agents.
With everything wallets.
And those wallets might find it easier to hold stables than fiat.
Give your Instinct a budget
Built with @Stripe and @link, we're launching Link balance in @instinct. You can now set a budget for your Instinct to make purchases on your behalf, and Instinct does the rest.
You choose how much money to add and set a limit for each purchase. Your Instinct can spend within those limits, without needing access to your credit card or asking for approval every time.
That means buying tickets as soon as the presale opens, picking up your size when the trail runners restock, or reordering your favorite coffee beans every other week.
Link balance is rolling out to Instinct users across the US starting today, with New York coming soon.
Ask your Instinct to set up Link balance and it’ll send you a link to get started.
I love the frame that brand marketing is arbitrage against performance marketing.
Because you can measure performance (pay-per-click), it's well-priced.
But if you do the math on how many people travel through an airport, and see the logo it works out better.
That's what @Revolut did 👇
Based. Not many founders/CEOs have the balls to do brand marketing. Most just live in a perpetual cycle of performance ads. @NStoronsky on @davidsenra’s podcast.
“If you’re a digital bank, you don’t have branches. People don’t see you physically, so they trust you less by definition compared to HSBC, Lloyds, JP Morgan Chase."
"So how do you build trust? In performance marketing you pay per impression, and there are a lot of spaces in the physical world you can buy that also produce impressions, at a much cheaper price. We bought almost 50% of all airports in Europe. Simple math. How many times a year people travel, how many times they’re in the airport, how many impressions we produce, how much it costs us. There is arbitrage to performance marketing.”
@jsfranklin221 Avoids you linking a prepaid card like apple cash.
You can spin up one time use cards, often higher auth rates / potentially lower fraud.
DAS LONDON:
Building The New Standard for Global Money Movement
with @zcabrams & @sytaylor
Wednesday Nov 11 in London.
Be there: https://t.co/w9Bk04BHuO
Instinct now lets you give your AI agent a balance to spend within limits.
That balance sits in stablecoins.
The purchase can still run through Visa.
But your bank should watch where you keep the money between purchases. https://t.co/zZYHeLEF8U