I’ve been trading for ~30 years.
First half: fully discretionary, living inside futures microstructure. It worked—until algos started exploiting the same patterns and reacting in microseconds. Edge decay was real.
So ~10 years ago I switched to systematic.
Now I run many uncorrelated strategies in parallel without babysitting screens all day. I wouldn’t go back.
My biggest unlock: reusability of know‐how.
When I finish a new system, I plug it into a ready workflow in minutes. It monitors itself; I move my brain to the next big thing.
Here’s the playbook I wish I had from day one:
- Framework (design once → reuse forever)
- Data → clean, feature, label.
- Hypothesis → simple, testable edges (breakouts, momentum, mean reversion).
- Validation → IS/OOS, realistic costs/slippage.
- Risk → position sizing, max heat, portfolio exposure caps.
- Deploy → automated orders, fail‐safes.
- Monitor → health dashboards, kill‐switch rules, mobile app.
- Iterate → new systems slot into the same pipeline.
Principles that compound:
- Many small, independent edges > one “genius” setup.
- Process beats prediction.
- Shipping beats perfecting.
Discretionary taught me markets. Systems gave me scale.
Last week was a reminder of how wild long mean reversion on individual stocks can be.
What happens when you trade it on an index instead?
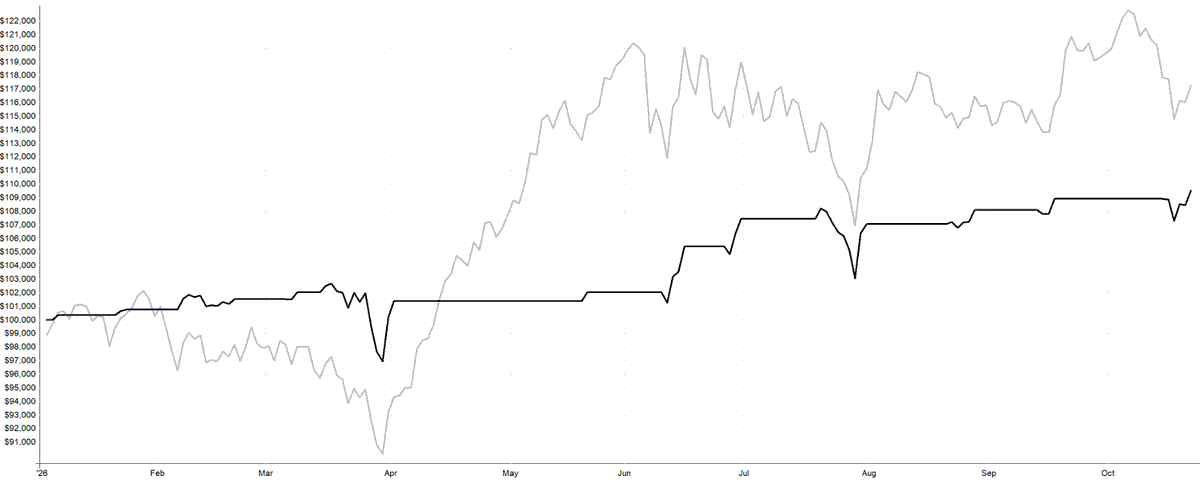
This chart shows a Nasdaq mean reversion system I trade live through a leveraged ETF.
In my experience, it usually behaves more smoothly than my individual-stock versions. The trade-off is lower profits. My version doesn’t beat the index.
I’m comfortable with that. It gives me another return stream, and using a leveraged ETF means it doesn’t tie up much capital.
Do you run mean reversion also on indexes?
In the chart: Black: my system’s equity curve. Gray: QQQ itself.
Friday was difficult for many long mean reversion systems.
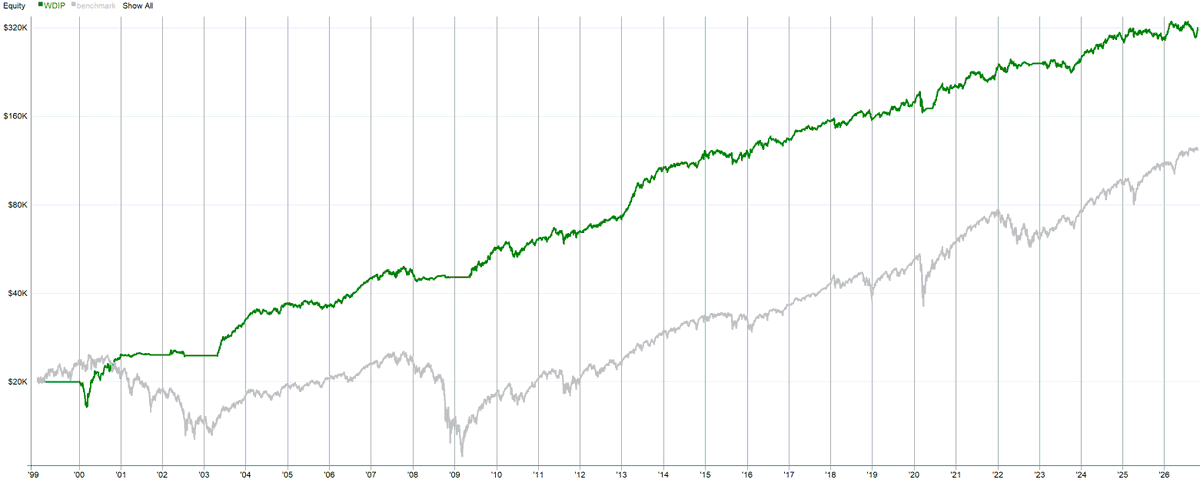
But this slower model, which I track publicly for many years, gained on that day.
I found the contrast interesting because it’s easy to put all these systems in the same “buy the dip” bucket.
The main difference here is speed. This model uses RSI on weekly charts across the S&P 500 universe. Nothing complicated.
One day doesn’t prove diversification. But slower timeframes are an interesting direction to test when looking for diversification within long mean reversion.
I track the model’s ongoing performance on Cracking Markets under:
Live Trading Models → Buy the dip (weekly).
@WolfhartInvest It smooths volatility, and this usually means it earns less money. Lower volatility is actually very positive for me. Too much volatility means investors will run away.
Friday’s dip in US stocks hurt my long mean reversion systems too.
Drawdowns look much easier when you can already see the recovery on the chart.
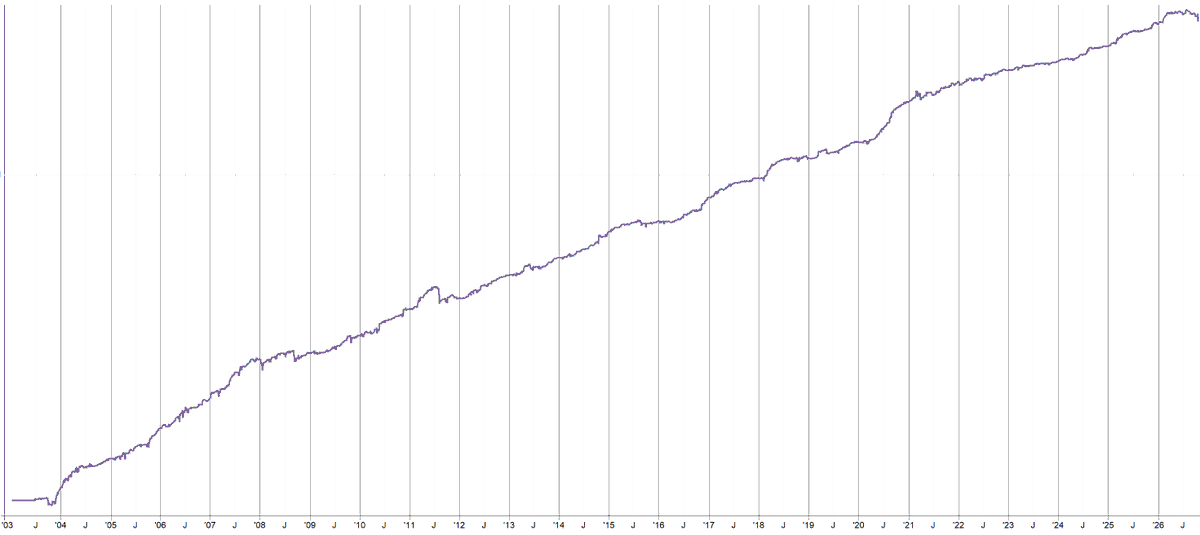
But looking at the combined simulated equity curve of these systems I live trade, roughly 4,000 trades, the size and speed of this drawdown were not unusual.
Mean reversion can produce a high win rate, with occasional larger losses. Those losses need to be reflected in the allocation from the beginning. I have hard limits on how much capital all these systems can use together. Their share of my portfolio is limited, and it gets smaller automatically as volatility rises.
LLMs have sent me back to my university maths.
And that’s changing the kinds of trading systems I’m trying to build.
All the systems I currently run are price-based. In some form, they express a view on price direction or momentum. That works, but it has limitations.
I’m not a quant or a mathematician. What I could build was partly constrained by the maths I was comfortable working with.
LLMs are helping me revisit what I learned at university, fill in the gaps, and build on it.
Over the past few months, I’ve been putting that learning into researching systems built around a view on volatility.
It feels like a different world from the systems I’m used to. The appeal is the possibility of adding a very different source of returns to my portfolio.
So far, LLMs haven’t made me work less. I’m working harder than before. There’s just a lot more I want to explore now :)
Can you build a hedge fund by combining the verified live results of independent traders?
I like the idea. I’m still undecided about how far you can get without understanding the strategies behind those results.
The concept is appealing:
• Give traders a platform to build verifiable track records.
• Select promising traders and strategies.
• Combine them into one portfolio.
• Manage sizing, correlations and risk centrally.
The traders keep their logic private. The allocator evaluates their results.
In theory, you could discover many independent sources of return that would otherwise remain in individual accounts.
I remember how promising Quantopian looked before it closed in 2020. More recently, I’ve been following Darwinex INDX with interest.
These are different implementations, and a drawdown in INDX alone doesn’t invalidate the idea. But they bring me back to the same concern:
How much of the selection process is simply data mining other people’s equity curves?
A verified live record tells you that the results happened. Establishing whether they reflect a repeatable edge is a much harder problem.
A trader can make money for several years through some combination of skill, favourable conditions and luck. Even an honest, disciplined trader may have weaknesses in the strategy that the market has not exposed yet.
Survivorship bias adds another problem: we see the attractive records of those who made it through, while many failed accounts disappear from view.
I see this when talking with traders. Sometimes the equity curve looks convincing, but discussing the actual process leaves me wondering how someone could feel comfortable putting money behind it.
Now select the most attractive records from a large pool and optimise their combination.
You can end up with a beautiful historical portfolio while still knowing very little about why it should keep working.
Different traders don’t necessarily mean different risks. Apparently unrelated strategies may depend on the same market conditions. What looked like diversification in the historical data may turn out to be variations of the same idea, using slightly different indicator settings.
And the selection and allocation process is itself a trading strategy. With limited history and many choices about whom to include, when to replace them and how much to allocate, there is plenty of room to overfit.
I still want the community fund idea to work.
But increasingly, I find myself paying more attention to the thinking and temperament behind the trading: how someone develops ideas, tests assumptions and deals with uncertainty.
Personally, I don’t trade other people’s systems. I need the conviction that comes from doing my own research. That is probably part of why I ended up becoming a trader myself.
But I understand the appeal of allocating capital to other traders. And a “meta-strategy” that combines their performance into a diversified portfolio still strikes me as a very appealing idea.
STP or LMT for breakout entries?
I want to catch the move. But I also care about how much I pay to get in.
A stop or market order prioritizes getting filled once the level breaks. A limit order gives me price control, with the risk of entering later or missing the trade.
That trade-off is worth testing.
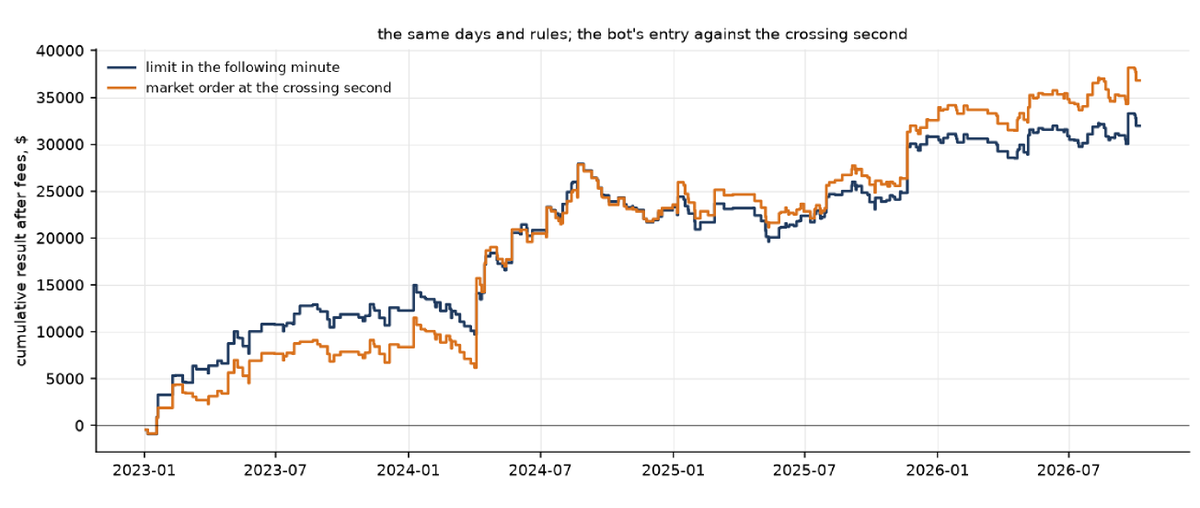
Here is an example from my intraday breakout using 0DTE options:
• Orange: market order when the breakout triggers. Fees included, slippage excluded.
• Blue: limit order in the following minute.
The immediate entry looks better before slippage.
But the slippage on market orders changes the conclusion. In my case, the limit approach works better in practice, especially at larger size.
The interesting part: the signal still has value even when I enter later.
@bitcoinblaize Deep dive with the rules and backtester is here: https://t.co/rBeovcjK6x
There is free registration, so the content is not freely available to AI.
My long mean reversion model (all rules shared) is making a new out-of-sample high.
+35% CAGR with a -10.6% drawdown over the period shown. And average capital use of only 15%.
This is a typical long mean reversion system trading Nasdaq 100 stocks. The same approach also works well on the S&P 500 universe.
Model results for the period shown:
• IBKR fees included
• CAGR: +35%
• Drawdown: -10.6%
• Sharpe ratio: 1.79
• Average capital use: 15%
That last number can create a temptation: make the system trade more.
Loosen the entries. Accept weaker setups. Keep more capital busy.
But every additional trade needs to earn its place. Increasing capital use only helps if those extra trades have an edge worth taking.
I prefer to let the model wait for its setups and combine it with other strategies, such as rotational momentum.
I share 100% of the rules, a detailed breakdown, and a free backtester so you can test variations yourself.
@Woodshedder@bitcoinblaize Deep dive with the rules and backtester is here: https://t.co/rBeovcjcgZ
There is free registration, so the content is not freely available to AI.
@SuperTrend76 Yes, this is true. But on the other hand, there are not many signals each day. And if you are tight on cash, you could modify this type of strategy so it monitors the market intraday and submits limit orders only when the market is close to the entry level.
@Dhairya_Motta Deep dive with the rules and backtester is here: https://t.co/rBeovcjK6x
There is free registration, so the content is not freely available to AI.
Can buying 0DTE options every day be profitable?
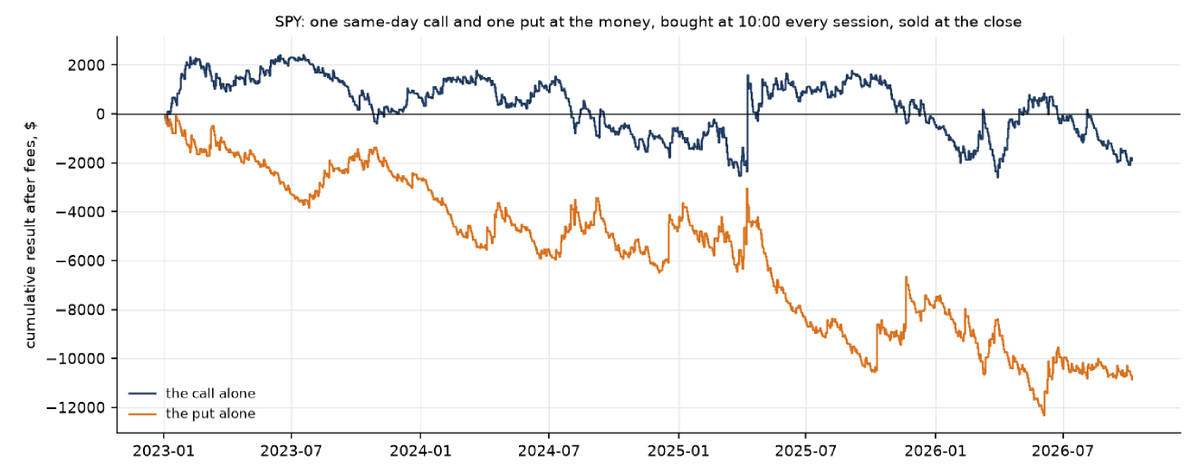
I backtested the simplest version: buy 1 ATM SPY call + 1 ATM SPY put at 10:00, then sell just before the bell.
944 trading days (2023 - 2026). $0.70/side fees.
Result: about -$12.7k. Lost money in every year tested.
• Before fees, the strategy lost about 4% of the total premium paid. Fees accounted for 21% of the total loss.
• SPY moved more than the straddle cost on only 38% of days.
• The 10 best days: +$14.6k. The other 934: −$27.2k.
• Calls nearly broke even (−$1.8k); puts lost $10.9k.
A few big days did a lot of the work. They still couldn’t cover the losses from the rest.
The edge, if any, is in choosing the day.
I just added new dedicated research server with 256 GB RAM for €85/month (ex VAT).
Not a VM. The whole machine, including hosting and electricity.
I needed more RAM and enough CPU threads to speed up some of my systematic trading research. Rather than order a new server, I took over an existing Hetzner contract.
The setup:
• Intel Xeon W-2295
• 256 GB ECC DDR4
• 1 TB SSD
Monthly cost: €85 ex VAT.
One-off takeover payment: €120.
Hetzner raised prices for new server orders in June, but left existing server contracts unchanged.
There is a marketplace on its forum where customers offer their dedicated servers for transfer to other customers.
Yes, it is older hardware. But I was looking for plenty of RAM and enough threads for research at a reasonable running cost - not the latest CPU.
For that purpose, this was a good deal for me.
Worth looking through those offers before ordering a new server.
I used to prefer systems that won often.
In recent years, I’ve shifted my portfolio more toward systems that win less often, but have much larger average winners than losers.
I previously favored higher frequency, mean reversion style systems. Frequent small profits felt comfortable. What I’ve become less comfortable with is the recovery process when losses start to cluster. When the average loss is much larger than the average win, you can suddenly find yourself looking at a mountain you have to climb one small profit at a time.
Lower win-rate systems are harder to live with from the beginning. Profits arrive less often. Losing stretches test your patience. But one large winner can recover several losses.
This is where automation helps me a lot. After a string of losses, I don’t have to talk myself into taking the next signal.
What about you? Do you prefer frequent small wins or fewer, larger winners?
Not every strategy in my portfolio gets an equal vote.
I run a systematic book: multiple strategies sharing the same capital, with weights chosen to fit the account.
But I build the foundation around deliberately simple systems.
I think of these as my “smart beta” sleeves.
The idea is to participate in market moves. Not constantly try to predict the next turn.
The risk management objective is to limit the damage from the worst market events. Not to beat the benchmark on every metric.
Two sleeves I currently use for this:
• Rotational momentum across stocks.
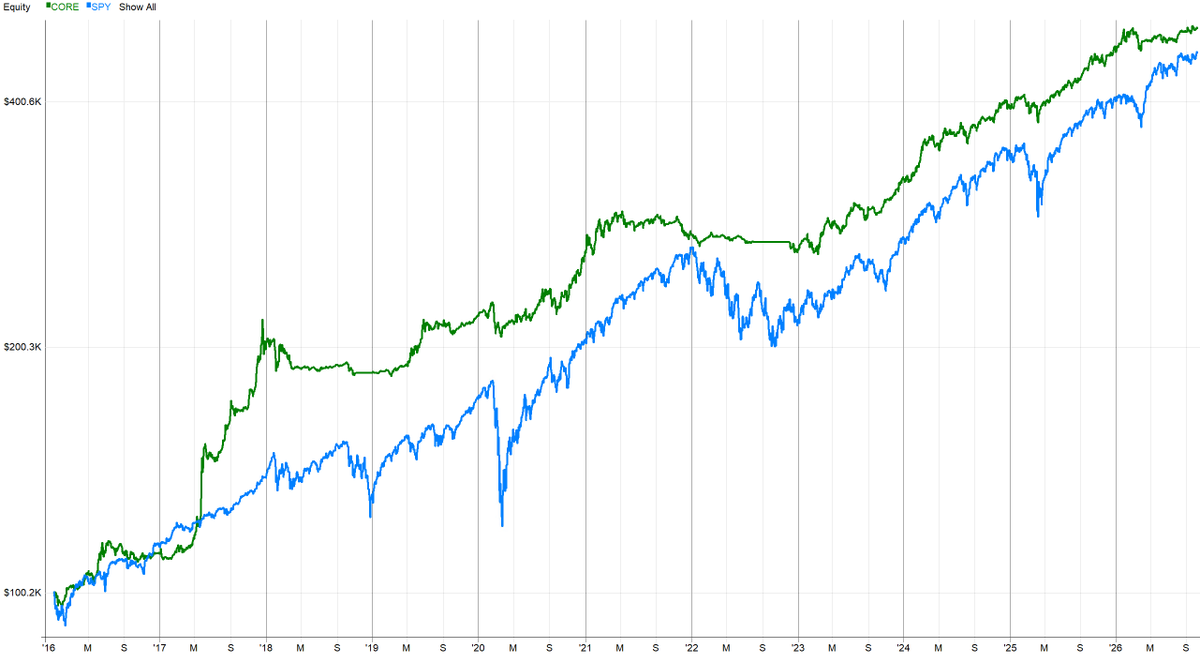
• CORE: trend following across a set of ETFs.
CORE is long-only, with very low turnover, but plays an important role in the overall portfolio.
I don’t need every strategy to be a highly active trading system. Some provide the foundation. Others complement it.
I want the weights to reflect those different roles.
50 live trades in my first SPX 0DTE option selling algo.
Roughly breakeven. Still in the "getting to know each other" phase.
A short romance or a long-term relationship? Too early to tell.
So far, the live path is consistent with the backtest. Roughly flat overall.
At this stage, that may be a useful outcome. A big drawdown could be demotivating. A big run could create too much confidence.
My main objective right now is to collect live execution data, compare actual fills with the ongoing backtest, and refine the machinery.
What I’m running:
• Selling 0DTE SPX call verticals.
• Risk capped by the vertical itself, with additional algo management to close some trades earlier.
• Small size while I battle-test the model.
Execution runs through my in-house Python scripts via IBKR.
This is my first execution bot built entirely through an LLM workflow, with me overseeing the process.
The execution is encouraging part: so far, I’m getting the midpoint fills I modeled in the backtest.
The model is simple, possibly too simple. I’m not treating 50 trades as proof of an edge.
But they are already giving me useful information about fills and ideas for further research. More importantly, they’re giving me the confidence to keep using LLMs to build execution systems I wouldn’t have been able to create on my own.