No Excuses just hit #85 Rising in Finance on Substack.
Built on one premise, most investors don't want to hear:
You don't have a return problem. You have a risk control problem.
Nobody wants that message when markets are running. Everybody wants it after the drawdown.
Thank you for being here.
$CAT: 3-month range broken. Trend band lost.
Next leg lower looks underway. Targets 720 / 680.
Selling call spreads to fund put spreads. Defined risk both ways.
Wrong above 800.
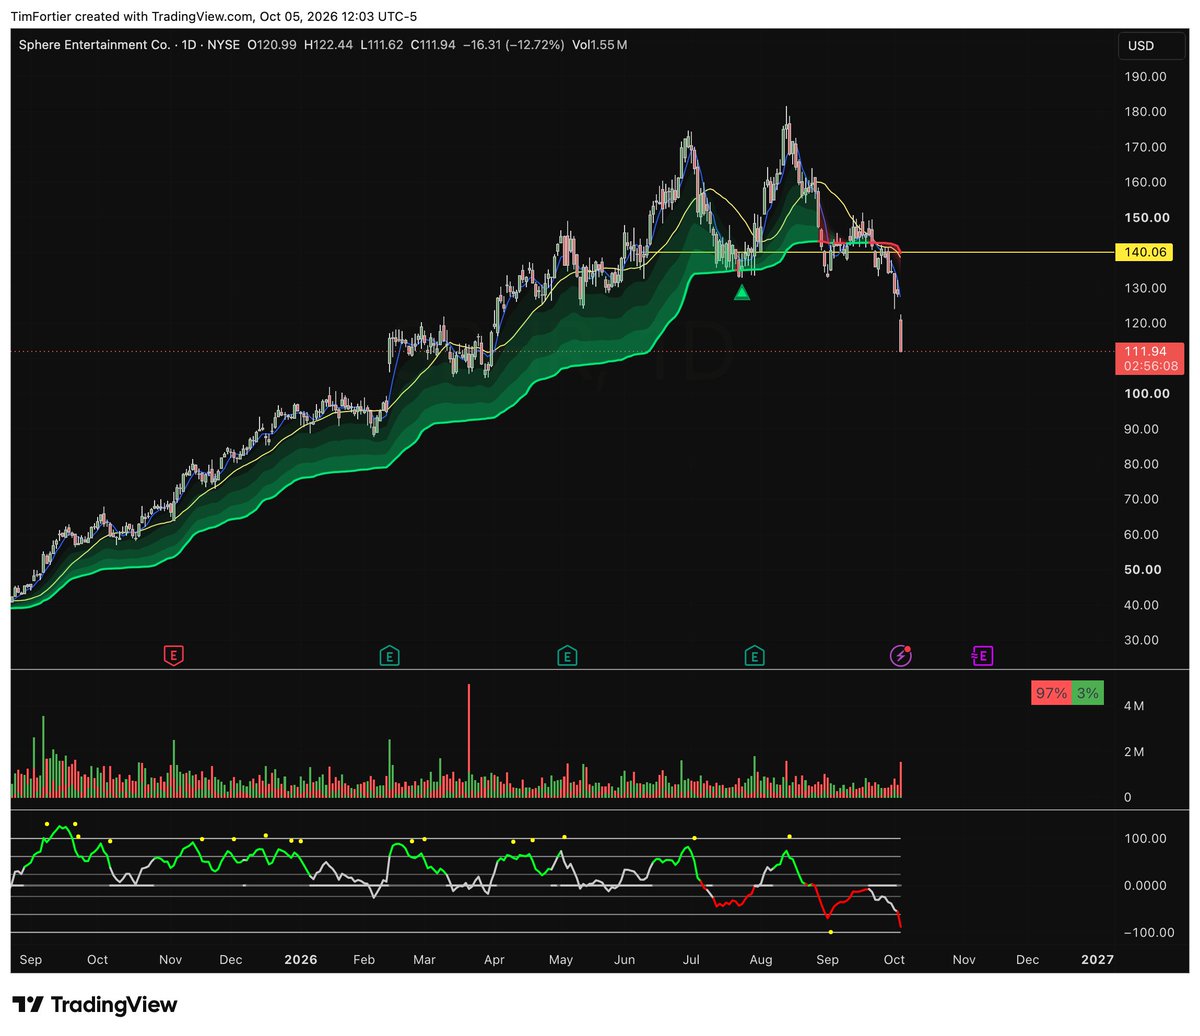
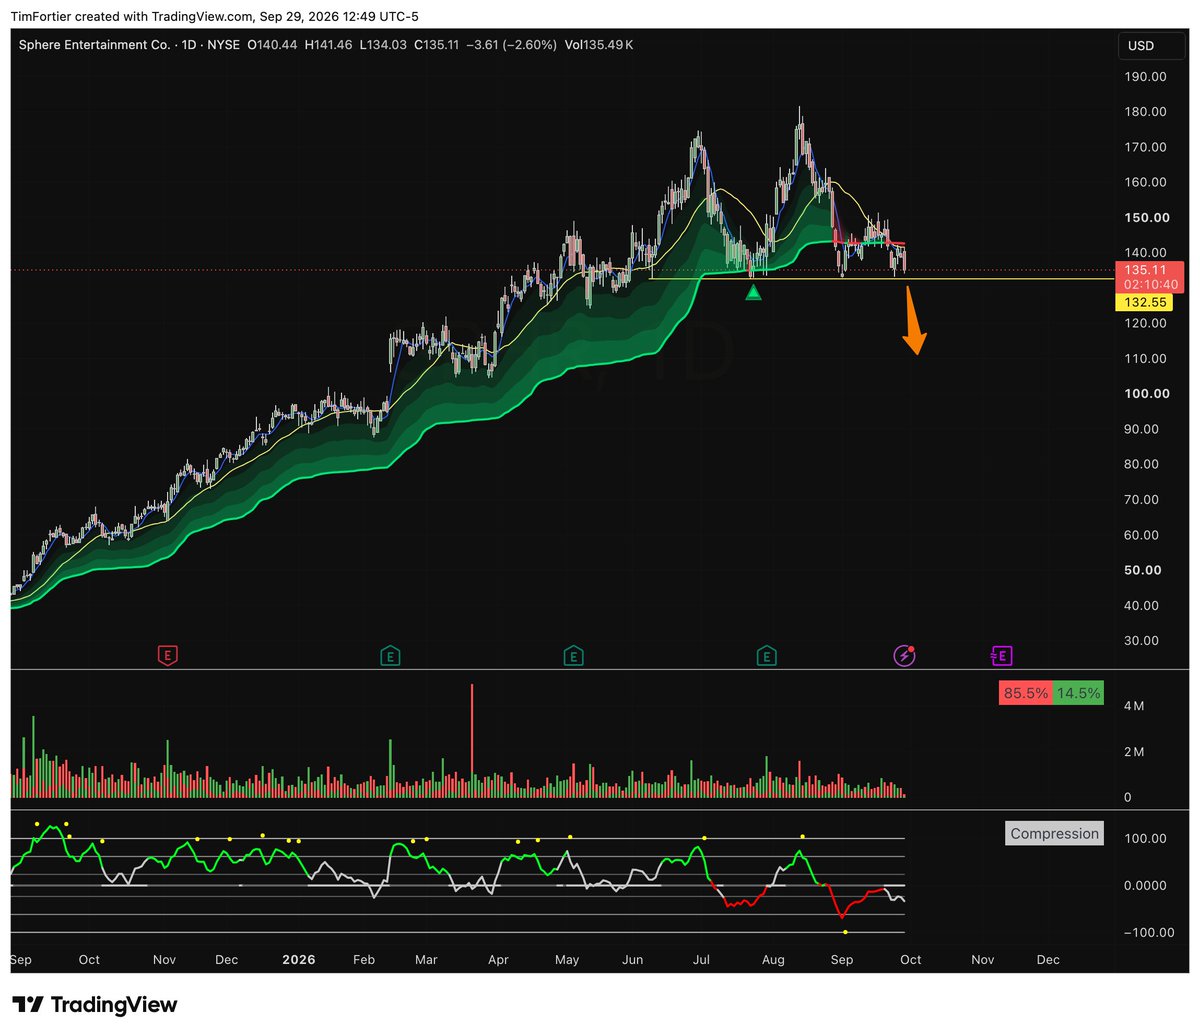
$SPHR update.
On Sept. 29, I presented my thesis to be short $SPHR.
Today: $112. Down 12.7% on the day. Down 17% since the post.
First target (115 to 120) is done. Taking partial profits, trailing the rest. Next level: high 80s.
Follow to get the next setup before it moves.
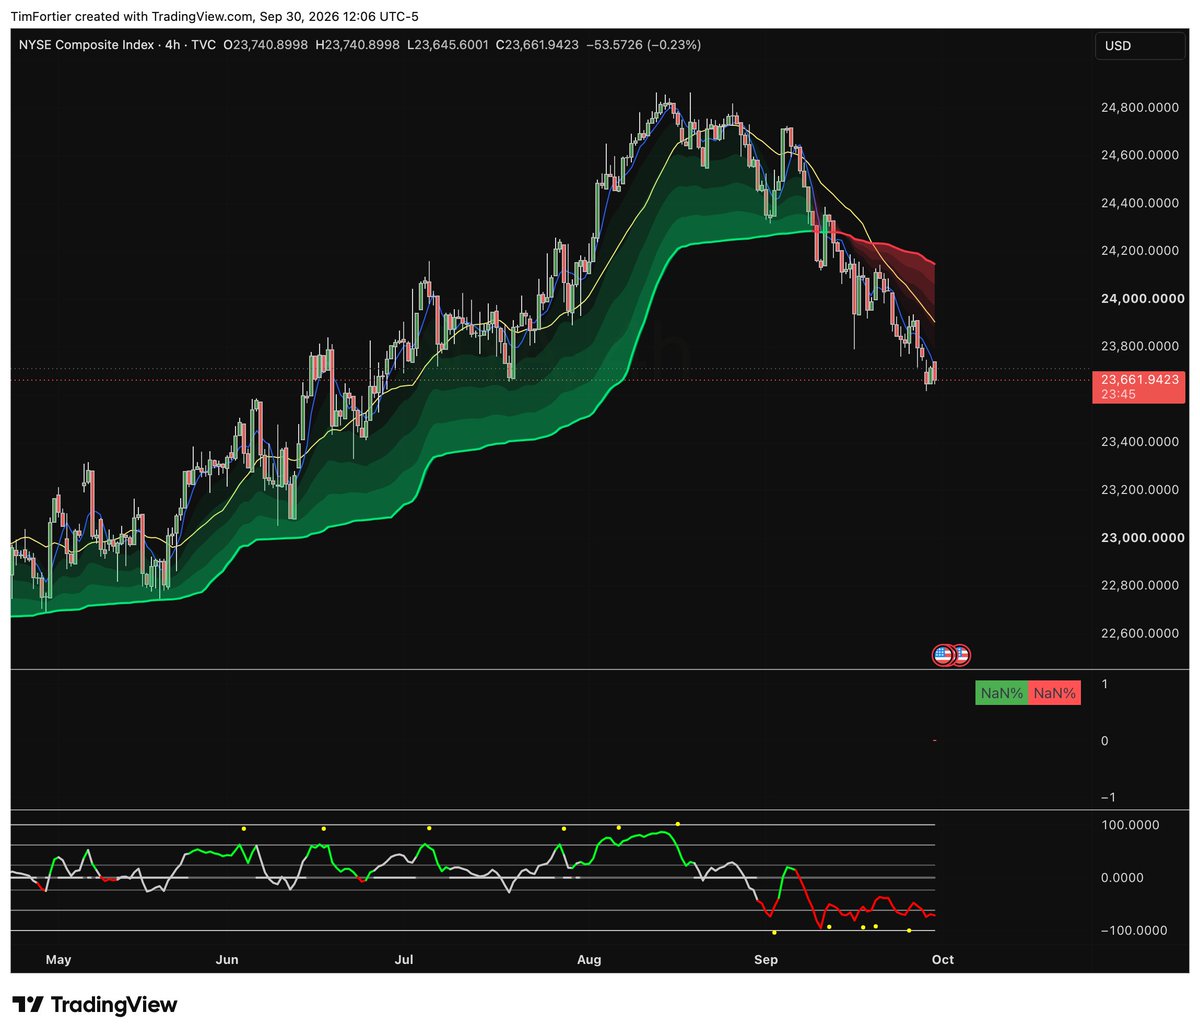
Meanwhile, here's the "other" market.
NYSE Composite, 4h: ~5% off the August high, trend ribbon flipped red, and a month of lower highs.
The index most people watch isn't the market most stocks live in.
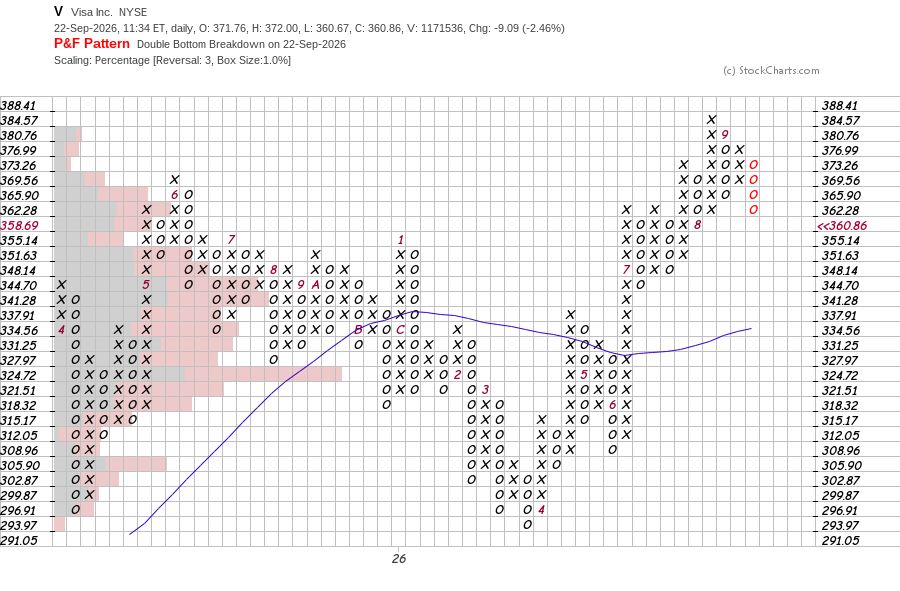
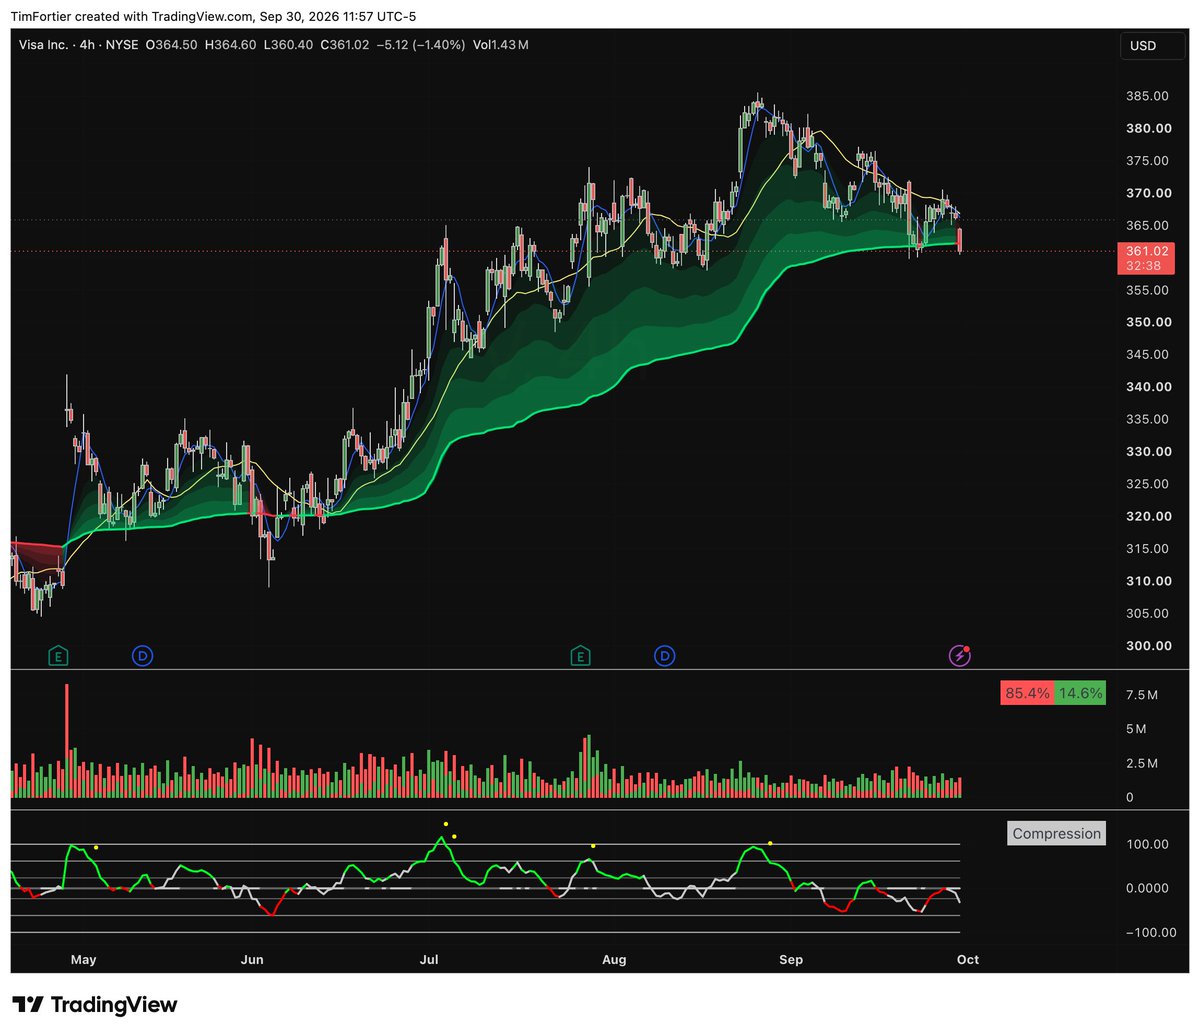
The payment networks are paying me to be bearish on them.
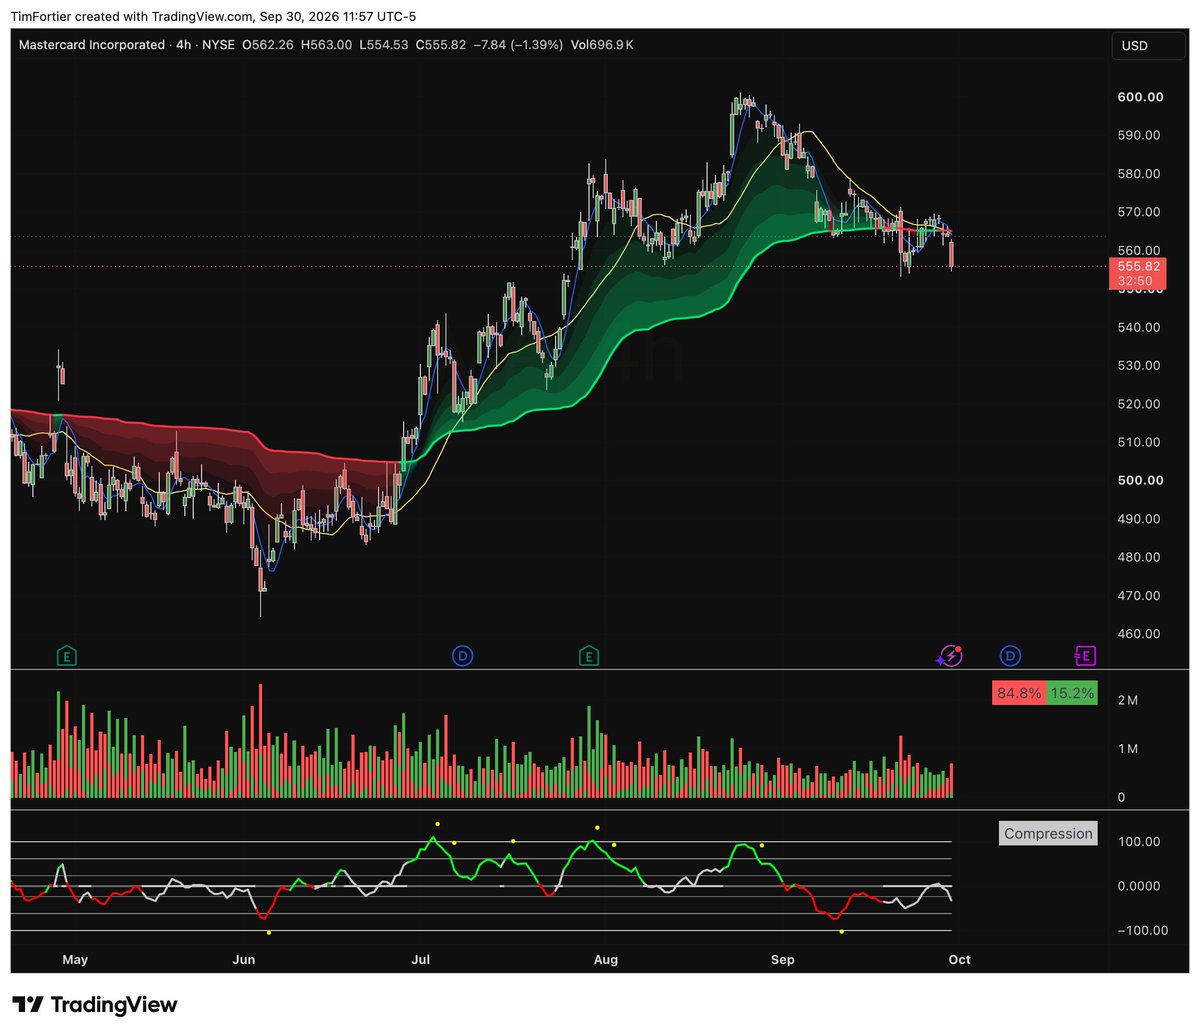
Sep 22: flagged $MA and $V as short setups. $MA just broke trend. $V is testing it.
Call credit spreads fund the put debit spreads.
Defined risk, cheaper conviction.
What could go wrong:
17.6% of the float is already short. 9 days to cover. This is a crowded trade.
One strong headline can squeeze it hard—earnings are expected in early November.
That's why I use defined-risk spreads.
Las Vegas doesn't have a money problem.
It has a people problem.
And the market is starting to price it. Here's the data and the next short on my list.
The plan:
Selling call spreads above.
Trigger for puts and put debit spreads: daily close below 132.55
Invalidation: reclaim of 143
First target: 115 to 120
Measured move: high 80s
Back on Sep 1, I presented $CBRL as an ideal short. It provided 10 points of gain.
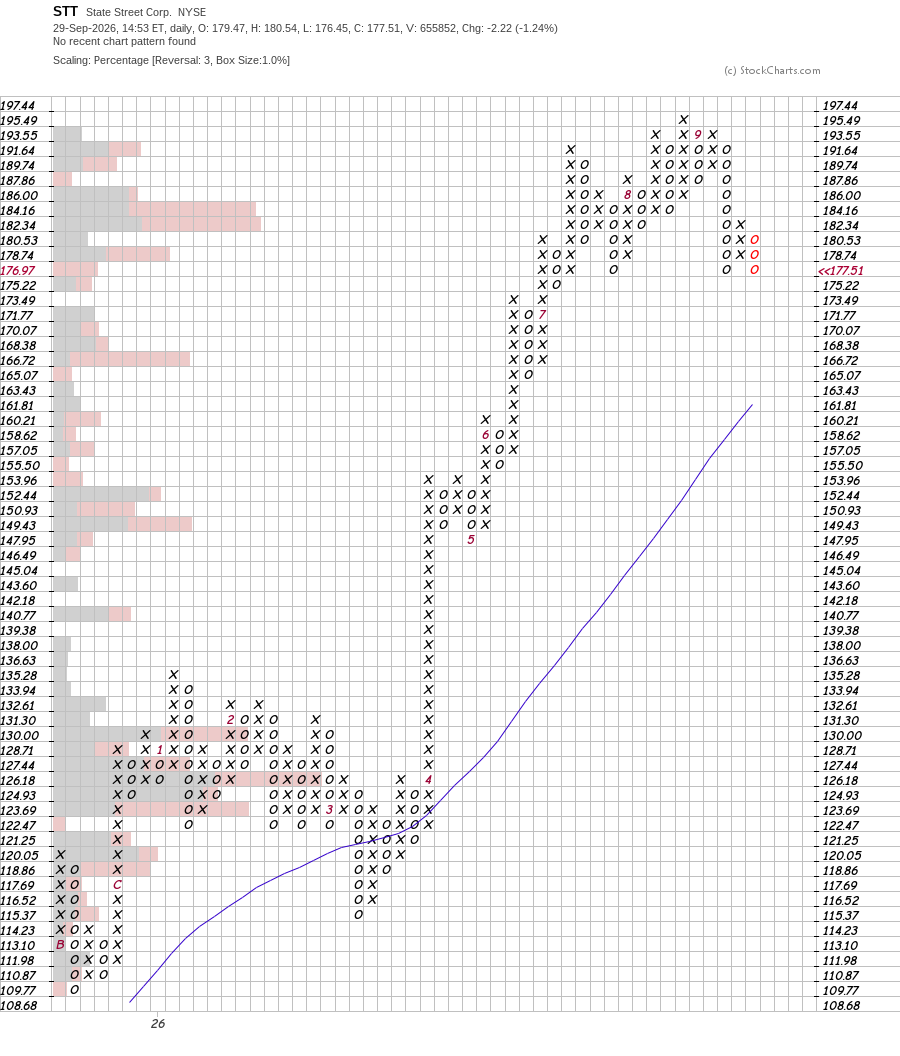
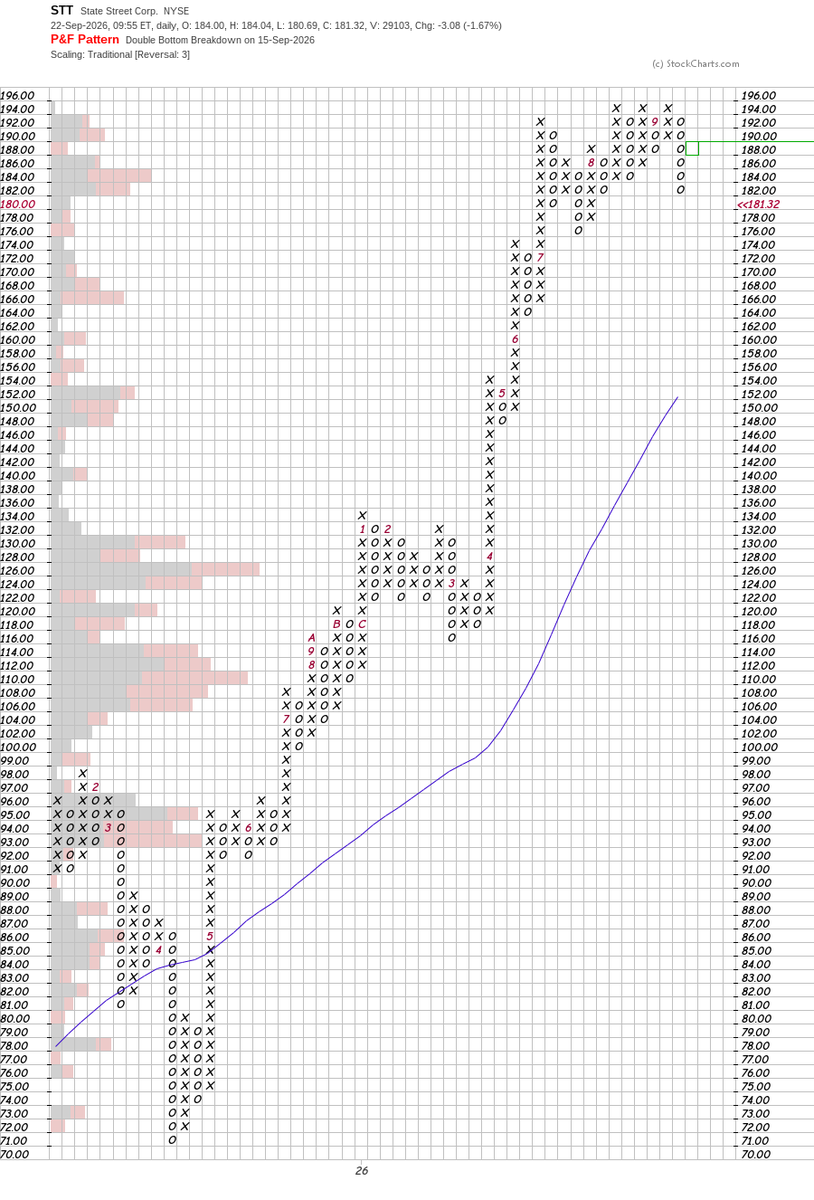
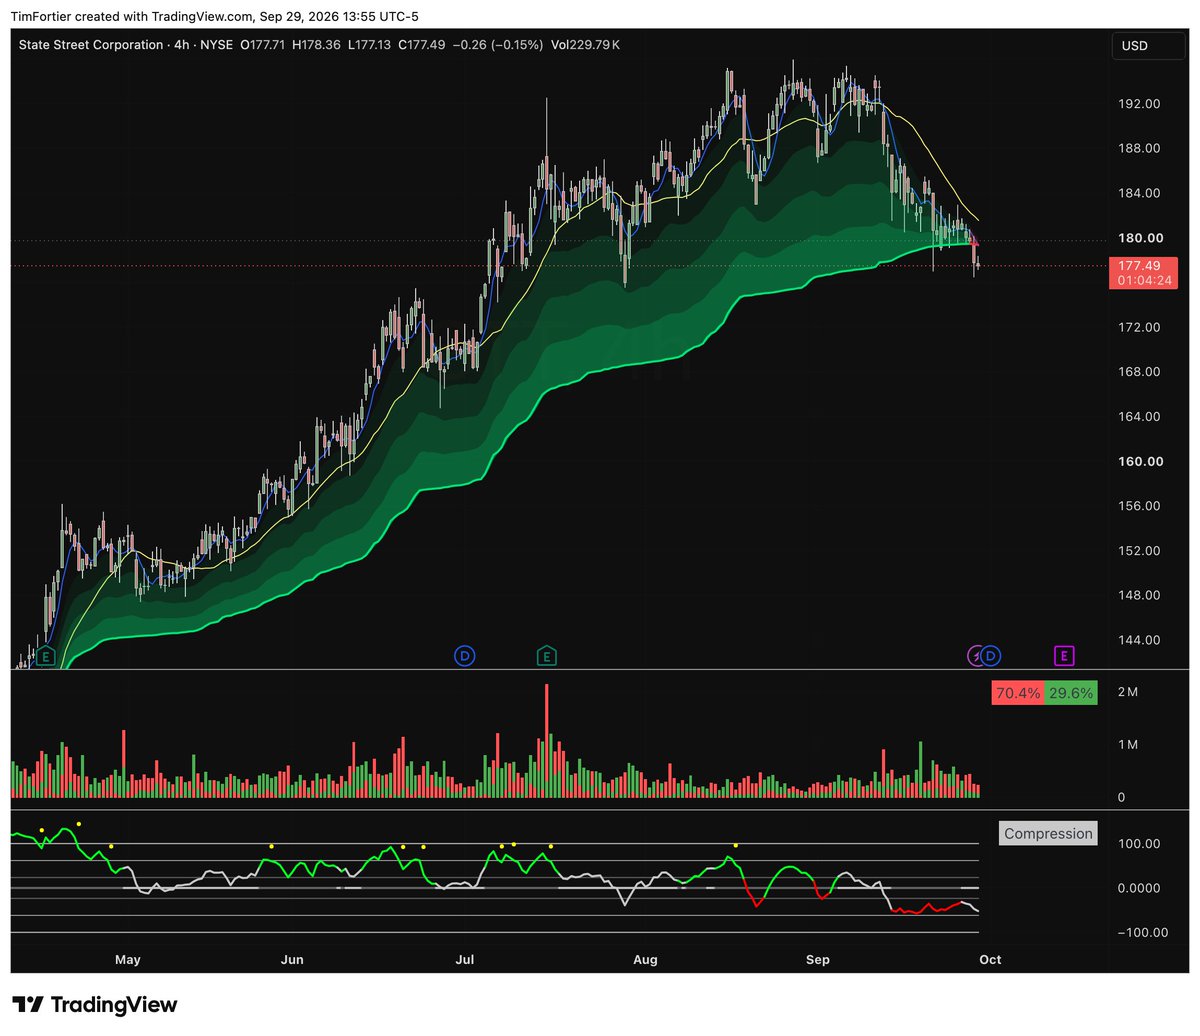
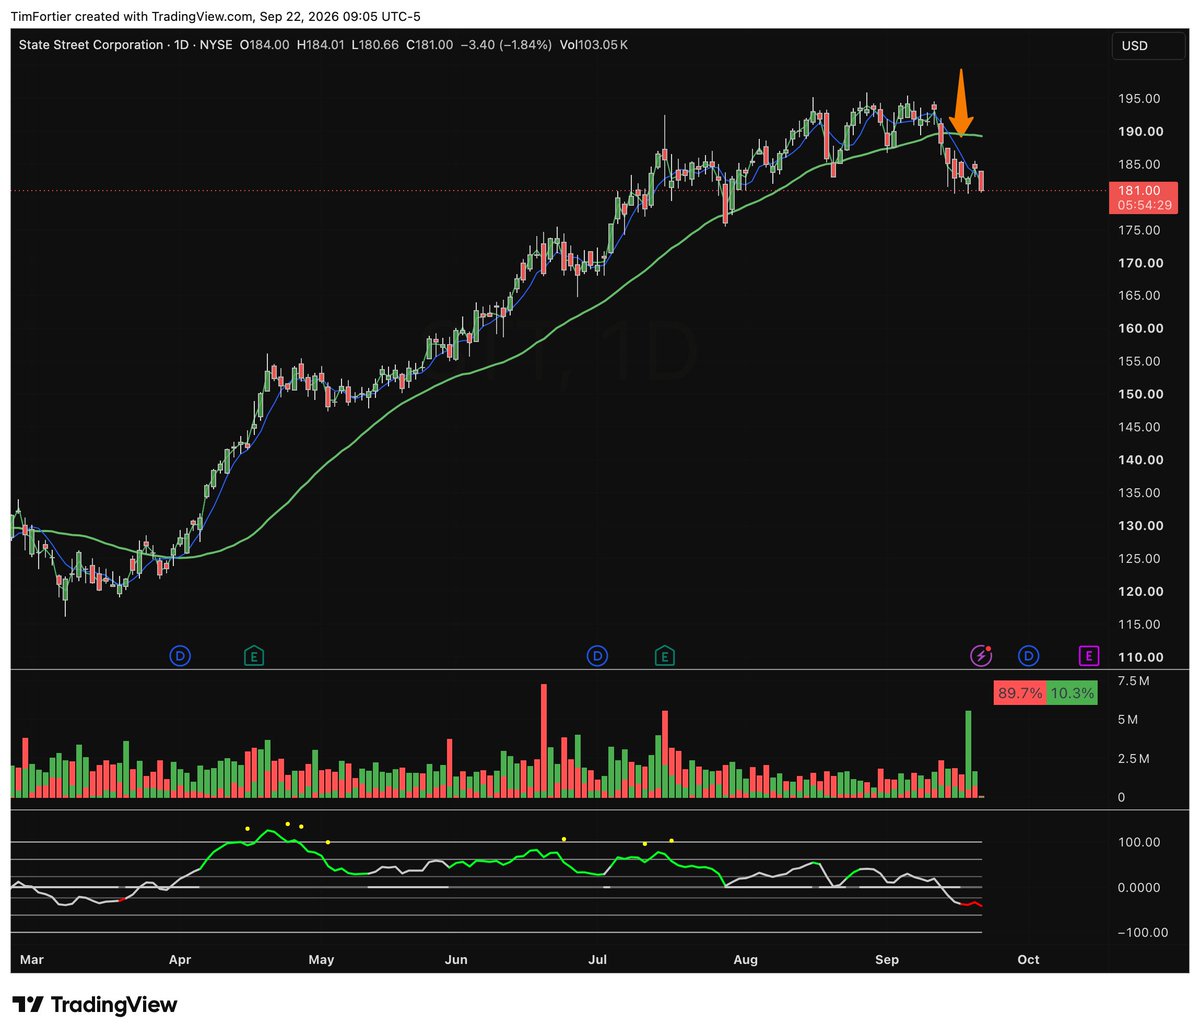
As I wrote about in this week's Substack, the banks are showing weakness.
One of my new favorite shorts is $STT. Call credit spreads and long puts, or put debit spreads.