One reason I bought $MCD is that I think the market is currently focused on weak US traffic, while I’m more interested in whether that weakness is temporary.
If traffic recovers, unit growth continues and margins remain resilient, today’s valuation could look very different in 12–18 months.
The key is proving the brand hasn’t lost its value proposition.
The biggest question in my $INTU thesis is also one of the main reasons the shares have become interesting to me: what happens if AI can do much of the work that people currently use QuickBooks and TurboTax to do?
The bear argument makes sense. If an AI agent can prepare accounts, answer tax questions and move information between different systems, perhaps the value of owning the underlying software becomes lower and switching becomes easier. I don’t think that risk should be dismissed simply because Intuit has been successful for a long time.
My current view, though, is that AI is more likely to increase the value of the platform than replace it.
QuickBooks already sits on years of financial history, invoices, payroll, payments, bank feeds and accounting relationships. If AI can use that data to move from showing a business owner what happened to actually doing more of the work for them, I think the product becomes more useful rather than less useful.
There are already signs of what that could mean internally. Intuit has reported developers coding around 40% faster with AI assistance and more than $135m of expected efficiencies from AI and automation, while management is simultaneously guiding to a large increase in GAAP operating margins.
The part that interests me most is what happens on the customer side. If QuickBooks becomes capable of reconciling accounts, chasing invoices, managing cash flow, helping with payroll and answering financial questions without the customer having to move between different products, the value of having all that data in one system arguably increases.
I could still be wrong. If AI makes the underlying accounting platform irrelevant and customers can move their financial data freely between agents, Intuit’s moat could weaken quickly.
But my base case is the opposite: AI makes the interface less important while making the data, workflows and ecosystem underneath it more valuable. That is a big part of why I think the disruption currently worrying the market could ultimately strengthen Intuit rather than weaken it.
One thing I like about the valuation of Intuit today is that I don’t need it to become the stock investors used to pay 40–50x earnings for.
At around $303, $INTU trades at roughly 15x the midpoint of FY27 GAAP EPS guidance of $20.24. My five-year base case gets earnings to around $31 a share, which comes from revenue reaching roughly $32bn, operating margins moving towards 34% and modest net share-count reduction.
If that happens and the market values Intuit at 19x earnings, I get to roughly $589 a share in five years. That works out at around a 15% annual return with dividends.
I don’t think that makes Intuit obviously cheap in the way an 8x earnings business might be cheap. There is still a lot embedded in those numbers: QuickBooks needs to remain a strong growth engine, the margin expansion has to come through and AI cannot materially weaken the value of the platform.
What I find attractive is that the valuation no longer requires everything to go right. I don’t need 15% revenue growth for another decade or a return to a premium multiple; I need something much closer to steady execution from a business that already has a strong position in accounting, tax and financial workflows.
That feels like a much healthier starting point for an investment than paying a great multiple for a great business and hoping the growth lasts forever
I've become fascinated by social arbitrage and observational investing.
Chris Camillo watches social trends.
Peter Lynch famously walked malls looking for consumer behaviour.
Buffett even went to see Mary Poppins while researching Disney.
Sometimes the investment clue appears before the financials do.
I love Zero to One by Peter Thiel.
One of the biggest lessons for investors is that the next great company probably won’t look obvious at the start.
The best businesses often don’t just compete better. They create something fundamentally different.
That makes me ask:
• What does this company understand that others don’t?
• Is the product dramatically better, not just slightly better?
• Can it dominate a small market before expanding?
• Could it create its own category?
The market gets much better at valuing a company once the economics are obvious.
The bigger opportunity is often recognising what a company could become before everyone else sees it.
@FindleysFinance Thanks for sharing! I have learnt the same lesson too. Some deeper digging and I could see management bonuses were based on where the stock price was in X years, not based on long term fundamentals.
On Thursday, I wrote about why Alexandre Arnault joining the $NKE board caught my attention.
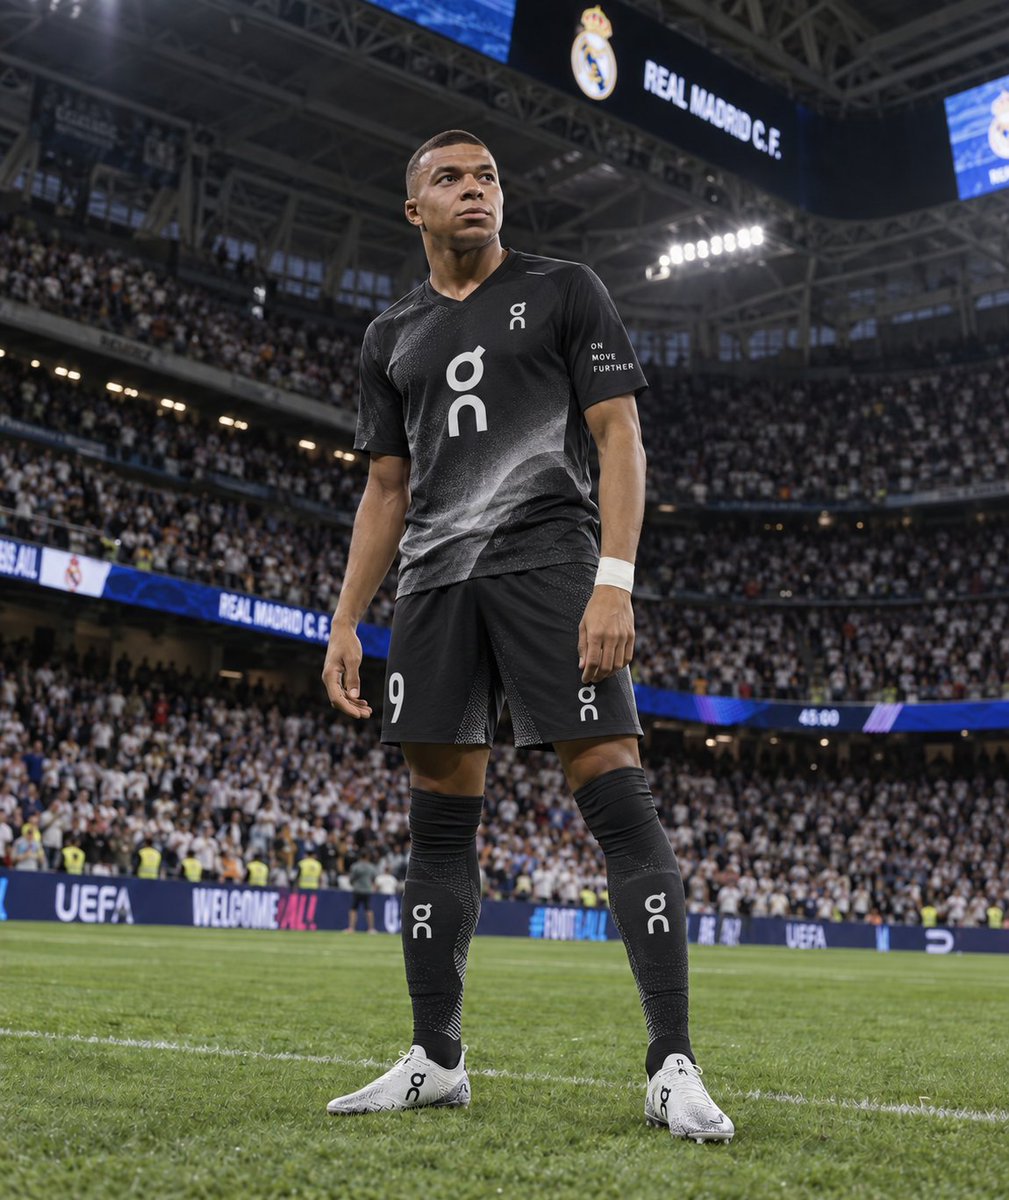
Yesterday, Kylian Mbappé leaving Nike after nearly 20 years to join On makes that appointment feel even more relevant.
On is using Mbappé as part of its push into football, with its first boots due in 2027. For a brand that built its reputation in running to convince one of the biggest footballers in the world to leave Nike and help build its entry into the sport is significant.
One athlete leaving doesn’t define Nike’s problems, but it adds to a pattern. Lamine Yamal has moved to Adidas, Puma has taken the Premier League match-ball contract, and newer brands increasingly seem confident attacking areas Nike once appeared to own.
That is why I keep coming back to the same issue with Nike. The problem isn’t awareness. It is whether the brand is still as desirable to the next generation of athletes and consumers as it once was.
It also makes the logic behind bringing someone with Arnault’s background onto the board easier to understand. Nike needs better product and performance innovation, but it also needs to restore some of the cultural pull that made athletes and consumers want to be associated with the brand in the first place.
I’ve owned $NKE and admired $LVMH for years, so Alexandre Arnault joining Nike’s board is a fascinating move that I didn’t expect.
It's worth noting that he isn’t coming in to run Nike. He joins as a director, which suggests his influence should be more around strategy, brand direction and long-term decision making than the day-to-day operation of the business. Nike itself highlighted his experience in brand building, innovation and digital transformation.
I can’t claim to have followed every step of his career, but the pattern is interesting. He helped lead Rimowa after LVMH acquired it, spending 2016–2020 repositioning an already respected luggage company into a much more culturally relevant luxury brand. He then moved to Tiffany after LVMH acquired it in 2021, becoming Vice President of Products and Communications and helping shape its product and communications strategy. Since February 2025 he has been Deputy CEO of Moët Hennessy.
What interests me is that he has spent much of his career around established brands and the challenge of keeping them desirable as consumers and culture change.
I’ve personally always found that fascinating with LVMH. How do brands built over decades remain aspirational to a new generation whose tastes, spending habits and definition of status may be completely different? That feels increasingly relevant to Nike.
The problem for Nike isn’t awareness. It's that competitors have been able to take attention and customers from a brand that once seemed almost untouchable.
In my own analysis of Nike, I’ve questioned whether some of that desirability has faded, particularly with younger consumers, while discounting and product saturation have made parts of the brand feel less special. This is where he could valuable.
If he can help Nike think differently about product, storytelling, cultural relevance and how a great heritage brand stays desirable to the next generation, I think that complements Elliott Hill’s push to restore sport and innovation.
Time will tell how much influence one director can really have, but as a Nike shareholder, I see it as an encouraging sign that the company understands the scale of the work required to make the brand feel special again.
Congratulations to the greatest investor of all time!
A man that has not only built an exceptional company, but one that is responsible for inspiring generation after generation of investors with his philosophy and patients.
There have been many times throughout my investing journey where I have deliberated an investment over and over or how an industry may grow over time. Then I listen to Warren talk and everything becomes clear.
Thanks for a legendary run!
This chart shows one of the reasons I am happy to hold $MCD. FCF and dividends have steadily increased, but the stock is priced as though that will change.
Considering they have just hit 50 years of consecutive dividend increases, with enough margin of safety in their FCF, I this think the market has mispriced McDonald's.
The best businesses can raise prices without reminding customers to reconsider the purchase.
A 5% price increase with little change in demand can flow disproportionately into profit.
Pricing power is not just a competitive advantage. It can be a powerful earnings engine
One characteristic of B&M that I probably didn’t appreciate enough when I first bought it is how unusual the product mix is from a macro perspective.
A significant amount of what it sells is everyday food, cleaning and household products, but sitting alongside that are toys, garden furniture, homeware and other discretionary purchases that are relatively inexpensive. That gives the business an interesting position.
If household finances become tighter, value becomes more important and consumers have a greater reason to trade down or search for bargains. If the consumer is doing well, B&M can still benefit because spending £10, £20 or £50 on something for the house or garden is very different from deciding whether to buy a car, go on holiday or make another large purchase.
It doesn’t make B&M recession-proof. Discretionary spending can still weaken and poor execution can hurt the business in any environment. But I like that I don’t need a particularly precise view on interest rates, inflation or economic growth for the investment thesis to work.
I think what B&M does internally over the next few years is considerably more important than my ability to forecast the UK economy.
For investors looking for opportunities today, I think B&M is still one of the more interesting turnaround situations.
I bought the shares at around 167p, but I still think they can deliver an attractive return from ~242p.
The reason is that I’m not relying on B&M suddenly becoming a high-growth business. Revenue is already close to £6bn and in my base case I only assume fairly modest growth from here. The bigger opportunity is margins.
Adjusted EBITDA fell from £620m to £459m last year despite revenue increasing. If management can repair the UK business and margins gradually recover towards more normal levels, earnings should grow much faster than sales.
I think they can turn it around because the plan doesn’t require reinventing the business. Management is going back to what made B&M successful in the first place: sharper pricing, simpler ranges, better availability and more disciplined promotions, while France continues to grow well.
My current underwriting suggests a mid-to-high teens annual return over the next 3–5 years if margins recover towards ~10.5% and the shares eventually rerate towards ~13x earnings.
There’s also an dividend yielding around 4% at today’s price, so I’m being paid while the turnaround plays out.
I’m already up considerably on the position, but that isn’t really why I continue to own it. I still think the return available from today’s price is attractive enough.
@ItsJamesHall I am with you!
I love the question, if money was no object how would you spend your days?
I think tell will tell you slot about what you should aim for