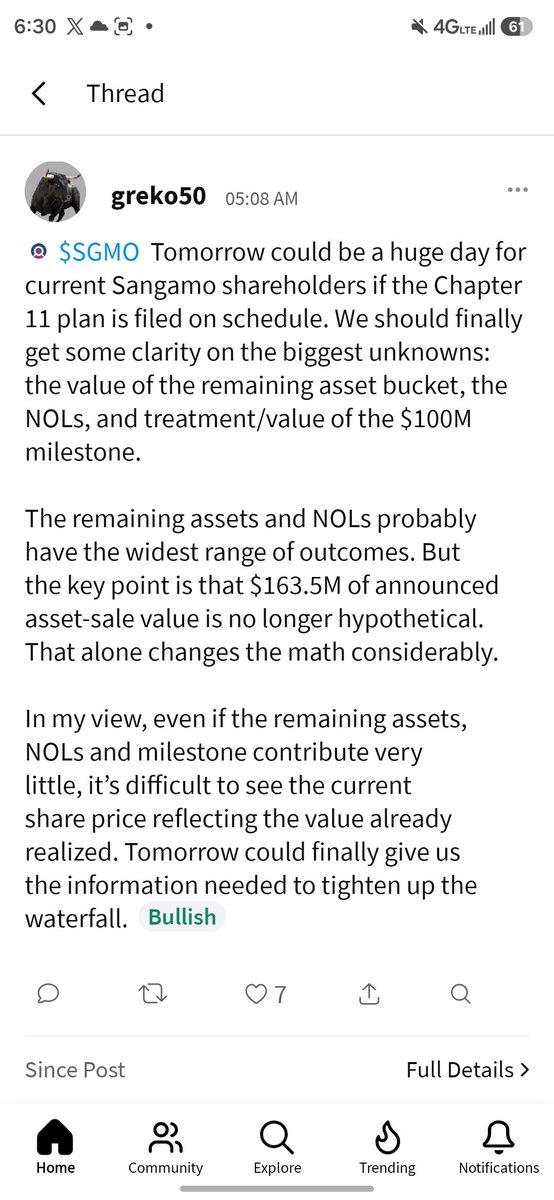
@wildcat_dburg@BiotechAnalysst I agree but it just sucks because it creates such an imbalance in the market, when only certain individuals have full access, while the rest of us are in sell only mode. Imagine when the plan gets filed or an asset sale takes place.
@Whoiswho53@vrotjan Obviously a good pt , and I'm sure the EC is well aware of that scenario. You have several different angles to look at when it comes to the remaining bucket of assets, NOL's, and milestone payments. Lot's of people want to maximize their payout now, others want to get what they
@vrotjan Lot's of unanswered questions at this pt, and yes only $5 mil is an extremely low example. NOL's are around 950 mil, and I believe it's anywhere from 1.5 to 5%, so roughly between 14.25 to 47.5 mil. As far as ST-503 being supposedly auctioned off sep, not sure with out more info.
@vrotjan $5 mil is purposely low, but it also shows valuing the remaining bucket of assets nearly impossible, hence why I gave such a wide range. In fact, the assets may not be worth a lot but the NOL's combined could push the value much higher. A lot of ways this could play out....
@vrotjan The first part is $80 mil, and depending on when the BLA is filed, sometime during the 4Q, you're looking around July-Aug timeframe for approval.
@vrotjan Our EC financial advisor Joshua Nahas argued that the NOL's were worth anywhere from .01-.05 on the dollar in other bankruptcy cases. As far as the assets, anywhere from $5-50 mil, strictly guessing. The really interesting part is the $100 mil milestone and how it's treated.
@vrotjan The $43 mil in intercompany liabilities I consider a wash and not counted against equity. In fact, I think Sangamo France can actual be a net + of $10 mil, it's being kept open solely for tax credit purposes. As for the remaining assets + NOL's, extremely hard to predict.
$aitx Hey Steve, why don't you tell everyone why dilution doesn't matter, how close you are to being OCFP, and last but not least, how you do the job of 10 people and only get paid for only 1!!! That's right Steve, let everyone know while they look at their wonderful AITX sp
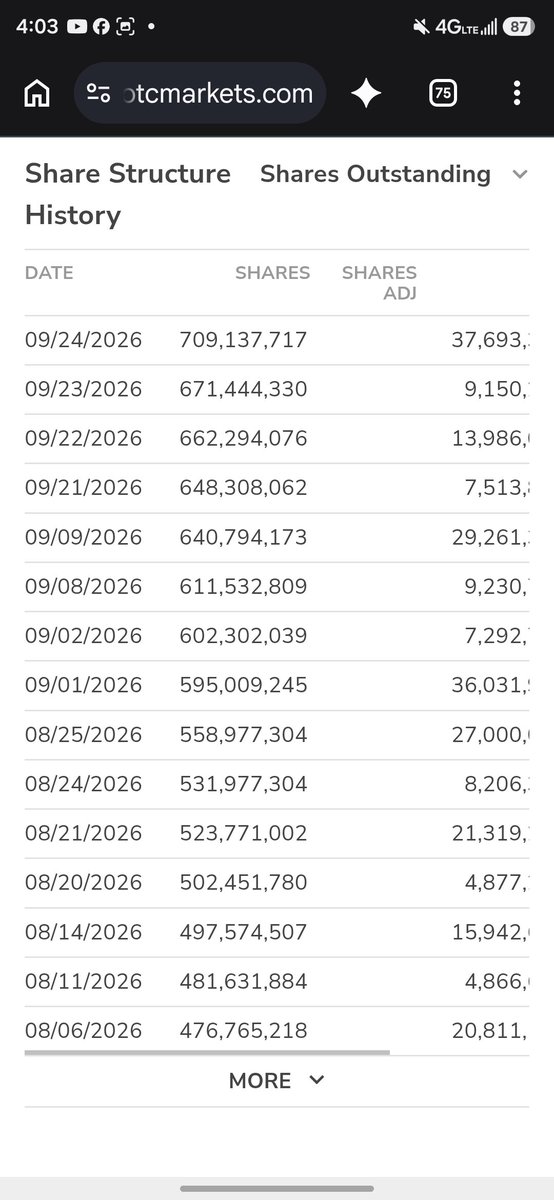
$aitx Seriously, is this guy cuckoo for Cocoa Puffs or what??? Still talking about being operationally cash flow positive, while avoiding the GIANT elephant in the room which is dilution that is bordering on insane levels, 20 bil pre-RS per month!!
$aitx Honestly, can anyone here think of a more arrogant, egotistical, narcissistic prick other than the infamous Steve Reinharz??? I mean WTF?? He's been running a dilution scam of co while paying himself insane amount of salary/bonuses for years now.
$vktx Massive upside for those who have the patience to wait, as we near major support levels. Plenty of cash now to see this through 2 massive readouts 2H/2027, Vanquish 1&2. Only a 4 bil mc with the added dilution from the offering. Just need a sliver of that TAM.....
@Soeren_Berlin@BiotechAnalysst Orrick can't magically make assets worth more than bidders will pay. Their job is to create competition and maximize value. These records show an alternative plan sponsor, a term sheet, bidder calls and negotiations. That's exactly what I'd want the Equity Committee doing.
$aitx Unfathomable amounts of dilution occuring as predicted, as this will easily hit 1 bil shares and beyond by the end of the year. I'm completely dumbfounded how anyone can invest here given the circumstances.....
@MitchellReed09 Way off base imo. This is a post of mine on ST. Extremely strong language and this is without remaining bucket of assets, NOL's, or $100 mil milestone payment.
$sgmo A revision to my previous Sangamo Equity Waterfall. I forgot to add in the Armastice warrants, and now I'm treating the $35 mil DIP as being fully used in all 3 scenarios. Still hard to nail down where we'll land, but risk/reward from here to me is very beneficial imo....
$aitx 15.558 BILLION old-share equivalents in 30 DAYS
Think about that comparison:
Entire FY2026: ~12.38B old shares added
Last 30 days: ~15.56B old-share equivalents added. And this all from money already blown months ago, what a fucking disaster!!!!!
@kaysaaa81 More than likely yes, but these are just estimates and can be adjusted up/down. Remaining bucket of assets will determine how much bigger the payout gets.....
$sgmo July MOR information: $16.91M cash, $18M replacement DIP, ~$78.1M prepetition claims, $43.39M intercompany payables, the lease/deferred-revenue treatment, and the much lower $4.1M actual July operating cash disbursements. Updated Equity Waterfall.......