$CRWV backlog went from $104B to $132.5B in one quarter. They say they're largely sold out through next year, with about 10x more demand than capacity. Demand isn't the problem. Building capacity fast enough is.
Stick with the ones that have power to build out. NFA
AI-infra miners fell about 35% on average in October. VanEck's take is that no signed leases were canceled, and power is still the binding constraint on AI compute. Prices moved a lot. The contracts didn't. 🔌
Know what you own. NFA
@elonmusk@bot@grok can @bot help me win a legal case against a gym where my watch was stolen from my locker and cctv footage of outside the gym was lost but there is locker logs of the time of the theft?
$KEEL-BIG NEWS FOR!🎉🎉🎉
Capacity expansion studies for Panther Creek and Scrubgrass,
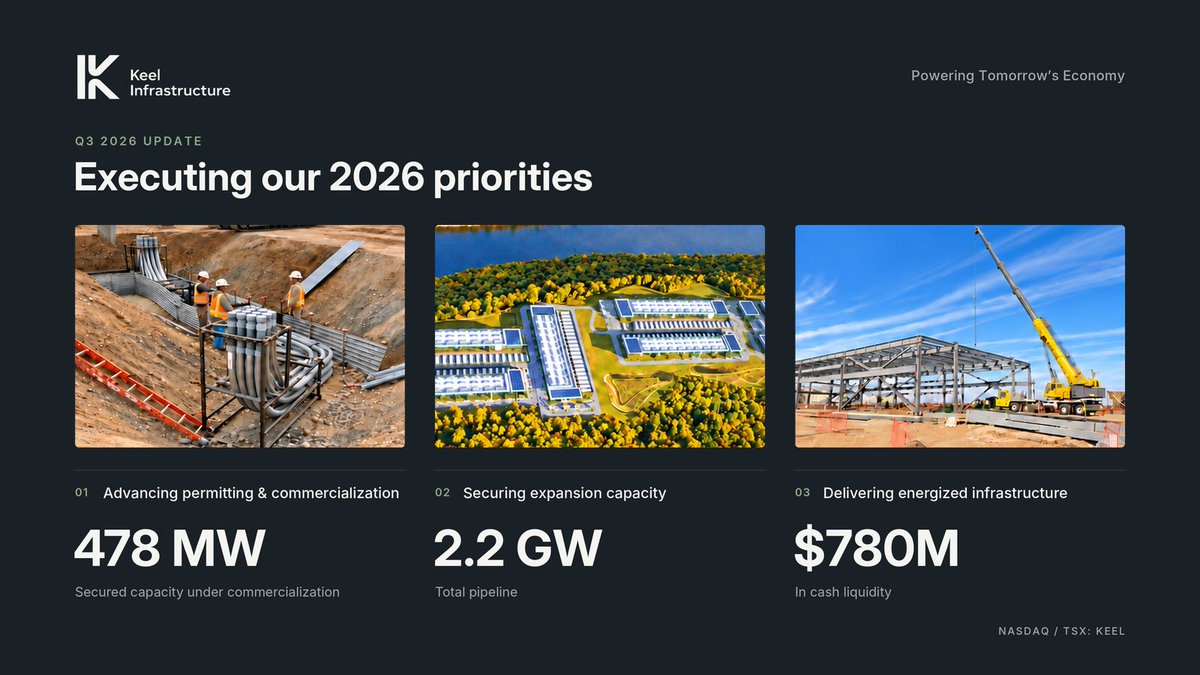
increasing capacity from 478 MW to 1,928 MW. Completion is expected in the first quarter of 2027.
(If this helps you, like + follow +share.)
$KEEL Completely speculative, but based on the Mcnalliemoney interview with Ben I’ve concluded that Keel has a credit worthy customer under LOI, while also maintaining talks with additional counterparts to keep tension on the LOI. Ben also explicitly said they would announce a contract before construction at Moses Lake is completed, obviously. Given the current site progress I would say its on track to be ready by May. Knowing timelines from personal commercial work experience, they’d want to have a customer signed at least 6 months before the site is ready to be handed over. This puts the timeline for a signed deal and SEC announcement requirements sometime in December. nfa.
Sneak peek of tonight's visit with @CaptainKeel CEO @keelinfra_ - you don't want to miss this one!!! 👀👀👀 $KEEL
Full video will be posted out shortly!!!
🚨 If $KEEL secures all 3 leases with high-quality, Tier 1 hyperscalers on 15-year agreements, how high could the stock realistically go before pulling back?
Assuming approximately 478 MW across the three projects at an average lease rate of $2.4M per MW annually, that would represent roughly:
• $1.15B in potential annual revenue at full operation.
• $17.2B in total contracted lease value over 15 years.
Here’s how I see the potential price ranges:
$6–8: Initial market re-rating as investors recognize the value of the signed leases.
$9–12: Strong bullish scenario if financing, construction, and tenant commitments are solid.
$14–18: Possible FOMO and short-squeeze territory if all three deals are announced close together.
Of course, signing contracts doesn’t mean immediate revenue. Financing, dilution, construction timelines, and execution will still matter.
My personal view: If all three Tier 1 hyperscaler leases are signed for 15 years, I wouldn’t be surprised to see $KEEL reach $12–15 before a significant pullback.
The big question is: Will the market finally start valuing $KEEL based on what it can become, rather than what it earns today? 🚀
Keel reported Q3 earnings today and conditions in the financial markets are far more volatile than conditions on the ground or at the negotiating table.
Here's some of what the Keel Crew got done this quarter:
· Advanced lease negotiations with significant technical diligence completed and mutliple LOIs negotiated, at multiple sites with multiple counterparties.
· Kept our power delivery schedules intact under our ESAs and PA’s new Executive Order, which we fully endorse.
· Engineered solutions to be fully compliant with the Executive Order.
· Broke ground at Moses Lake.
· Cleared three more permits in PA. To date, no permit application has been denied at any of our sites.
· Introduced the Keel Standard, our commitment to the communities where we build.
Heads down, shovels up.
“Demand is higher today than it has ever been, with increasingly fewer options for customers to grow in 2027 and 2028.” - Ben Gagnon, CEO & Director
$KEEL Q3 2026: Construction underway at Moses Lake, first HPC revenue in 2027. PA permitting advancing. ~$780M cash liquidity.
More on our Q3 results: https://t.co/TLYjma77OZ