1/7
If you’re stuck in a job you don’t love, exhausted, stressed, and wondering if there’s any way to build real freedom
Read this
This is the honest story of how I went from corp. burnout → F/Time trader
…and what I’d tell anyone who wants a real shot at changing their life
PRE-MARKET MOVERS | Fri Oct 23
$RNG $AXTI $XPEV $SKHY $LITE $SPCX $HAFN $FRO $BP $OXY $XOM $CVX $DOW $MU $NET $TTMI $LRCX $INTC $NVDA $TSLA $AMD $CRDO $MRNA $BE $NCLH $WDC $BABA $NKE $GE $AXP $NEM $ASTS $CCL $LUV $UAL $AAL $DAL $SMR $META $CRWV
Read-Through
Macro: A bounce attempt after Thursday’s AI selloff, when the S&P 500 fell 1.2%, the Nasdaq fell 2.6% and the Philadelphia Semiconductor Index fell about 6.7%, while the Dow and Russell 2000 held flat to slightly higher.
Futures are mixed this morning: S&P 500 down about 0.2%, Nasdaq 100 down about 0.1% and Dow down about 0.6% as of 7:15 a.m. ET.
Oil is higher, with WTI around $101, up about 2%, after strikes on Saudi oil infrastructure, tanker threats in the Strait of Hormuz and a larger than expected crude draw in the EIA report.
The 10-year yield is near 5.0%, and French bond market turmoil and AI financing concerns are in the mix. The Fed meets Oct 28.
AI leaders and chips: Stabilizing. Nvidia, Tesla, AMD and Intel are roughly flat after Thursday’s drops, and Lam Research is steady after losing double digits.
Memory: The strongest AI pocket. SK hynix and Micron are higher after Thursday’s selloff, with SK hynix also higher after suspending its review of a possible Solidigm listing.
AI infrastructure after earnings: Still under pressure. Bloom Energy, Credo and Western Digital are lower even where results were strong.
SpaceX: Higher after Phillip Securities upgraded it to Buy, and cell-tower stocks Crown Castle and American Tower are up on a Bloomberg report of SpaceX talks over cell-site access.
Energy and tankers: Green with oil, including BP, OXY, XOM, CVX, FRO and HAFN.
Airlines and cruise lines: Lower with fuel costs, led by Norwegian Cruise Line after a JPMorgan downgrade.
Gold and China: Newmont is lower after earnings as gold falls, and Alibaba and other China ADRs are lower again.
Earnings: RingCentral and Robert Half are sharply higher on beats, while American Express and Autoliv are lower after reporting.
Biotech: Moderna is lower again ahead of full melanoma vaccine data at ESMO.
We’re seeing relative strength in:
✅ Memory (SKHY, MU)
✅ SpaceX and cell-tower names (SPCX, CCI, AMT)
✅ Energy and tankers (BP, OXY, XOM, FRO)
✅ Earnings beats (RNG, RHI)
Weakness in:
❌ AI infrastructure after earnings (BE, CRDO, WDC)
❌ Cruise lines and airlines (NCLH, CCL, AAL, UAL)
❌ Gold miners (NEM)
❌ China ADRs (BABA)
❌ MRNA
Watching closely: Whether Thursday’s AI flush has found a floor or this is a bounce that gets sold into the close of the week, with oil and Hormuz headlines, a 10-year near 5% and next week’s Fed meeting all in the background.
@TradersAscent
NOT FINANCIAL ADVICE
PRE-MARKET MOVERS | Thu Oct 22
$BHVN $DOW $NET $PANW $CRWD $XOM $OXY $CVX $BP $PSX $WMT $LLY $UNH $NOC $LRCX $TTMI $IBM $TSLA $META $AMZN $SPCX $SMCI $NVDA $AMD $INTC $MU $AMAT $MRVL $CRWV $NBIS $IREN $MSTR $COIN $HOOD $AAL $UAL $FCX $BABA $XPEV $DELL
Read-Through
Macro: Futures are sharply lower. Nasdaq 100 futures are down about 1.7%, S&P 500 futures down about 1.1% and Dow futures down about 0.7% as of 7:16 a.m. ET, after the S&P 500 closed Wednesday up 0.6% and near its all time high.
The trigger is AI capital spending: last night’s reports from Tesla, Meta and IBM, plus Lam Research, did not settle worries about the return on AI spending. Oil is also higher. Iranian state TV said seven tankers were attacked or hit by mines in the Strait of Hormuz, which the Associated Press could not verify, and the State Department ordered some diplomatic staff and families out of Saudi Arabia.
AI leaders: Tesla, Meta and IBM are all lower after earnings. Tesla cut its 2026 capex forecast to about $20B from more than $25B and lowered its long-term sales target. Meta beat but raised its capex outlook to $135B to $145B, and free cash flow turned negative. IBM beat but missed on gross margin, and its CEO said some customers question whether AI investments are paying off.
Semis and AI hardware: Red across the board. Lam Research is down sharply after guiding below consensus, and equipment (AMAT, KLAC), chips (INTC, AMD, NVDA, MRVL, MU) and servers (SMCI, DELL) are all lower after Wednesday’s rally.
Neoclouds and crypto: CoreWeave, Nebius, IREN and the miners are lower, with MSTR, COIN and HOOD down as bitcoin falls about 2.6%.
SpaceX: Giving back part of Wednesday’s gain.
Airlines and China: Airlines are lower with oil, led by American after it scrapped its full year guidance. China ADRs are lower after Beijing’s market regulator met with e-commerce platforms on product quality.
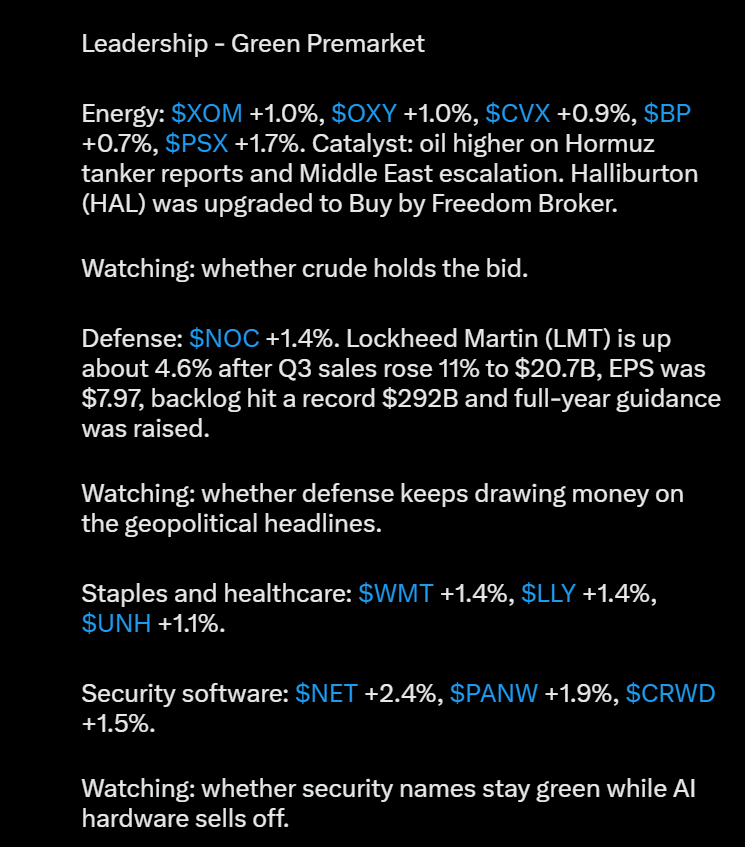
Energy, defense and defensives: The green side. Energy is higher with oil. Defense is bid after Lockheed raised guidance. Staples and healthcare names are higher, and security software is up again.
Biotech and chemicals: Biohaven is up sharply on FDA news and Dow is higher after earnings.
We’re seeing relative strength in:
✅ Energy (XOM, OXY, CVX, BP)
✅ Defense (NOC, plus LMT)
✅ Staples and healthcare (WMT, LLY, UNH)
✅ Security software (NET, PANW, CRWD)
✅ BHVN, DOW
Weakness in:
❌ AI leaders after earnings (TSLA, META, IBM)
❌ Semis and equipment (LRCX, AMAT, INTC, AMD, NVDA)
❌ AI hardware and neoclouds (SMCI, DELL, CRWV, NBIS, IREN)
❌ Crypto (MSTR, COIN, HOOD)
❌ Airlines and China (AAL, UAL, BABA, XPEV)
❌ Copper and gold miners (FCX)
Watching closely: Whether the AI capex worry from Tesla, Meta, IBM and Lam turns into a broader unwind of this week’s rally, with oil and Hormuz headlines adding pressure, and what Western Digital, Newmont and Deckers say after the close.
@TradersAscent
NOT FINANCIAL ADVICE
PRE-MARKET MOVERS | Wed Oct 21
$SPCX $TSLA $SMCI $DELL $HPE $VRT $AMKR $CRDO $LITE $WDC $MU $SKHY $INTC $NVDA $AMD $MRVL $KLAC $LRCX $CRWV $NBIS $IREN $APLD $CIFR $WULF $MARA $MSTR $HOOD $BE $XE $OKLO $SMR $RKLB $DOCN $ZM $NFLX $XPEV $LI $BABA $CMG $FTNT
Read-Through
Macro: The AI trade is back in charge. Yesterday’s close was mixed (Dow +1.0%, S&P 500 +0.3%, Russell 2000 +1.7%, Nasdaq slightly lower) as oil eased from near its highs of the Iran war. Oil is still the risk. The U.S. called a peace deal “difficult” and Iran’s foreign minister said the Strait of Hormuz stays closed until its conditions are met. Tesla, Meta and IBM report after the close today.
AI hardware and servers: The strongest group. Super Micro raised its preliminary quarterly revenue guidance well above prior estimates, and Dell, HPE, Vertiv, Amkor, Credo and Lumentum are all sharply higher.
SpaceX and Tesla: SpaceX is up after its first quarterly profit since its June IPO, with Musk saying SpaceX and Tesla have formed independent special committees to evaluate a potential merger. Tesla is also higher ahead of its report tonight.
Neoclouds and miners: CoreWeave, Nebius, IREN, Applied Digital and Cipher are all higher after Musk dismissed fears of an AI compute glut. Bitcoin miners and MSTR are bouncing with them.
Semis and memory: Green across the board, led by memory (Micron, SK hynix, Sandisk, WDC) and equipment (KLAC, LRCX, AMAT). Intel, Nvidia and AMD are higher.
Power and nuclear: Bloom Energy, X-energy, Oklo and NuScale are higher on the read that power and cooling, not chips, are the constraint on AI computing.
Upgrades: DigitalOcean (Piper), Zoom (Oppenheimer) and Northrop Grumman (Baird) were upgraded, and Robinhood and Costco picked up initiations.
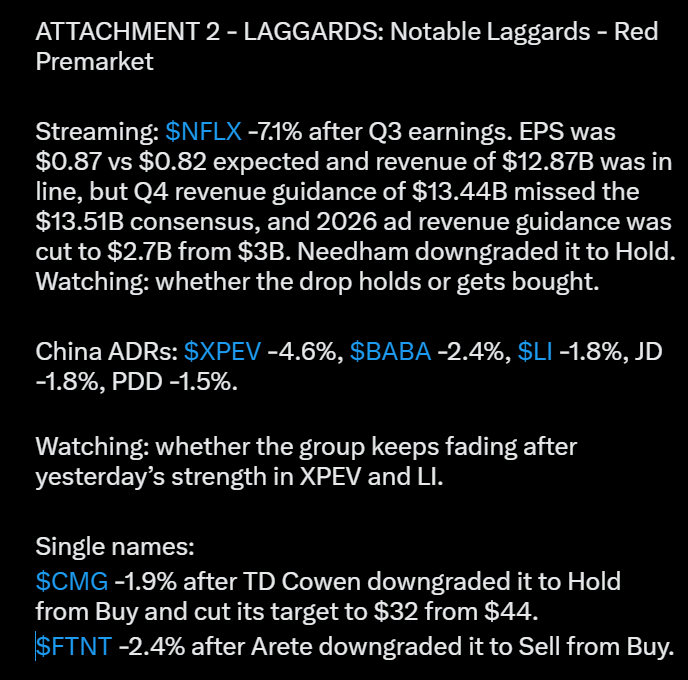
Netflix and China: NFLX is the biggest decliner on the board after earnings. China ADRs (BABA, JD, PDD, XPEV, LI) are lower.
We’re seeing relative strength in:
✅ AI hardware and servers (SMCI, DELL, HPE, VRT)
✅ SpaceX and Tesla (SPCX, TSLA)
✅ Neoclouds and miners (CRWV, IREN, NBIS, WULF)
✅ Semis and memory (MU, SKHY, INTC, NVDA)
✅ Power and nuclear (BE, XE, OKLO)
Weakness in:
❌ Netflix (NFLX)
❌ China ADRs (BABA, XPEV, LI)
❌ Chipotle (CMG)
❌ Fortinet (FTNT)
Watching closely: Whether the AI hardware rally from SpaceX and Super Micro can hold through the day and into Tesla, Meta and IBM earnings after the close, or whether oil and Hormuz headlines bring the selling back.
@TradersAscent
NOT FINANCIAL ADVICE
PRE-MARKET MOVERS | Tue Oct 20
$OXY $CVX $XOM $BP $PBR $PSX $WMT $KR $COST $PEP $KO $WM $LLY $NOW $XPEV $LI $SMR $OKLO $SKHY $NBIS $APLD $IREN $CIFR $CRWV $MU $SNDK $INTC $AMD $MRVL $SMCI $AAOI $AXTI $MARA $WULF $CLSK $RIOT $MSTR $IONQ $RGTI $FCX
Read-Through
Macro: Oil is the driver this morning. Iran’s Revolutionary Guards said mines halted two tankers in the Strait of Hormuz, and crude jumped more than 5% on the reports. The IRGC also said Tehran hasn’t fully closed the Strait and could widen the blockade to Bab al-Mandeb and the Suez Canal.
AI stocks bounced Monday (Nasdaq +1.1%, S&P 500 +0.4%, Dow -0.1%) after Friday’s worst week since June, and that bounce is being sold this morning.
Energy: The clear leader. Producers and majors are green, including OXY, CVX, XOM, BP, PBR and PSX, with XLE pushing into all time highs. Tankers (FRO, HAFN) are the exception and are lower.
Staples and value retail: A defensive bid is building in WMT, KR, COST, PEP and KO, along with WM and LLY. Discretionary retail and apparel are flat.
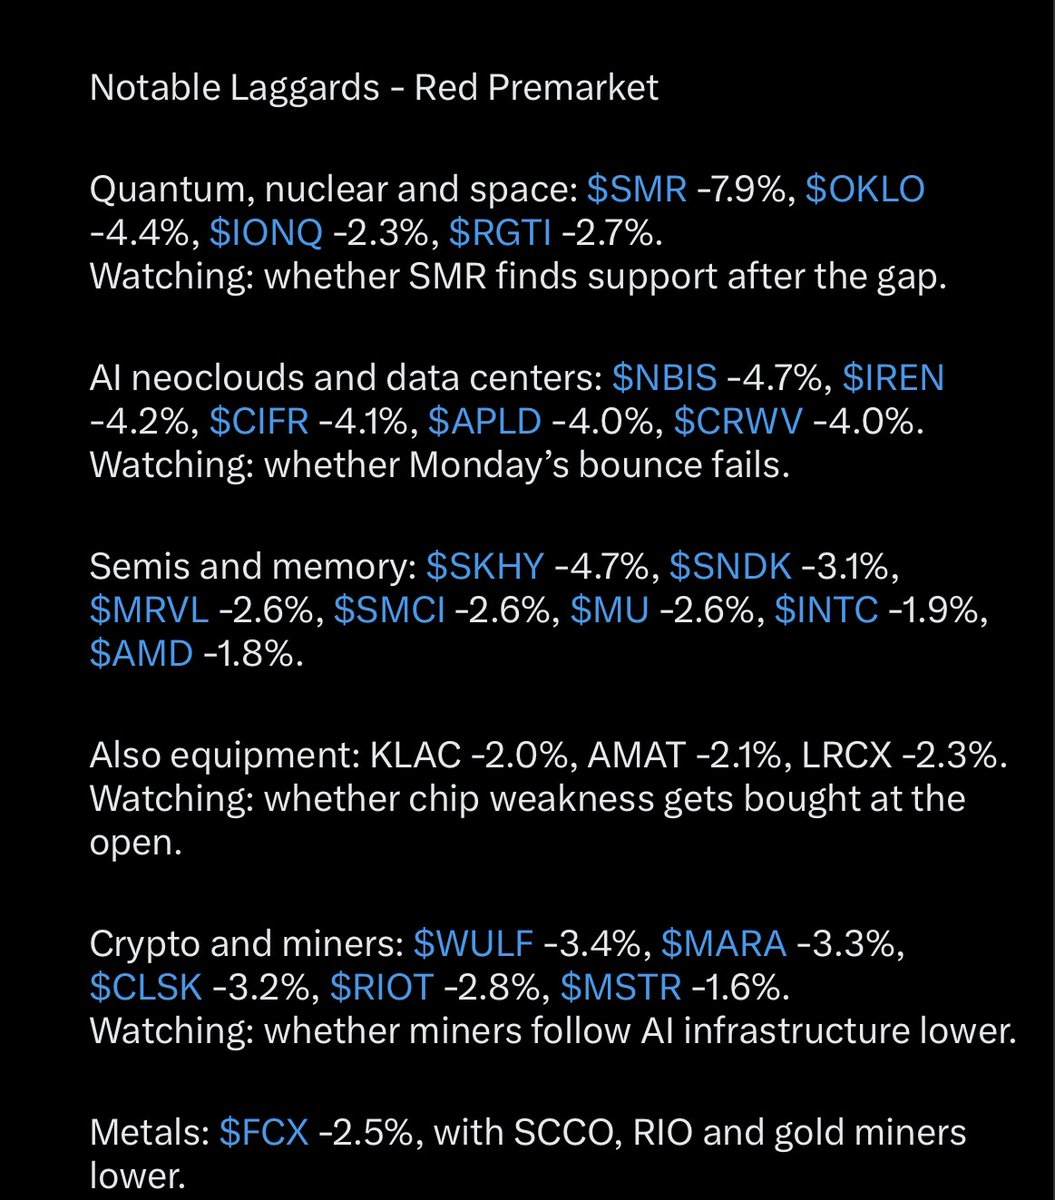
AI infrastructure and neoclouds: Giving back Monday’s bounce. CoreWeave, Nebius, IREN, Applied Digital and Cipher are all lower.
Semis and memory: Red across the board. SK hynix, Micron, Sandisk, Intel, AMD, Marvell and SMCI are down, along with equipment (KLAC, LRCX, AMAT).
Crypto and miners: Lower, including MARA, WULF, CLSK, RIOT and MSTR.
Quantum, nuclear and space: Weak. SMR is the largest decliner on the list, with OKLO, IONQ and RGTI also lower.
Metals and travel: Gold miners, copper (FCX, SCCO) and RIO are lower. Airlines and cruise lines are modestly lower with oil higher.
We’re seeing relative strength in:
✅ Energy producers and majors (OXY, CVX, XOM, BP)
✅ Staples and value retail (WMT, KR, COST, PEP)
✅ China EVs (XPEV, LI)
Weakness in:
❌ AI neoclouds and data centers (CRWV, NBIS, IREN, APLD, CIFR)
❌ Semis and memory (SKHY, MU, SNDK, INTC, AMD)
❌ Crypto and miners (MARA, WULF, CLSK, MSTR)
❌ Quantum and nuclear (SMR, OKLO, IONQ, RGTI)
❌ Metals and miners (FCX, gold miners)
Watching closely: Whether the oil spike turns into a broader risk-off day that keeps the AI bounce from holding, or whether energy and staples leadership stays contained while the rest of the market stabilizes into the open.
@TradersAscent
NOT FINANCIAL ADVICE
Every morning, 30 minutes before the open, I post charts with intraday inflection levels laid out as if/then scenarios for the people I trade with. The arrows are the roadmap - where I think price can go.
Left the arrows on today to show how they played out.
$AMZN gave me an 805% winner.
$SPY $QQQ $NVDA $GOOGL $MRVL
PRE-MARKET MOVERS | Mon Oct 19
$CRWV $NBIS $APLD $IREN $CIFR $WULF $MARA $CLSK $RIOT $MSTR $INTC $MU $SKHY $SNDK $AMD $MRVL $KLAC $LRCX $AMAT $ARM $SMCI $HPE $DDOG $NVDA $AMZN $IONQ $RGTI $ASTS $RKLB $XE $CLF $SMR $OKLO $XOM $CVX $OXY $BP $NOC $PYPL $MRNA
Read-Through
Macro: A bounce attempt after a rough Friday. The Nasdaq fell 2.1% and the S&P 500 fell 1.1%, their worst week since June, with chips leading the slide on worries over how long AI infrastructure spending can last. The Fed meets Oct 28.
AI infrastructure and neoclouds: The sharpest rebound on the board. CoreWeave, Nebius, IREN, Applied Digital and Cipher are all sharply higher after Friday’s double-digit drops.
Semis and memory: Broadly green. Intel, Micron, AMD, Marvell, SK hynix and Sandisk are higher, along with equipment (KLAC, LRCX, AMAT) and Arm.
Crypto and miners: Green, including MSTR, MARA, CLSK, RIOT, WULF and COIN. These names took the hardest hits Friday.
Quantum, nuclear and space: IONQ, RGTI, SMR, OKLO, ASTS and RKLB are all higher.
Software and cybersecurity: Mostly higher. DDOG, CRWD, PANW and NET are up, though most were hit hard Friday.
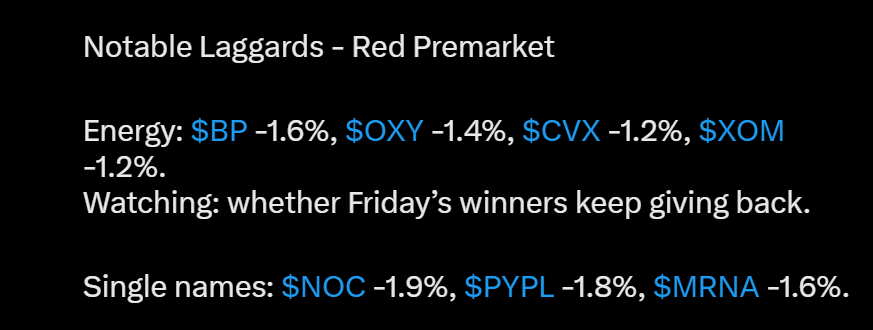
Energy: The one clearly red group. XOM, CVX, OXY and BP are lower after strong Friday sessions.
Idiosyncratic: NOC, PYPL and MRNA are lower.
We’re seeing relative strength in:
✅ AI neoclouds and data centers (CRWV, NBIS, IREN, APLD)
✅ Semis and memory (INTC, MU, AMD, SKHY)
✅ Crypto and miners (MSTR, MARA, WULF, CLSK)
✅ Quantum and space (IONQ, RGTI, RKLB)
Weakness in:
❌ Energy (XOM, CVX, OXY, BP)
❌ NOC
❌ PYPL
❌ MRNA
Watching closely: Whether this is a real reversal of Friday’s AI infrastructure selloff or just a bounce that gets sold this morning, and whether money rotating out of Friday’s energy winners and back into the hardest-hit growth names has any staying power.
@TradersAscent
NOT FINANCIAL ADVICE
$WMT $KO $PEP $PFE $LLY $JPM $BAC $NEM $AU $HL $XOM $CVX $HD $LOW $MA $RKLB $SKHY $MU $SNDK $WDC $INTC $NVDA $AMD $MRVL $TSM $VRT $DELL $CRWV $NBIS $IREN $APLD $CIFR $WULF $SMR $ONDS $IONQ $ORCL $SOFI $NET $PANW
Read-Through:
The risk-off move that started with Wednesday’s hot CPI is still running. Yesterday’s close was ugly in AI infrastructure and speculative tech (CRWV -15%, DOCN -15%, IREN -12%, WULF -13%, CORZ -12%, NBIS -10%, SMR -10%, DELL -11%, ORCL -9%, MRVL -9%), while defensives rallied (WMT +3.5%, COST +2.9%, KR +3.9%, LLY +3.6%, MRK +3.8%, UNH +4.7%).
This morning follows the same script: growth and speculative groups are lower and defensives are higher. Rates remain the backdrop, with the Fed meeting on October 28 (Coinpaper).
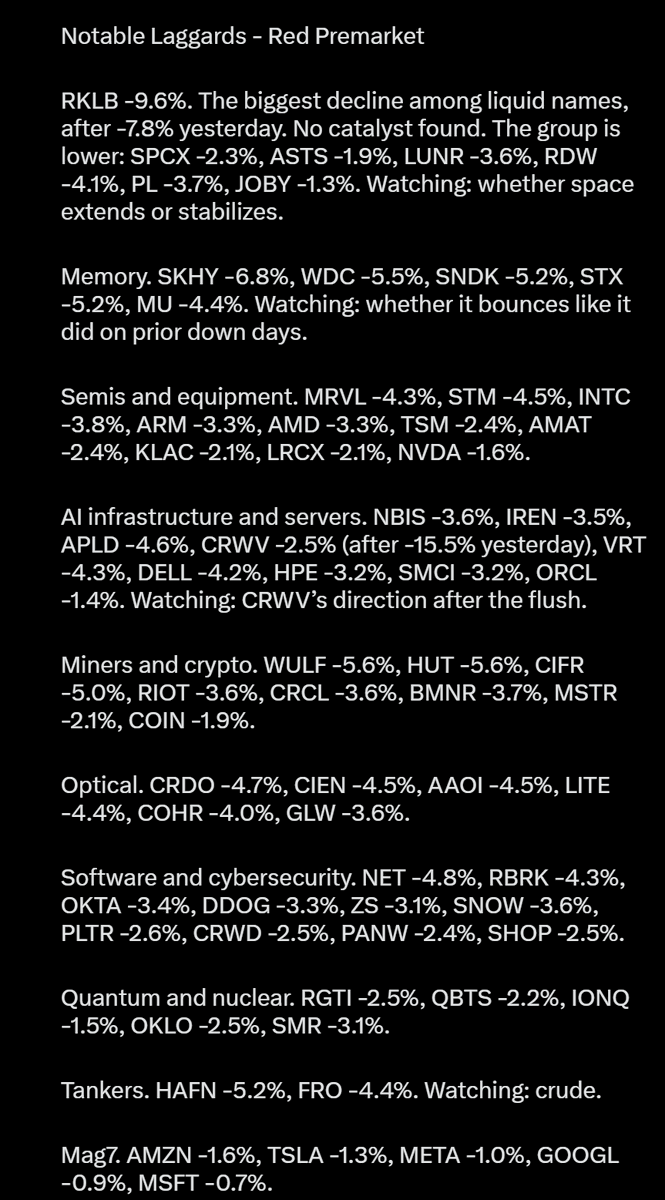
Space is the biggest percentage loser among liquid names. RKLB is down nearly 10% after falling 8% yesterday, and the group is red (ASTS, LUNR, RDW, JOBY, PL, SPCX). I could not find a catalyst for RKLB.
Memory is weak again. SKHY -6.8%, WDC -5.5%, SNDK -5.2%, STX -5.2%, MU -4.4%.
Chips and equipment are lower with them (INTC, AMD, MRVL, TSM, ARM, AMAT, LRCX, KLAC), and NVDA is down too.
AI infrastructure and miners are still under pressure. NBIS, IREN, APLD, CIFR, WULF, HUT, SMR and VRT are lower.
CRWV is only down about 2.5% but is trading with unusual relative volume after yesterday’s 15% flush, so it is worth watching for direction.
Software and cybersecurity are red as well (NET -4.8%, RBRK -4.3%, OKTA -3.4%, DDOG -3.3%, PANW -2.4%).
Optical, quantum and nuclear are also lower.
Where money is going:
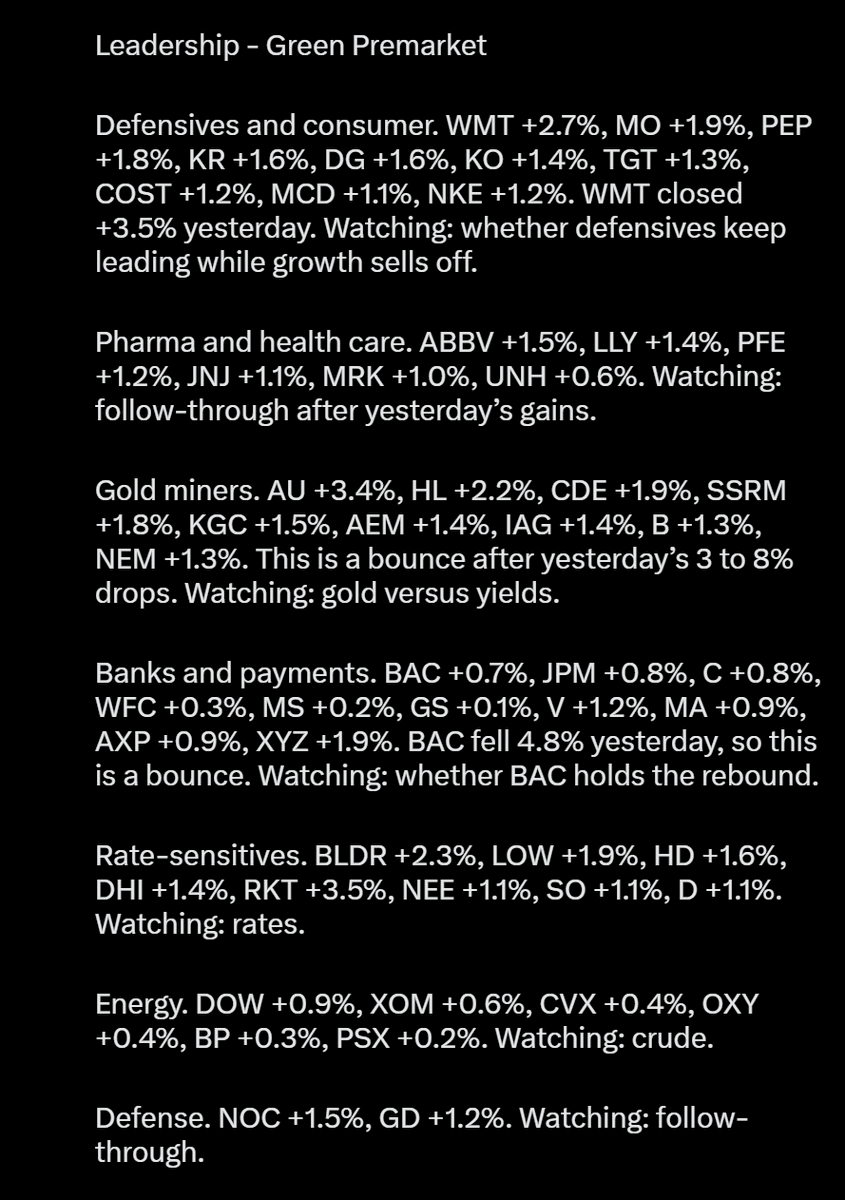
Defensives and consumer. Walmart and staples (WMT, COST, KR, KO, PEP, MO), pharma (PFE, LLY, MRK, ABBV, JNJ) and defense (NOC, GD) are all higher.
Gold miners are bouncing after yesterday’s 3 to 8% drops: AU +3.4%, HL +2.2%, CDE +1.9%, KGC +1.5%, NEM +1.3%.
Banks are rebounding modestly (BAC +0.7%, JPM +0.8%, C +0.8%) after BAC fell 4.8% yesterday on very heavy volume.
Rate-sensitives are higher: homebuilders and home improvement (BLDR, LOW, HD, DHI) and utilities (NEE, SO, D).
Energy is mildly green (XOM, CVX, OXY), but the tankers that ran this week are giving it back (FRO -4.4%, HAFN -5.2%).
The Mag7 is all red: AMZN, META, GOOGL, MSFT, TSLA and NVDA. China ADRs are red as well (BABA, BIDU, PDD).
We’re seeing relative strength in:
✅ Defensives and consumer: WMT, COST, KR, KO, PEP, MO
✅ Pharma and health care: PFE, LLY, MRK, ABBV, JNJ
✅ Gold miners: NEM, AU, AEM, HL, CDE
✅ Banks: BAC, JPM, C
✅ Homebuilders, home improvement and utilities: HD, LOW, BLDR, NEE, SO
✅ Energy: XOM, CVX, OXY
Weakness in:
❌ Space: RKLB, ASTS, LUNR, RDW
❌ Memory, chips and equipment: SKHY, MU, SNDK, WDC, INTC, AMD, MRVL, TSM
❌ AI infrastructure and miners: CRWV, NBIS, IREN, APLD, CIFR, WULF, VRT, DELL
❌ Software and cybersecurity: NET, RBRK, OKTA, PANW, DDOG
❌ Mag7, quantum, nuclear and tankers
Watching closely: whether the AI infrastructure and space unwind finds a floor after two heavy down days, or whether it extends while defensives, gold miners and banks keep leading.
I’m also watching whether the bounce in banks holds and whether the Mag7 can stop the slide.
@TradersAscent
NOT FINANCIAL ADVICE
$GOOGL $CVX $XOM $OXY $BP $FRO $ABBV $JNJ $GFS $ALB $WMT $KO $NOW $BABA $V $BAC $WFC $C $JPM $GS $MS $CRWV $HPE $DELL $NBIS $IREN $CIFR $SKHY $SNDK $WDC $MU $INTC $AMAT $NVDA $PANW $FTNT $ASTS $IONQ $META $COIN
Read-Through:
CPI came in a little hot this morning, and the tape has a mild risk-off tilt. The selling is broad but not violent. Defensives, energy and a few China names are green, while banks, AI infrastructure and rate-sensitives like gold miners are red.
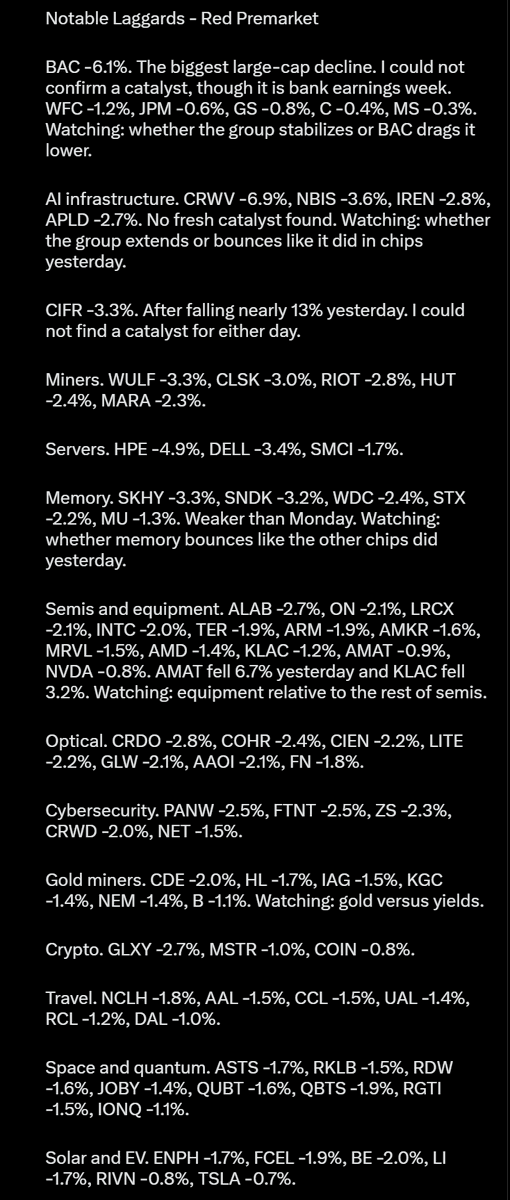
Banks are the headline. BAC is down more than 6% and the other majors are lower too: WFC, JPM, GS, C and MS. It is earnings week and the group has not been rewarded: yesterday C fell 5.6% and WFC fell 3.1%, even after GS gapped higher. I could not confirm what is driving BAC this morning.
AI infrastructure is under pressure again. CRWV is down nearly 7%, with NBIS, IREN and APLD lower as well, and the bitcoin miners are down with them. CIFR is lower again after falling nearly 13% yesterday. HPE and DELL are weak too, which points to AI hardware names as a group.
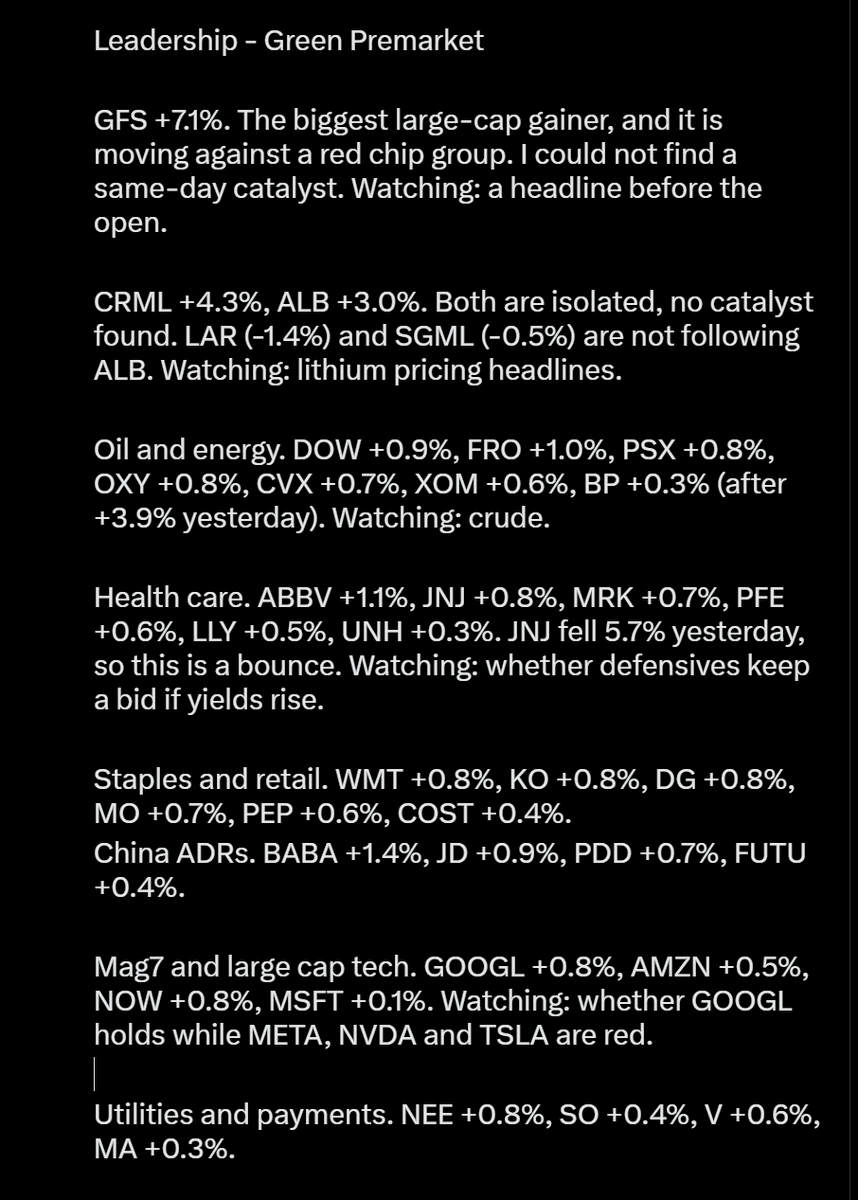
Chips are red but less severe than Monday. Memory is lower again (SKHY, SNDK, WDC, STX), with MU only slightly down. Equipment is the soft spot: AMAT fell 6.7% yesterday and is lower again. Worth noting: most big chip names bounced during yesterday’s session after weak premarkets (INTC +1.4%, AMD +1.9%, NVDA +1.0%). GFS is the exception today, up more than 7%, and I could not find why.
Hot CPI shows up in the rate-sensitive groups. Gold miners are lower (CDE, HL, NEM, KGC), cruise lines and airlines are red, and crypto is red across the board, majors included (COIN, MSTR, GLXY). Cybersecurity (PANW, FTNT, ZS, CRWD), solar and lidar are also weak.
Defensives and energy are holding up. Health care (ABBV, LLY, MRK, PFE, JNJ), staples (WMT, KO, PEP) and oil (CVX, XOM, OXY, PSX) are green. China ADRs (BABA, PDD, JD) are higher. Among the Mag7, GOOGL and AMZN are green while META, NVDA and TSLA are red.
We’re seeing relative strength in:
✅ Oil and energy: CVX, XOM, OXY, PSX
✅ Health care: ABBV, JNJ, LLY, MRK, PFE
✅ Staples and retail: WMT, KO, PEP, MO
✅ China ADRs: BABA, JD, PDD
✅ GOOGL and NOW
✅ Outliers: GFS, ALB, CRML
Weakness in:
❌ Banks: BAC, WFC, JPM, GS, C, MS
❌ AI infrastructure and miners: CRWV, NBIS, IREN, APLD, CIFR, HPE, DELL
❌ Memory and chip equipment: SKHY, SNDK, WDC, STX, AMAT, LRCX
❌ Crypto, including majors: COIN, MSTR, GLXY
❌ Gold miners, travel, cybersecurity and solar
Watching closely: whether the hot CPI turns a mild risk-off tilt into real follow-through selling, or whether dip buyers show up again like they did in chips yesterday.
I’m also watching whether banks stabilize after BAC, and whether defensives and energy keep their bids if rates push higher.
@TradersAscent
NOT FINANCIAL ADVICE
PRIVATE: FOR YOUR EYES ONLY
$UNH $GS $MS $BP $XOM $CVX $WMT $HD $V $CCL $NFLX $COIN $MSTR $GLXY $WFC $MU $SKHY $WDC $STX $SNDK $INTC $NVDA $AMD $MRVL $AVGO $AMAT $LRCX $CRWV $NBIS $IREN $APLD $CIFR $ASTS $ONDS $SHOP $META $CIEN $COHR $IONQ $HUT
Read-Through:
Rates are the new wrinkle this morning. TLT is bid and the 10-year yield (TNX) is pulling in. Yesterday's tape was oil up, yields up, chips down. Today yields are easing and chips are still getting hit, so the semiconductor and memory weakness looks more like a group problem than a rates problem.
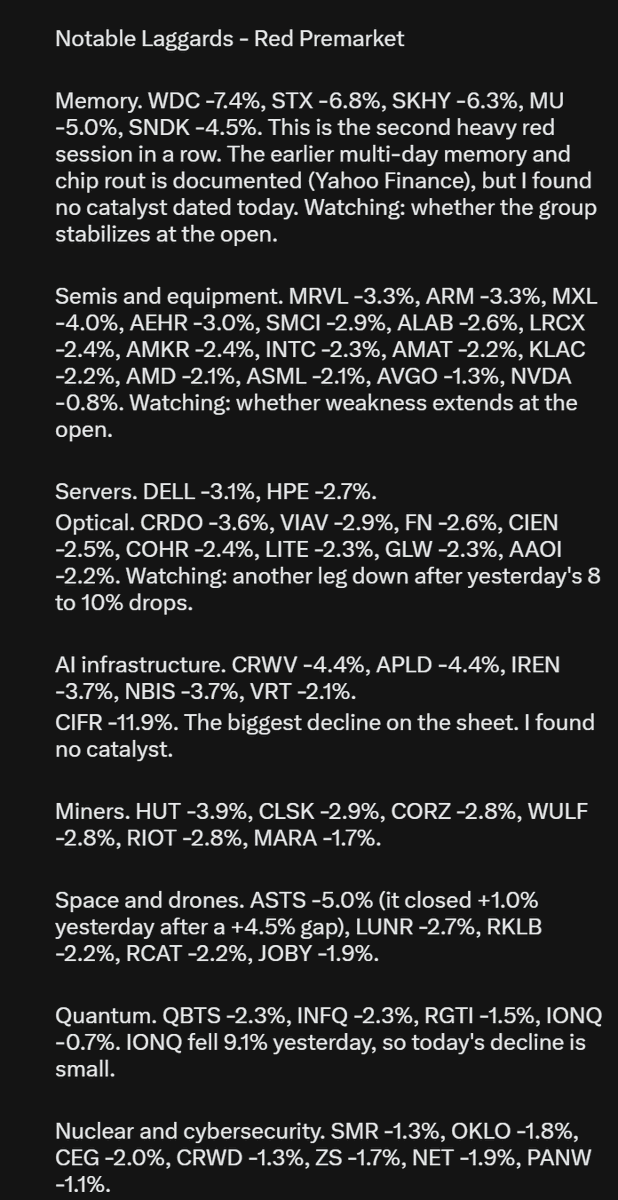
Monday's close sets the stage. Optical and AI hardware took the worst of it, with CIEN, LITE, COHR, VIAV and AAOI each down roughly 8 to 10% on the session, and the follow-through is red again this morning.
Memory is the weakest group on the sheet. STX -6.8%, WDC -7.4%, SKHY -6.3%, MU -5.0%, SNDK -4.5%. That is every memory and storage name down hard together. Broader semis and equipment are red across the board, and servers (DELL, HPE, SMCI) are down too. The few semi exceptions, NVTS and TSEM, are small moves.
AI infrastructure is under pressure. Neoclouds, data center names and bitcoin miners are down together: CRWV, APLD, IREN, NBIS, HUT. CIFR is the outlier at -11.9% on 3.1M shares, and I could not find a catalyst for it. Optical, quantum, nuclear, space and drones, cybersecurity and solar are also red. Software leans red but on thin volume.
Money is rotating toward rate-sensitive and defensive groups. Utilities, homebuilders and home improvement, retail and staples, cruise lines and airlines, and gold miners are all green, which fits falling yields. Oil and energy lean green (BP, XOM, CVX, OXY), while the tankers that ran yesterday (FRO, HAFN) are giving some back.
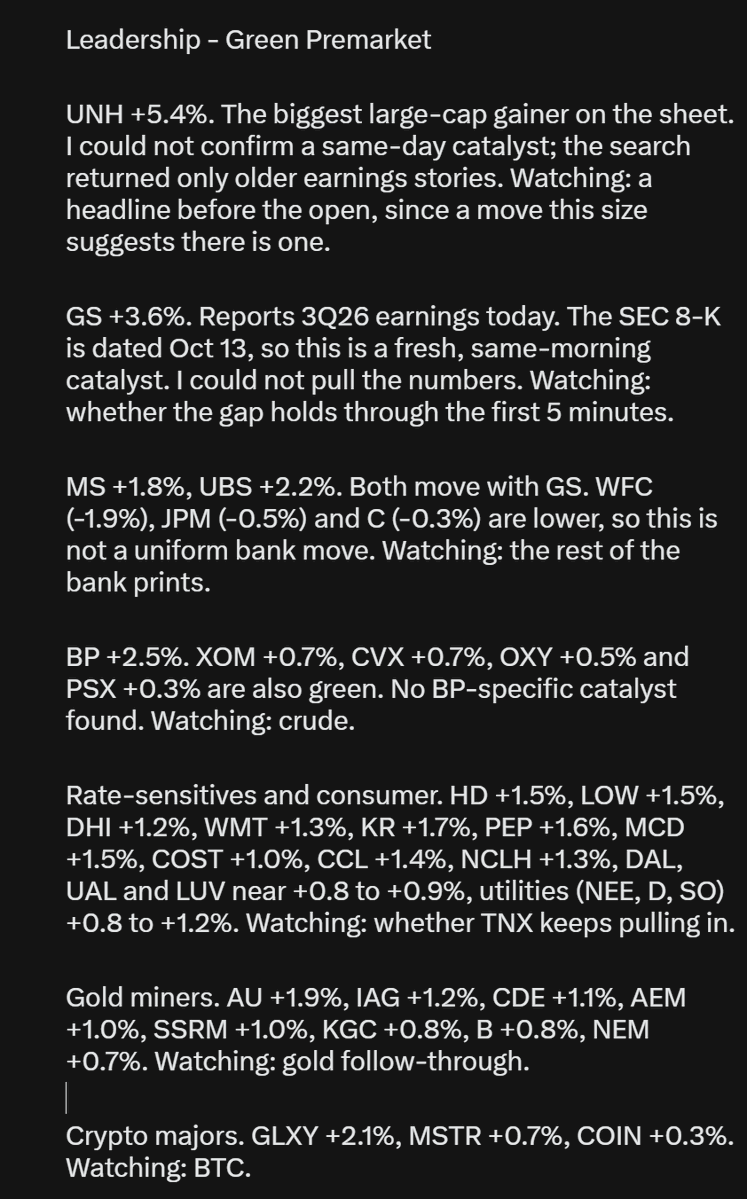
Earnings season has started. GS is up 3.6% and reports today. UBS, MS and V are green, while WFC, JPM and C are lower, so banks are showing dispersion rather than a group move. UNH is up 5.4% on heavy volume.
Crypto is split again. Majors are green (GLXY, MSTR, COIN) while miners are red.
We're seeing relative strength in:
✅ Banks with earnings: GS, MS, UBS
✅ Health care: UNH
✅ Oil and energy: BP, XOM, CVX, OXY
✅ Rate-sensitives: utilities, homebuilders, home improvement
✅ Retail, staples and travel: WMT, KR, PEP, MCD, CCL, NCLH, airlines
✅ Gold miners: AU, AEM, IAG, CDE
✅ Crypto majors: GLXY, MSTR, COIN
Weakness in:
❌ Memory and storage: STX, WDC, SKHY, MU, SNDK
❌ Semis, chip equipment and servers: MRVL, ARM, AMAT, LRCX, INTC, AMD, DELL, HPE
❌ Optical: CRDO, CIEN, COHR, LITE, VIAV
❌ AI infrastructure and miners: CRWV, APLD, IREN, NBIS, CIFR, HUT
❌ Space, quantum, nuclear and cybersecurity
Watching closely: whether chips and memory keep sliding even with yields easing, since that would confirm the pressure is sector-specific.
Whether falling yields (TLT up, TNX lower) are enough to stop the chip and memory selloff at the open, or whether money keeps rotating from tech into banks and rate-sensitives.
I'm also watching bank earnings follow-through and whether the rate-sensitive groups hold as tech weakens.
@TradersAscent
NOT FINANCIAL ADVICE
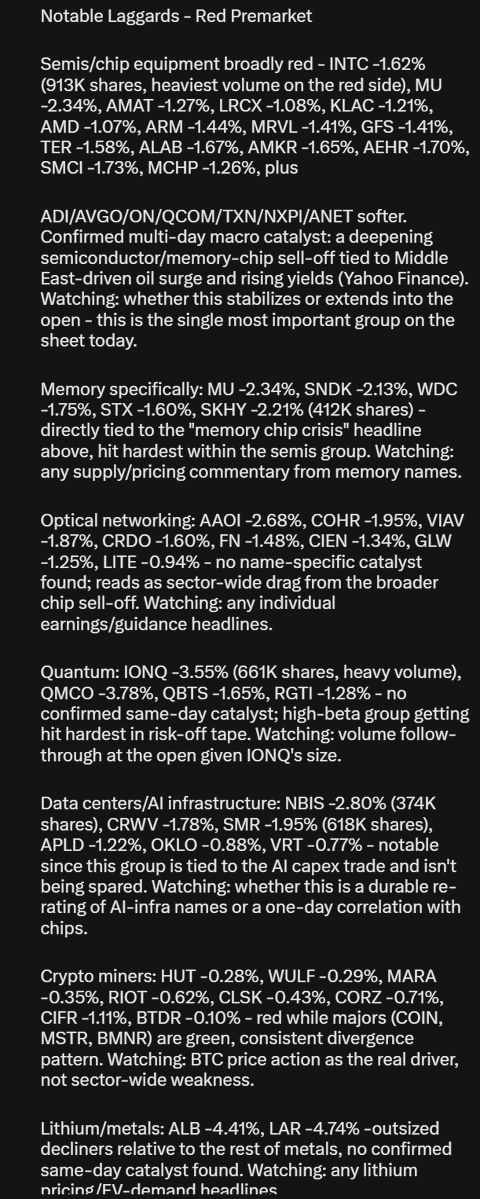
$IREN $AI $FRO $ASTS $FSLR $ONDS $NOW $FTNT $BMNR $BP $PSX $OXY $PBR $COIN $MSTR $CRCL $GLXY $HUT $WULF $MARA $RIOT $INTC $MU $AMAT $LRCX $KLAC $AMD $ARM $MRVL $SNDK $WDC $AAOI $COHR $IONQ $QMCO $NBIS $SMR $SOFI $ALB $LARRead-Through:
The dominant story this morning is a deepening semiconductor rout running alongside a geopolitical-driven oil spike - Wall Street has been sliding for several sessions now as chip stocks lead the tech sell-off amid a "memory chip crisis" and Middle East tensions push crude higher and lift Treasury yields (Yahoo Finance, Barchart). That's the lens for nearly everything red on the sheet this morning.
Semis/chip equipment broadly red - this is the single biggest theme on the sheet. INTC -1.62% (913K shares, heaviest volume on the red side), MU -2.34%, AMAT -1.27%, LRCX -1.08%, KLAC -1.21%, AMD -1.07%, ARM -1.44%, MRVL -1.41%, GFS -1.41%, TER -1.58%, ALAB -1.67%, AMKR -1.65%, AEHR -1.70%, SMCI -1.73%, MCHP -1.26%, plus ADI, AVGO, ON, QCOM, TXN, NXPI and ANET all softer. Memory specifically is getting hit hardest within that: MU -2.34%, SNDK -2.13%, WDC -1.75%, STX -1.60%, SKHY -2.21% (412K shares) - directly consistent with the "memory chip crisis" headline.
Optical networking also broadly red: AAOI -2.68%, COHR -1.95%, VIAV -1.87%, CRDO -1.60%, FN -1.48%, CIEN -1.34%, GLW -1.25%, LITE -0.94% - no name-specific catalyst found for most of these; this reads as the chip-sector-wide pullback dragging the whole group.
Quantum broadly red: IONQ -3.55% (661K shares, heavy volume), QMCO -3.78%, QBTS -1.65%, RGTI -1.28% - again no fresh name-specific news, this looks like high-beta/speculative names getting hit hardest in the same risk-off tape.
Data centers/AI infrastructure broadly red: NBIS -2.80% (374K shares), CRWV -1.78%, SMR -1.95% (618K shares), APLD -1.22%, OKLO -0.88%, VRT -0.77% - notable because this is the group most tied to the AI capex story, and it's not being spared from the chip-sector weakness.
Oil/energy clearly green and the other side of today's macro coin: BP +1.56%, PSX +1.19%, OXY +1.15%, PBR +1.03%, CVX +0.94%, XOM +0.92% - tracking the crude spike tied to Middle East/Strait of Hormuz tension that's also pressuring yields and weighing on growth/tech (Nasdaq).
Crypto split persists: majors green (COIN +0.76%, MSTR +0.73%, BMNR +1.75%, CRCL +0.57%, GLXY +0.44%) while miners stay red (HUT -0.28%, WULF -0.29%, MARA -0.35%, RIOT -0.62%, CLSK -0.43%, CORZ -0.71%, CIFR -1.11%, BTDR -0.10%) - the same majors-vs-miners divergence we've flagged on prior days.
Software/cybersecurity leaning green: NOW +2.09%, FTNT +0.98%, DDOG +0.63%, CRWD +0.63%, MDB +0.62%, ZS +0.54%, PANW +0.53%, TWLO +0.50% - a pocket of relative strength even as hardware/semis sell off.
Metals mixed, lithium notably weak: ALB -4.41% and LAR -4.74% stand out as outsized decliners; gold miners broadly soft but not dramatic (AEM -1.39%, NEM -0.91%, AU -0.70%, KGC -0.80%, HL -0.82%, B -0.83%, CDE -0.76%, SSRM -0.54%).
Space/drones mixed: ASTS +3.82% and ONDS +2.97% both green on heavy volume, SPCX +0.97% also green, but RKLB -0.89%, JOBY -1.11%, ACHR -0.69%, RCAT -0.35%, RDW -0.10% red - no clean sector-wide direction here, these look more name-specific.
Individual standouts on the leadership side:
IREN +3.92% (2.53M shares - by far the heaviest volume on the whole sheet) and AI (https://t.co/CHeMm1NmaA) +3.90% are the two biggest % gainers. I could not confirm a same-day, dated catalyst for either this morning - IREN's known recent catalysts (Nvidia/AI Cloud contract news) are from prior sessions and should be treated as already priced in rather than fresh; this move looks like continued momentum/short-covering in the name rather than new news. Same caveat on AI/C3.ai -no fresh same-day headline found, treat as sector-momentum, not news-driven.
I'd flag SOFI's volume again : -1.84% on 3.1M shares is, like several prior sessions, wildly disproportionate volume for the size of the move. Still no confirmed catalyst found. Worth digging into if you trade it.
Watching closely:
whether the semiconductor/memory rout stabilizes or accelerates into the open - this has been a multi-day deepening story, not a one-day wobble,
and oil/yields are the read-through to watch for confirmation either way.
Also watching the crypto majors-vs-miners split and whether oil/energy strength holds if tanker/Hormuz headlines escalate further.
@TradersAscent
NOT FINANCIAL ADVICE
The amount you can build just by deciding it matters can’t be overstated. Trading’s upside has no ceiling, and neither does yours…if you stop treating it like a side hobby and start treating it like a skill worth mastering.
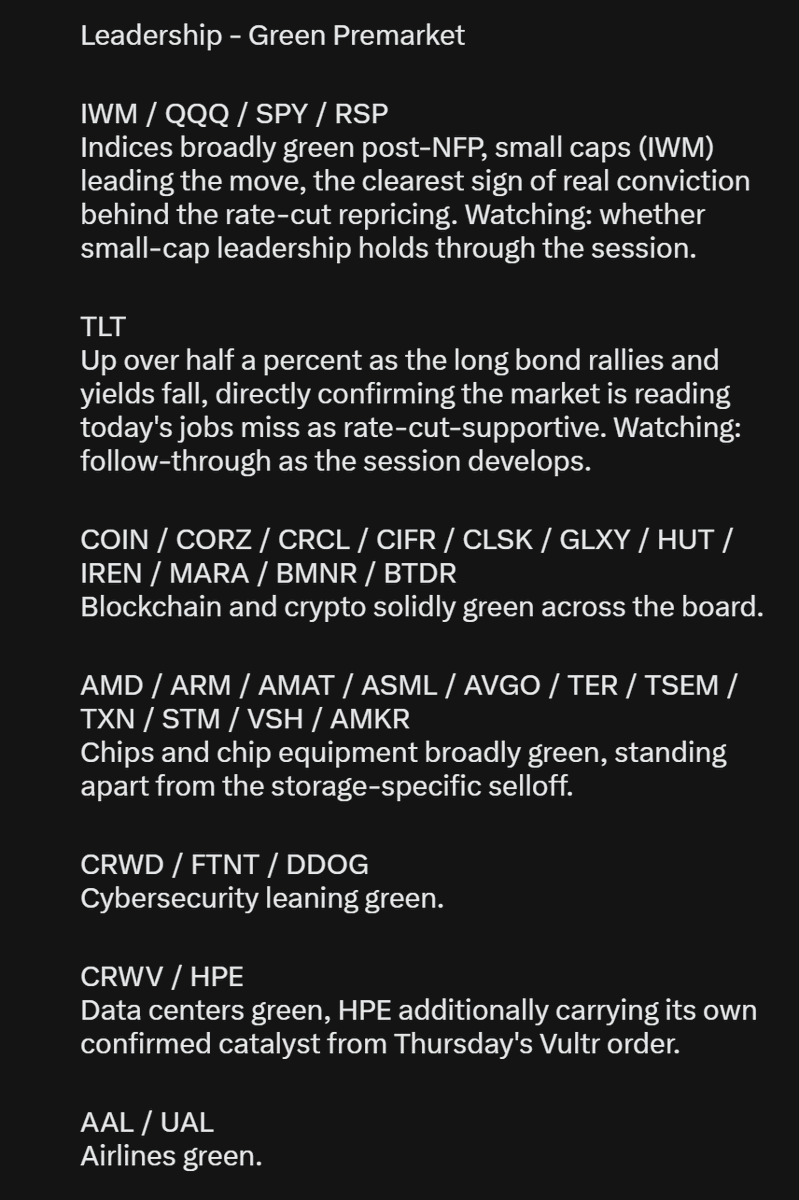
Pre-Market Movers - Friday October 2 2026
$QQQ $SPY $IWM $RSP $TLT $STX $WDC $SNDK $APP $AMD $ARM $AMAT $ASML $AVGO $TER $TSEM $TXN $STM $VSH $AMKR $COIN $CORZ $CRCL $CIFR $CLSK $GLXY $HUT $IREN $MARA $BMNR $BTDR $CRWD $FTNT $DDOG $CRWV $HPE $AAL $UAL $XOM $BP $BABA $XPEV $VIX
Read-Through:
September's jobs report landed soft across nearly every line, payrolls up just 29,000 against a 90,000 estimate, August revised down from 162,000 to 133,000, unemployment ticking up to 4.2%, and wage growth cooling too.
The market's reaction confirms exactly what that combination usually means: indices are broadly green, with small caps leading, IWM up over 1.6%, well ahead of QQQ and SPY, and the long bond is rallying too, TLT up more than half a percent as yields fall on rising rate-cut expectations.
This is now a genuine broad-market move, not a handful of rate-sensitive pockets, nearly everything that was flat or mixed earlier this morning has turned solidly green.
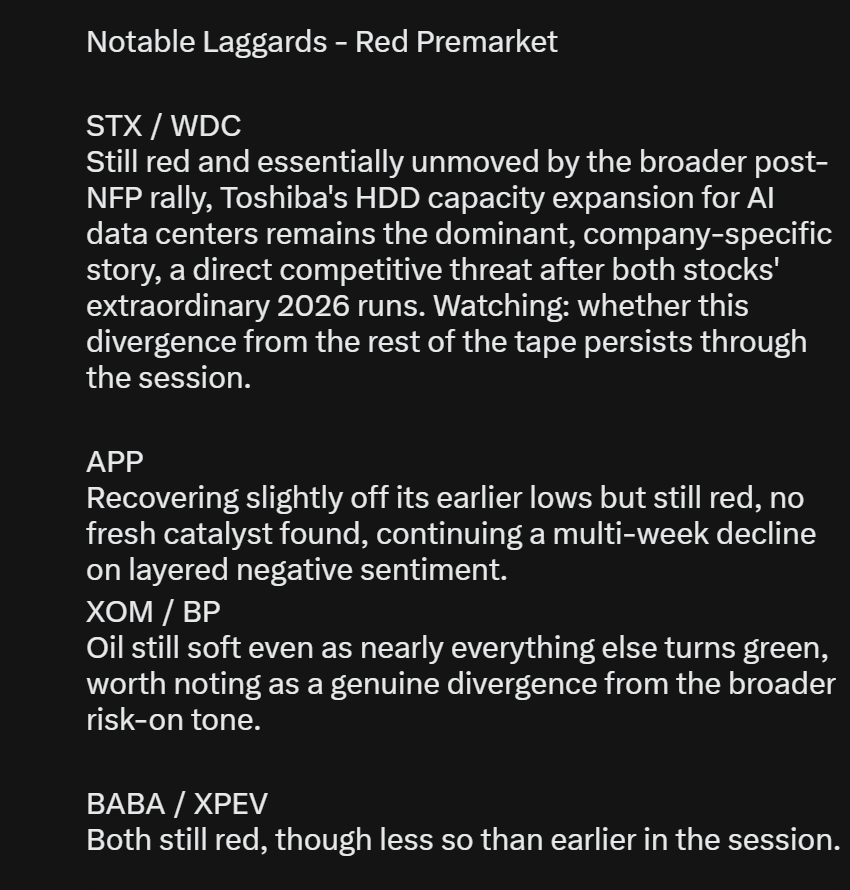
Storage remains the clear exception, and the fact that it hasn't budged with the rest of the tape says something. Toshiba's announced hard disk drive capacity expansion for AI data centers is still weighing on Seagate and Western Digital exactly as hard as it was before the jobs data, Seagate is actually slightly more negative now, and SanDisk is lower with them.
That's a real tell that this is a company-and-sector-specific story, not something a dovish macro print can offset. AppLovin has recovered a little off its earlier lows but remains the other clear laggard, still no fresh catalyst behind the move.
Full catalyst breakdown in the attached images.
We're seeing relative strength in:
✅ Indices broadly green, small caps leading - IWM, QQQ, SPY, RSP
✅ TLT up on falling yields, confirming the dovish read on the jobs data
✅ Blockchain and crypto solidly green across the board - COIN, CORZ, CRCL, CIFR, CLSK, GLXY, HUT, IREN, MARA, BMNR, BTDR
✅ Chips and chip equipment broadly green - AMD, ARM, AMAT, ASML, AVGO, TER, TSEM, TXN, STM, VSH, AMKR
✅ Cybersecurity leaning green - CRWD, FTNT, DDOG
✅ Data centers green - CRWV, HPE
✅ Airlines green - AAL, UAL
Weakness in:
❌ STX / WDC - unmoved by the broader rally, Toshiba's HDD capacity expansion still the dominant story for storage
❌ SNDK - lower alongside the storage complex
❌ APP - recovering slightly but still red, no fresh catalyst found
❌ XOM / BP - oil still soft even as nearly everything else turns green
❌ BABA / XPEV - both still red, though less so than earlier
Watching closely:
Whether small caps' outperformance (IWM leading QQQ and SPY) holds through the session as the cleanest read on how much conviction is behind this rate-cut repricing.
Whether storage's refusal to participate in the rally is a warning sign for the rest of memory or stays contained to Seagate and Western Digital specifically.
And whether oil's continued weakness even on a broad risk-on morning says something about demand expectations. @TradersAscent
NOT FINANCIAL ADVICE