State-owned #LNG giant @qatarenergy expects the damage to two liquefaction trains at its giant Ras Laffan complex to take three years to repair, according to Qatar’s energy minister and CEO of QatarEnergy, Saad Sherida Al-Kaabi. #lngprime https://t.co/QmJGGwdOec
Diesel is done flying under the radar. $6.27 a gallon today. Gasoline is $4.33. One is up 70% in a year, the other 36%. Obviously neither is ideal, but that gap tells us we have a refining shock rather than a crude shock.
WTI settled at $105.83, which is $2.52 of every gallon. The diesel crack spread is above $110 a barrel this week, another $2.71 per gallon. Half the wholesale price of diesel is now a refining premium. (Normal year is $20 to $30)
For the forseeable future— the world has lost its distillate makers. In August, diesel exports were 390,000 b/d, a quarter of prewar volumes. Three of Russia's six largest diesel refineries are dead in the water. Global refinery throughput is 4.2 million b/d below last year.
U.S. refineries are at 97.8% — they have zero headroom for production.
Washington's tools are crude and gasoline tools. The SPR puts crude into refineries that cannot run harder; the winter-gasoline waiver helps gasoline. The only diesel lever is restricting the 1.56 million b/d we export, which trades a short domestic discount for lower refinery runs— not to mention a tighter global market.
Inventories also point the wrong way. East Coast distillate stocks are 28% below last year. EIA's outlook, with inputs finalized September 3, already had national stocks below the five-year low through most of 2027. That was a week before the Saudi East-West pipeline, (their last export lifeline) was hit and taken offline.
Demand is giving way on the margins. Distillate consumption is 2.6% below last year. With refineries maxed and imports at 185,000 b/d, any easing from here comes from less consumption. Even that isn’t a fix but rather a mechanism of recession.
Pass-through inflation is here, and will not slow anytime soon. Diesel producer prices rose 24% in August alone. FedEx ground is at a 28% fuel surcharge, Union Pacific intermodal at 56%.
The US panicked when diesel hit a record $6 a gallon last week; we are already at $6.27– and rising. Don’t blame refiners, their profits are a symptom of scarcity, not the cause; retail fuel margins fell 11% last month.
Where does this land for those considering Natural Gas power over diesel? $6.27/gallon is equivalent to $45/MMBtu! Henry Hub is at $3. Largely flat since the war broke out.
Every behind the meter diesel deployment now buys energy through the tightest bottleneck in the global system— marginal refining capacity— now within drone range of two wars, neither with an end in sight. American natural gas never touches them, and there is no crack spread on methane.
LNG exports tie it to global prices at the margin, but Henry Hub is not sealed off from the world. There there is no refinery between the wellhead and the burner tip. Pipeline gas where there is pipe. LNG/CNG by truck where there isn't. That is the business we are in, and the past quarter has decidedly settled the economics debate.
Diesel is done flying under the radar. $6.27 a gallon today. Gasoline is $4.33. One is up 70% in a year, the other 36%. Obviously neither is ideal, but that gap tells us we have a refining shock rather than a crude shock.
WTI settled at $105.83, which is $2.52 of every gallon. The diesel crack spread is above $110 a barrel this week, another $2.71 per gallon. Half the wholesale price of diesel is now a refining premium. (Normal year is $20 to $30)
For the forseeable future— the world has lost its distillate makers. In August, diesel exports were 390,000 b/d, a quarter of prewar volumes. Three of Russia's six largest diesel refineries are dead in the water. Global refinery throughput is 4.2 million b/d below last year.
U.S. refineries are at 97.8% — they have zero headroom for production.
Washington's tools are crude and gasoline tools. The SPR puts crude into refineries that cannot run harder; the winter-gasoline waiver helps gasoline. The only diesel lever is restricting the 1.56 million b/d we export, which trades a short domestic discount for lower refinery runs— not to mention a tighter global market.
Inventories also point the wrong way. East Coast distillate stocks are 28% below last year. EIA's outlook, with inputs finalized September 3, already had national stocks below the five-year low through most of 2027. That was a week before the Saudi East-West pipeline, (their last export lifeline) was hit and taken offline.
Demand is giving way on the margins. Distillate consumption is 2.6% below last year. With refineries maxed and imports at 185,000 b/d, any easing from here comes from less consumption. Even that isn’t a fix but rather a mechanism of recession.
Pass-through inflation is here, and will not slow anytime soon. Diesel producer prices rose 24% in August alone. FedEx ground is at a 28% fuel surcharge, Union Pacific intermodal at 56%.
The US panicked when diesel hit a record $6 a gallon last week; we are already at $6.27– and rising. Don’t blame refiners, their profits are a symptom of scarcity, not the cause; retail fuel margins fell 11% last month.
Where does this land for those considering Natural Gas power over diesel? $6.27/gallon is equivalent to $45/MMBtu! Henry Hub is at $3. Largely flat since the war broke out.
Every behind the meter diesel deployment now buys energy through the tightest bottleneck in the global system— marginal refining capacity— now within drone range of two wars, neither with an end in sight. American natural gas never touches them, and there is no crack spread on methane.
LNG exports tie it to global prices at the margin, but Henry Hub is not sealed off from the world. There there is no refinery between the wellhead and the burner tip. Pipeline gas where there is pipe. LNG/CNG by truck where there isn't. That is the business we are in, and the past quarter has decidedly settled the economics debate.
THE QUANTUM INTERNET IS COMING
Remember when I said China leads the quantum network race? The US just answered twice in the same week.
Result one: Stony Brook and Brookhaven National Lab sent quantum information through open air across 13 miles. No cable at all. The first US demonstration of its kind.
Result two: a NIST led team transmitted entangled photons across 62 kilometers of fiber. Not lab fiber but an existing, ordinary, already in the ground telecom cable. The toughest real world test the quantum internet has passed.
Why both are hard: entanglement is the resource that makes quantum networks work, and it's absurdly fragile. Temperature, vibration, atmosphere, the noise of regular traffic in nearby fibers, all of it destroys quantum states. Getting them through 38 miles of commercial cable, or 13 miles of open sky is a massive feat.
But kilometers aren't the whole story.
China's famous 12,000 km quantum backbone runs on an older architecture, trusted relay nodes. Every few hundred kilometers the signal stops, gets measured, gets re-sent.
What NIST demonstrated is the next architecture which is entanglement over real infrastructure, end to end, no trusted middlemen. And it rides fiber that's already underground. Every telecom on earth already owns the hard part.
What Stony Brook demonstrated is the path off the ground entirely. Free space links are the stepping stone to quantum satellites, the one domain China has monopolized since Micius launched (Though its had its problems).
So overall, China built more kilometers of the old design over a decade. The US just demonstrated the new design on buried cable AND in open air, in seven days.
This race has just begun.
$IONQ $RGTI $INFQ $QBTS
No one wants this to be true more than I, the idea that the world has a ‘peacetime glut’ right now, is a phenomenal prospect indeed.
But, do we believe it? Will this idea materialize/have impact on September’s expected chaos?
MUST READ: Middle Eastern oil producers are pressing ahead with shuttling large volumes of crude out of the Persian Gulf, despite renewed Iranian attacks.
https://t.co/qvHvbwpnH1
The same is going to happen in the US, my guess is 'material impact' felt by 2030-2032, its a race to build infrastructure until then.
If the economics for your charging or refueling solution are there, it's a no-brainer.
CNG powered Cummins X15N - 8-12mpg (dge- blended!)
If charging and operational geography is economical, dge mpg is even higher with EVs, CEVs
The same is going to happen in the US, my guess is 'material impact' felt by 2030-2032, its a race to build infrastructure until then.
If the economics for your charging and/or refueling solution are there, it's a no-brainer.
CNG powered Cummins X15N - 8-12mpg (dge- blended!)
If charging and operational geography is economical, dge mpg is even higher with EVs, CEVs
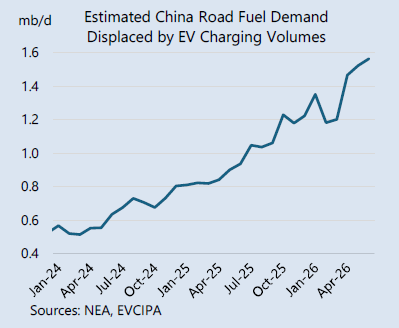
CHART OF THE DAY: @IEA estimates Chinese EV fleet (cars + trucks) is displacing >1.5m b/d of oil demand (up from ~1m b/d) a year ago.
"This displacement [...] suggests an acceleration in the already very strong growth in the use of electricity for transportation," the IEA said.
@JavierBlas Tbf— depends how crucial/sustainable that ‘1B barrel stockpile’ was to their effort in cutting 5m b/d, comfortably, can they flex such muscle easily in the future?
@JavierBlas Well researched & written, more and more think the Hormuz gets bypassed overnight— anyone predicting pre-2035—please elaborate how that is possible without Iranian cooperation?
Until such time as Hormuz is bypassed, “China is the new OPEC” is almost inarguable?
Wild.