Mohit Ulva turns the impossible into reality! 👌
A sensational unbeaten knock to take India to the U19 Asia Cup title in the most dramatic fashion.
#SonySportsNetwork#SonyLIV#PAKvIND
Why trailing PE is among the most useless metrics for decision making.
I will not enter into comparison, since I have not studied Pradeep Metals.
There are multiple ways to evaluate risk reward for entry consideration.
One basis for entry decision could be on forward PE considerations., and impact on capex / scale up from current base as well at absolute level.
Trailing PE may seem high because they expected impact on base could be large.
Mind it, sharing numbers for illustrative purpose only, as an example for process.
And this is not a A is better / worse than B comparison. Just as an example.
In fact, the Union Minister connection with Pradeep Metals could expedite a lot of things and rocket the valuation.
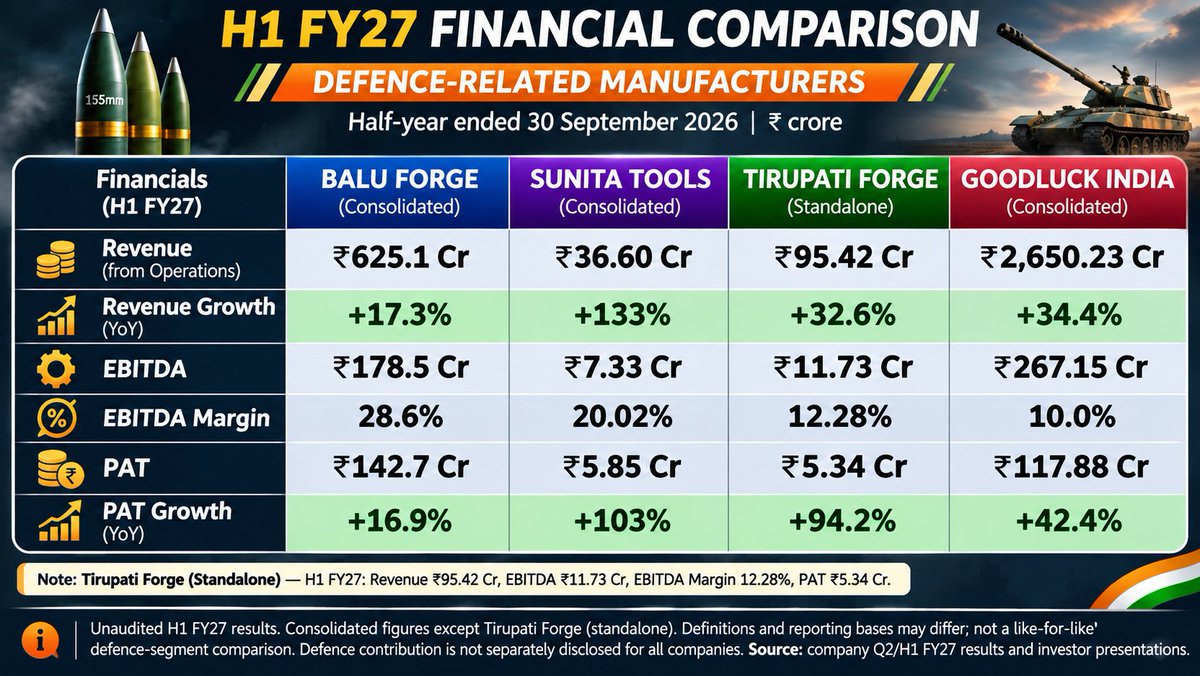
A) Sunita Tools:
FY26 Rev: 46 cr
FY27E
Rev: 60-70 (core) + 50/75/100 - basis 2/3/4 months of shell revenue realization (thus valuation be adjusted according to delays)
~120 - 160 cr Rev
@ 16-18% PAT: 20 - 28
FY28E
Revenue (assuming shells are in production)
= 90-100 (core) + 250-300 (shells)
= 350-400 cr
@ 18% PAT = 63 - 70 cr
@ Market cap = 670 cr
FY27E PE = 24-34
FY28E PE = 9-11
FY29E PE = far fetched
B. Pradeep Metals
(I have not assessed the business - hence make adjustments basis your understanding)
FY26 Rev = 338
Assuming FY27 timely execution and 2 year to scale to 80% capacity util & 40% in year 1 (FY28)
FY27E Rev = 370-380 (10-12% core growth growth)
PAT @ 9% (though this will likely be impacted due to the capex)
FY27E PAT = 34
FY28E Rev = 420 + 150 cr (assuming 25 cr per 10k shells, 40% util and timely approvals)
Say PAT @ 10% from 9%,
FY28E PAT = 57 cr
FY29E Rev = 450-60 + 300 (assuming 80% util) = 750-760
Say PAT at 12% as the shell scales up and proportion to revenue is also higher
FY29E PAT = 90 cr
@ Mcap of 940 cr
FY27E PE = 27-28
FY28E PE = 16-17
FY29E PE = 10-11
^if due to the connection, it hits 80% shell factory utilization in FY28, then FY28E PE will likely be closer to 11-12
Now, make adjustments basis your business understanding and forward valuation expectations for risk-reward
Discl.
Do your Due Diligence.
Sharing for illustrative and study purpose only: on forward valuation basis business outlook and probability
Share your thoughts and counter-thoughts
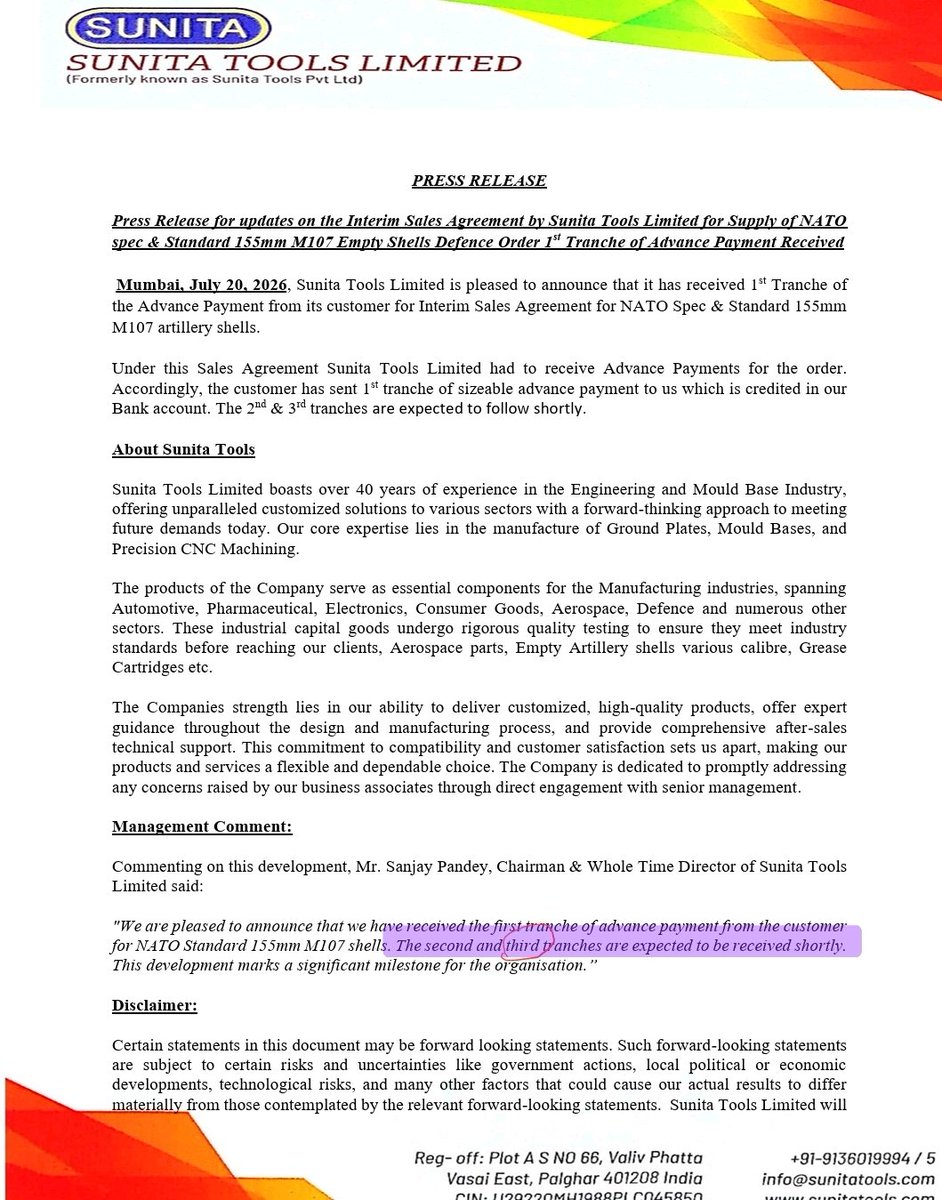
@ankurjain83@Kourav123@Chirag68158004@SidNayak7 Developments happen, sometimes not at the speed it should.process is clear.That only after testing their product, receiving the advance & subsequently the dp02, orders will be delivered. There was a delay in picking the prototype by customer due to the war.
@Kourav123@Chirag68158004@SidNayak7@ankurjain83 Where is it mandated that the advance amount needs mentioning in the notification. Leave that to the promoter, he knows better than most. When he has to reveal , he will...so chill
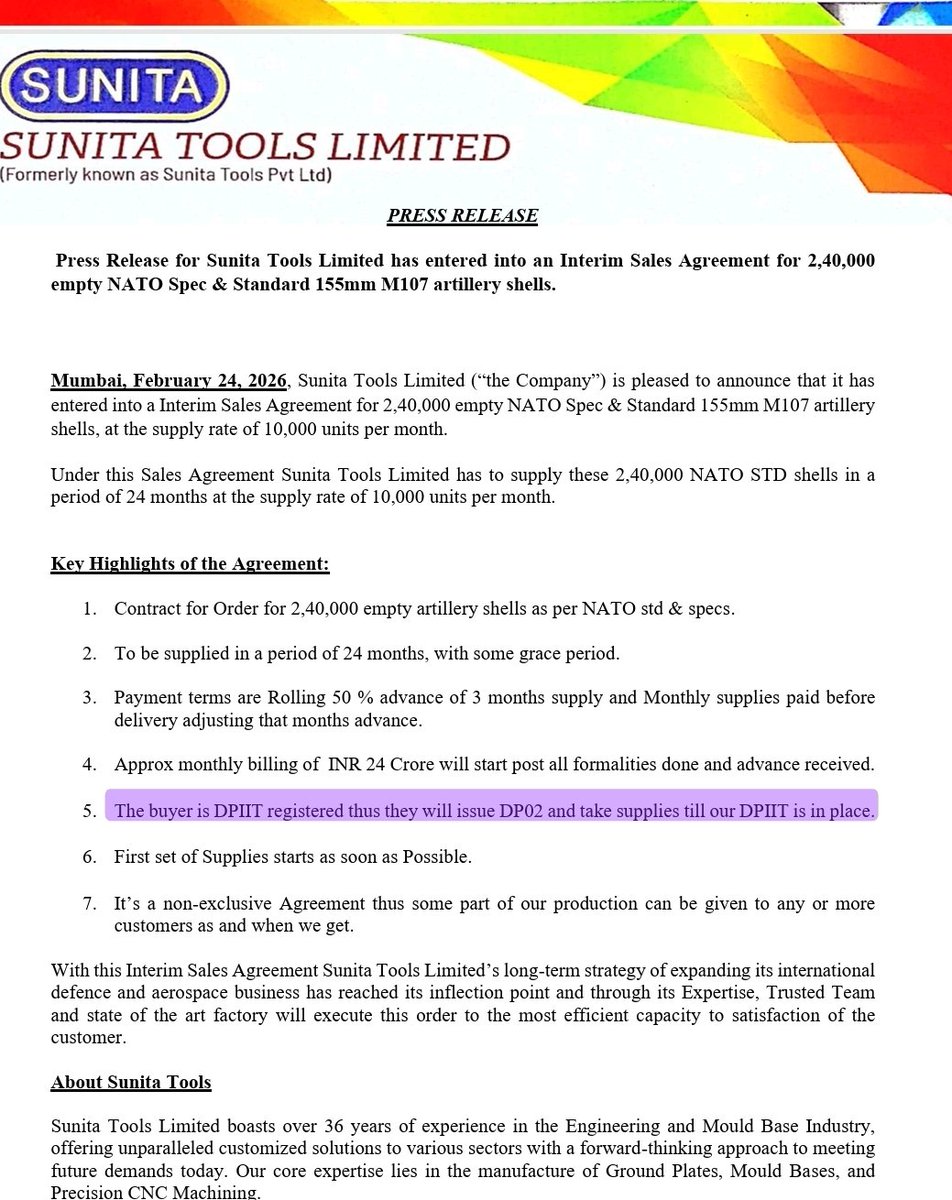
@ankurjain83@Chirag68158004@SidNayak7@Kourav123 Ur meeting the promoter & stating the same is insignificant. Many investors have met the promoter. What the promoter states & what's comprehended is different at times. The last notification of being production ready is a big statement. Research? 😆😆, Pic is self explanatory!!
@Chirag68158004@SidNayak7@ankurjain83@Kourav123 Your understanding is absolutely correct. Along with DP02 , advance receipt is paramount , 2 tranches have been received and 3rd one is awaited upon receipt of the same DP02 will be seeked. Factory is production ready infact is positive statement rather than claimed otherwise.