Every call goes up before the print. Every receipt goes up after.
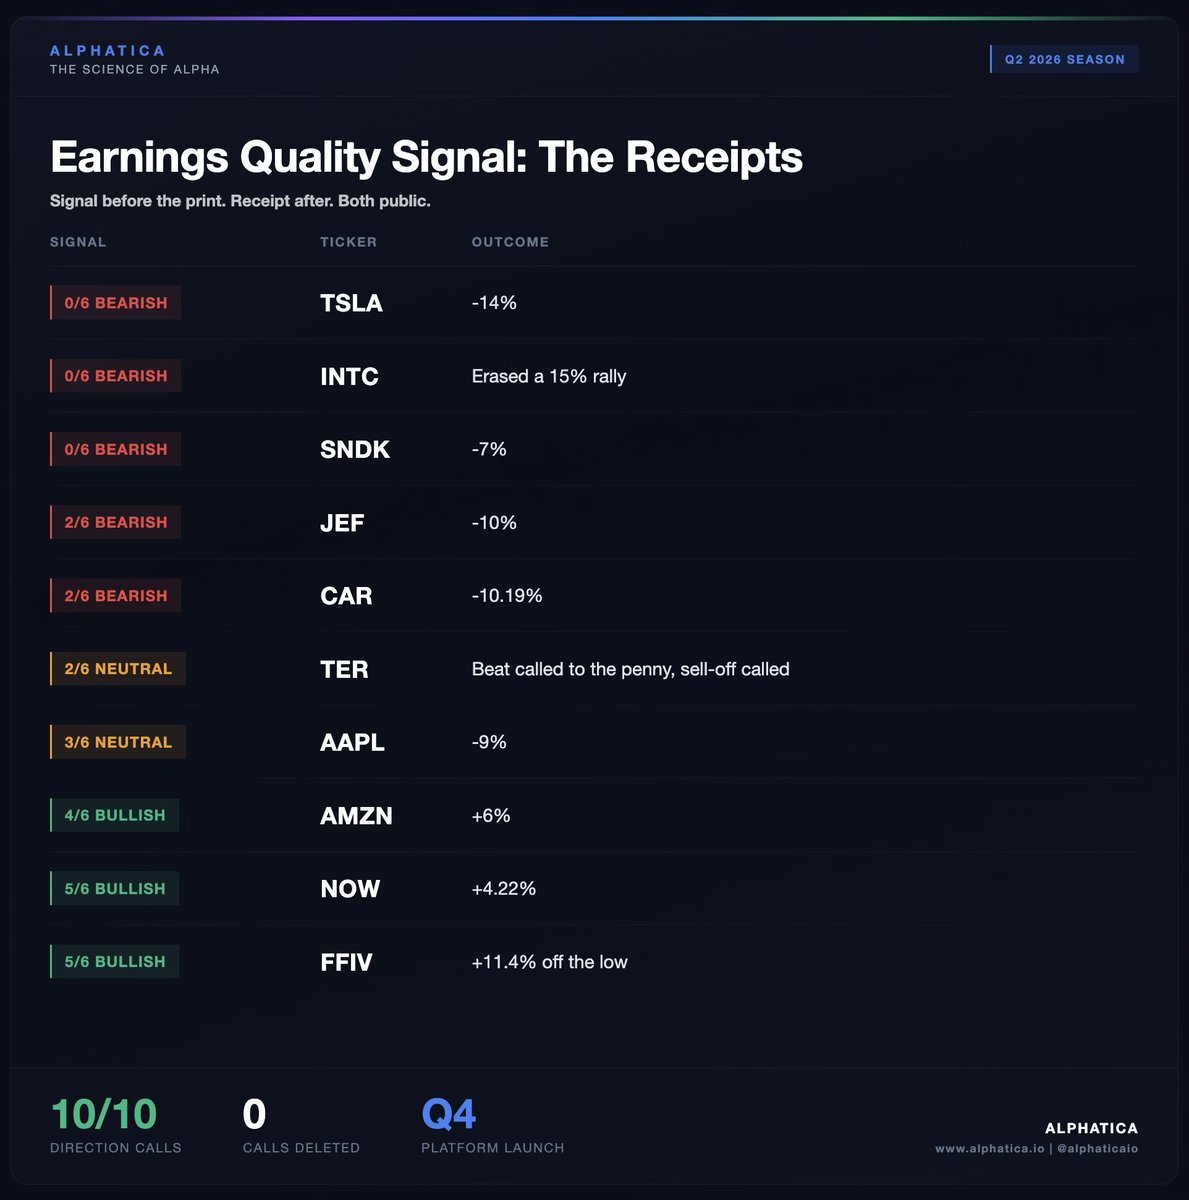
Q2 2026, Alphatica Earnings Quality Signal:
0/6 BEARISH TSLA -14%
0/6 BEARISH INTC erased a 15% rally
0/6 BEARISH SNDK -7%
2/6 BEARISH JEF -10%
2/6 BEARISH CAR -10.19%
2/6 NEUTRAL TER beat called to the penny, sell-off called
3/6 NEUTRAL AAPL -9%
4/6 BULLISH AMZN +6%
5/6 BULLISH NOW +4.22%
5/6 BULLISH FFIV +11.4% off the low
Next up is NVDA, August 26 post-market. The call posts before it.
What else runs here: Institutional quality research that you will only find behind trading desks and prime brokerages.
The edge was never the data. It was who could afford the analysis. Q4 changes that.
Institutional and data licensing: [email protected]
Get on the list first: https://t.co/5wz4VrHpgG
$NVDA $SPY $QQQ
TSLA. We called MISS. Adjusted EPS $0.48 vs $0.45 street and $0.40 from us. Revenue $28.04B vs $28.25B street. We had $28.6B.
Wrong on EPS. Wrong on revenue. Wrong on the pattern. We said revenue would beat and margin would fail. Revenue missed and earnings beat.
Stock up 1.45% after hours to $392.09.
The disclosure signal said BULLISH. It was right. Our call went the other way.
The quality signal says 0/6. GAAP EPS $0.22. Adjusted $0.48. More than half of tonight's earnings live in the adjustments. That part of the read has not changed.
Gross margin still to come. That tells us if this beat is durable.
We post the misses with the same card as the wins. That is the point.
*The Alphatica Earnings Quality Signal is 0/6 BEARISH. Keep an eye on price.
$TSLA $SPY
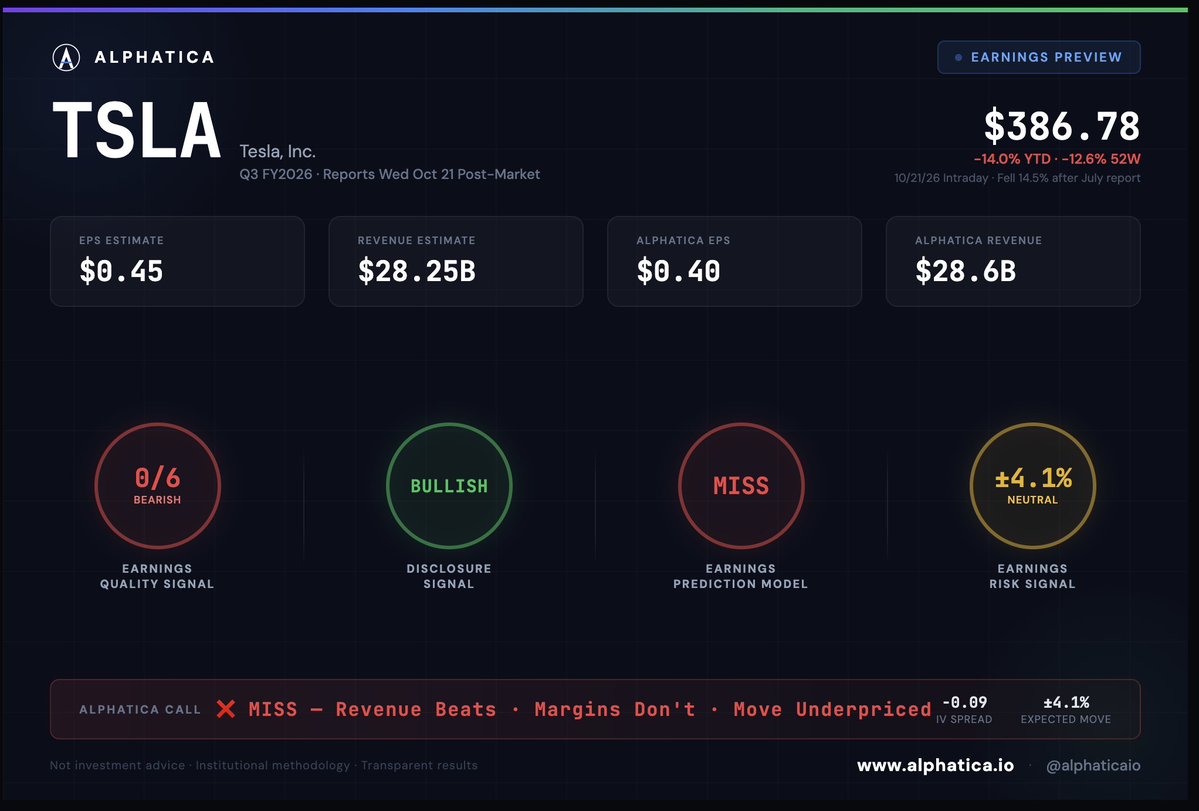
TSLA reports tonight after the close.
0/6 on our quality signal. BULLISH on disclosure. NEUTRAL on risk, with calls and puts priced dead even. Up 3.5% today going in. Last quarter revenue beat by 6.6%, EPS missed by 39%, and the stock fell 14.5% the next day.
Street EPS: $0.45
Street Revenue: $28.25B
Alphatica Estimates:
EPS: $0.40
Revenue: $28.6B
OUR CALL: MISS ❌
We called BEAT in July. The quality signal was right and we were wrong. We are not making the same mistake twice.
The pattern is the call. Tesla has beaten revenue in 5 of the last 8 quarters but EPS in only 3. The last two big revenue beats, Q3 2025 at +5.2% and Q2 2026 at +6.6%, came with EPS misses of 10.5% and 39%. Volume is there. Margin is not.
Q3 deliveries were 486,532, beating delivery consensus by 5.3% and up 1.3% from Q2. That supports revenue. But energy storage deployments came in at 13.7 GWh against 15.9 GWh expected, a 14% miss in the highest-margin segment. Regulatory credits fell to $146M last quarter, less than half of what was expected. Operating spend on AI, robotaxi and R&D is still rising.
MARGIN IS THE TELL:
Gross margin printed 16.8% last quarter. The street wants 17.9% tonight. Beat line 18.5%, miss line 17.3%. The street has Q3 operating income at $946M, a 3.35% margin, more than double Q2's 1.4%. That is a big recovery to ask of a quarter where deliveries grew 1.3%.
The street already knows margins are under pressure. Q3 operating income estimates were cut 17% in 90 days. FY2027 operating income was cut 18%. FY2027 free cash flow consensus went from negative $5.0B to negative $9.3B in the same window.
OUR FOUR SIGNALS:
Earnings Quality: 0/6 BEARISH. Unchanged. Net income fell 46% in FY2025, from $7.15B to $3.86B. Gross margin compressed from 25.6% to 18.0% over three years. Revenue declined for the first time at this scale. Management's internal accounting signals reversed from maximum confidence to rebuilding reserves, and the rebuild is accelerating. The one clean metric is cash: $14.75B in operating cash flow, 3.8x net income.
Disclosure Signal: BULLISH. Maintained and strengthening. Quarterly filing tone has improved five straight quarters, each one a record in Tesla's 15-year filing history. The MD&A section scored positive tone outright, which is rare. Management is telling a better story every quarter. The numbers have not followed yet.
Prediction Model: MISS. 3 of the last 8 quarters beat on EPS, with an average surprise of -5.7%. Lifetime beat rate 44%.
Earnings Risk Signal: +/-4.1% NEUTRAL. IV spread at -0.09. Expected move +/-4.1%, about $15.62. The average post-earnings move over three years is 8.97%. Options are pricing less than half of what this stock usually does. In July they priced 3.9% and the stock fell 14.5%.
THE SETUP:
After a revenue beat, Tesla has averaged -3.9% the next day, up only 4 of 13 times. After an EPS miss, -4.4%. Revenue surprise and the stock reaction are negatively correlated. One up revision and four down in the last 30 days. Mean target $398, 2.9% above the price. 185x forward earnings.
Short volume ratio peaked at 62.6% on September 25. It is now 48.3%, back inside the 45% to 50% band normal hedging produces.
$386.78 is the price. $28.25B is the street. $0.45 is the bar. 17.9% gross margin is the line that matters. Two red circles, one green, one yellow. The revenue beat is likely. The margin decides the stock, and options are not priced for it.
Not Investment Advice.
$TSLA $SPY
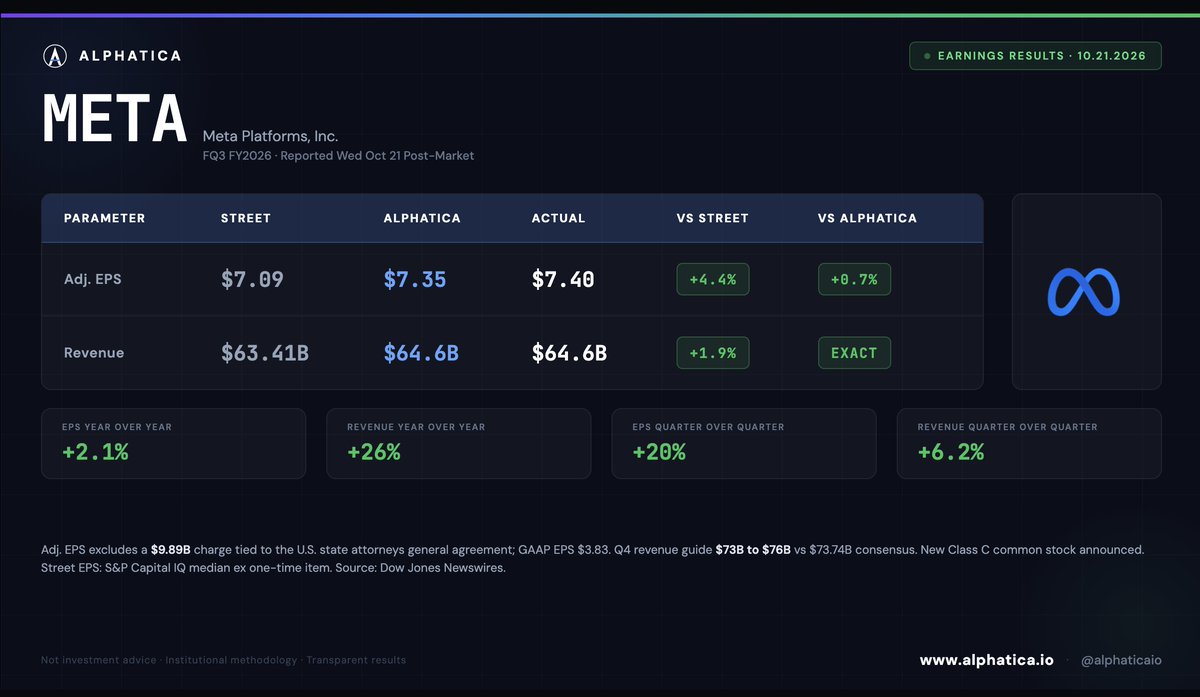
META. We called BEAT. $7.40 adjusted vs $7.09 street. Revenue $64.6B. Our number was $64.6B.
Dead on.
Stock up 3.94% after hours to $721.57.
We told you the consensus was split by a one-time charge. We told you to judge the quarter ex the item. Tonight: a $9.89B charge for an agreement with U.S. state attorneys general. GAAP EPS $3.83. Adjusted $7.40.
We also told you litigious language in Meta's filings had tripled since FY2022 to a series high. That is why our disclosure signal was downgraded to NEUTRAL. The legal docket just became a $9.89B line item.
Revenue up 26% year over year. Q4 guide $73B to $76B vs $73.74B street. Midpoint above.
What we are still watching: the capex guide on the call. That decides whether this holds.
$META $SPY
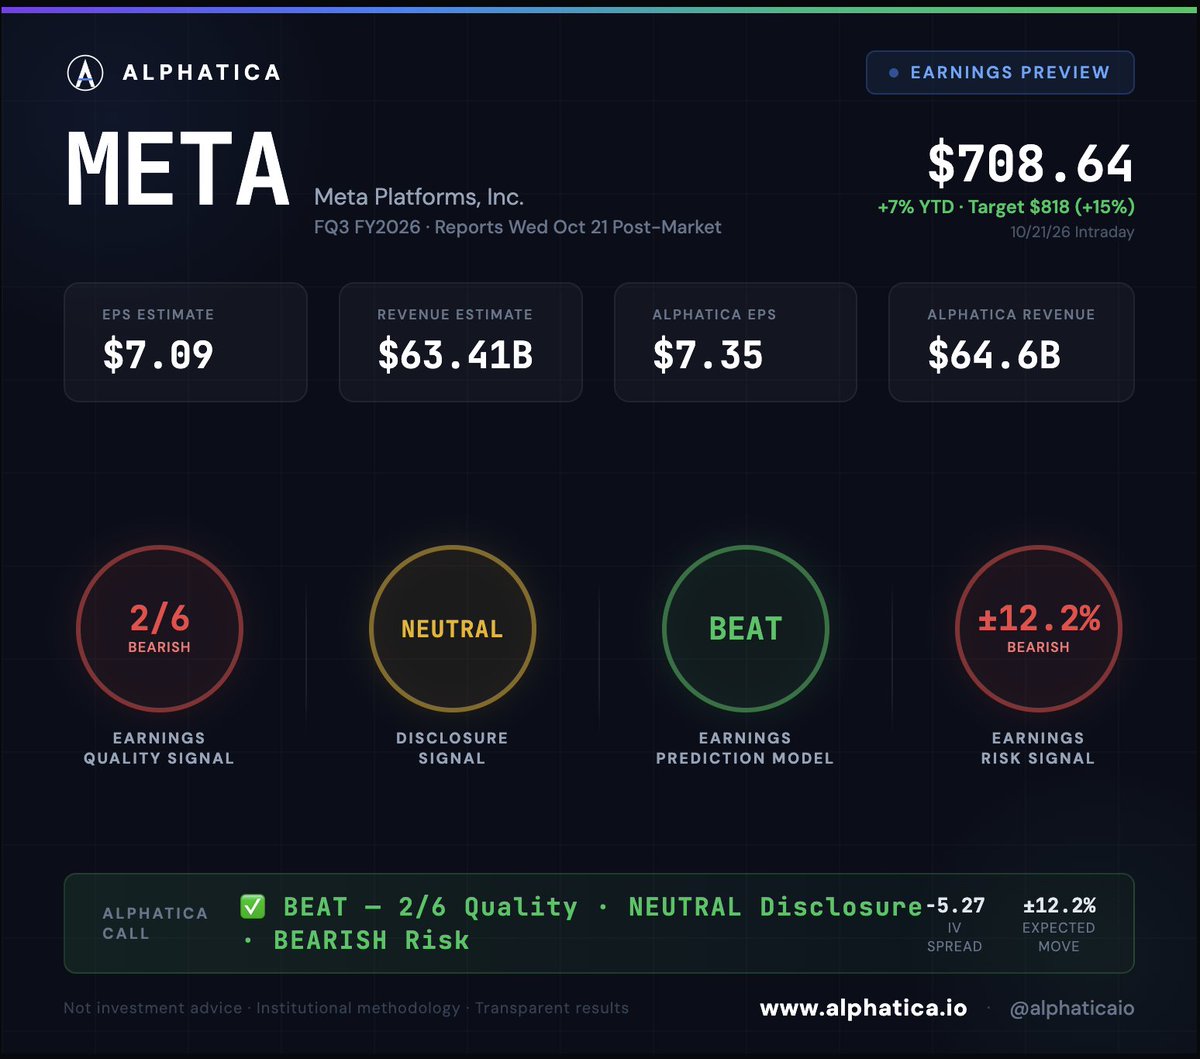
META reports tonight after the close.
2/6 on our quality signal. NEUTRAL on our disclosure signal, downgraded from BULLISH in April. Puts priced over calls. Options pricing a 12% move. Up 23% in eight weeks going in. Last quarter it missed by 16.5% and fell 8%.
Street EPS: $7.09 (ex one-time item)
Street Revenue: $63.41B
Alphatica Estimates:
EPS: $7.35
Revenue: $64.6B
OUR CALL: BEAT ✅
Read the consensus carefully tonight. It is split. The mean is $6.80. The median is $7.09. The gap is a one-time item that some analysts model and most headline numbers will not separate. Truist is at $3.92 and raised its target to $1,000 the same day. That is not a bear call. That is a charge. Judge the quarter on the number ex the item. The beat line is $7.30. The miss line is $6.90.
Meta has beaten EPS in 7 of the last 8 quarters by an average of 10.8%, and beaten revenue in all 8 by an average of 2.5%. We are sizing at $7.35 ex-item, a 3.7% beat, and $64.6B on revenue, 1.9% above the street.
THE REAL NUMBER IS NOT EPS:
The street has cut Q3 operating income 14% in 90 days while leaving revenue untouched. Implied operating margin has fallen from 33.1% to 28.3%. FY2027 free cash flow consensus went from negative $4.4B to negative $29.0B in the same 90 days. The market already knows the spending is coming. The question is whether the capex guide goes higher again. The last two times it did, Q1 2024 and Q3 2025, the stock fell 10.6% and 11.3% the next day on beats.
OUR FOUR SIGNALS:
Earnings Quality: 2/6 BEARISH. The business is exceptional: $60.5B in net income, operating margin from 24.8% to 41.4% in three years, $115.8B in operating cash flow. But stock comp runs at $20.4B, 10.2% of revenue, one of the highest ratios in our database at this scale. And management's internal accounting signals posted the most severe single-year deterioration we have ever recorded. The most profitable ad business ever built, with weak accounting confidence.
Disclosure Signal: NEUTRAL. Downgraded from BULLISH. The April call rested on the first annual tone improvement in five years. It never confirmed. Quarterly tone slipped back into the range it has held since 2022. Litigious language in the annual filing has more than tripled since FY2022 and sits at a series high. The legal docket is growing inside the filings.
Prediction Model: BEAT. 7 of the last 8 quarters beat on EPS. 19 of the last 22 beat on revenue. Lifetime beat rate 84%.
Earnings Risk Signal: +/-12.2% BEARISH. IV spread at -5.27. Puts priced over calls. Expected move +/-12.2%, about $86.63. The average post-earnings move over three years is 8.23%. The options market is pricing a bigger move than history and paying up for downside.
THE SETUP:
Seven target raises and one cut in the last 30 days. Mean target $818, up 7.9% in a month. The stock ran 23% in eight weeks before giving back 4.8% in the last four. 20.9x forward earnings, the 35th percentile since 2019. Not cheap, not stretched.
Short volume ratio peaked at 59.7% on September 24. It is now 29.7%, well below the 45% to 50% that normal hedging produces. The shorts left before the print.
$708.64 is the price. $63.41B is the street. $7.09 is the bar ex-item. $7.30 is the beat line. Two red circles, one yellow, one green. The beat is likely. The capex guide decides the stock.
Not Investment Advice.
$SPY $META
TSLA reports tonight after the close.
0/6 on our quality signal. BULLISH on disclosure. NEUTRAL on risk, with calls and puts priced dead even. Up 3.5% today going in. Last quarter revenue beat by 6.6%, EPS missed by 39%, and the stock fell 14.5% the next day.
Street EPS: $0.45
Street Revenue: $28.25B
Alphatica Estimates:
EPS: $0.40
Revenue: $28.6B
OUR CALL: MISS ❌
We called BEAT in July. The quality signal was right and we were wrong. We are not making the same mistake twice.
The pattern is the call. Tesla has beaten revenue in 5 of the last 8 quarters but EPS in only 3. The last two big revenue beats, Q3 2025 at +5.2% and Q2 2026 at +6.6%, came with EPS misses of 10.5% and 39%. Volume is there. Margin is not.
Q3 deliveries were 486,532, beating delivery consensus by 5.3% and up 1.3% from Q2. That supports revenue. But energy storage deployments came in at 13.7 GWh against 15.9 GWh expected, a 14% miss in the highest-margin segment. Regulatory credits fell to $146M last quarter, less than half of what was expected. Operating spend on AI, robotaxi and R&D is still rising.
MARGIN IS THE TELL:
Gross margin printed 16.8% last quarter. The street wants 17.9% tonight. Beat line 18.5%, miss line 17.3%. The street has Q3 operating income at $946M, a 3.35% margin, more than double Q2's 1.4%. That is a big recovery to ask of a quarter where deliveries grew 1.3%.
The street already knows margins are under pressure. Q3 operating income estimates were cut 17% in 90 days. FY2027 operating income was cut 18%. FY2027 free cash flow consensus went from negative $5.0B to negative $9.3B in the same window.
OUR FOUR SIGNALS:
Earnings Quality: 0/6 BEARISH. Unchanged. Net income fell 46% in FY2025, from $7.15B to $3.86B. Gross margin compressed from 25.6% to 18.0% over three years. Revenue declined for the first time at this scale. Management's internal accounting signals reversed from maximum confidence to rebuilding reserves, and the rebuild is accelerating. The one clean metric is cash: $14.75B in operating cash flow, 3.8x net income.
Disclosure Signal: BULLISH. Maintained and strengthening. Quarterly filing tone has improved five straight quarters, each one a record in Tesla's 15-year filing history. The MD&A section scored positive tone outright, which is rare. Management is telling a better story every quarter. The numbers have not followed yet.
Prediction Model: MISS. 3 of the last 8 quarters beat on EPS, with an average surprise of -5.7%. Lifetime beat rate 44%.
Earnings Risk Signal: +/-4.1% NEUTRAL. IV spread at -0.09. Expected move +/-4.1%, about $15.62. The average post-earnings move over three years is 8.97%. Options are pricing less than half of what this stock usually does. In July they priced 3.9% and the stock fell 14.5%.
THE SETUP:
After a revenue beat, Tesla has averaged -3.9% the next day, up only 4 of 13 times. After an EPS miss, -4.4%. Revenue surprise and the stock reaction are negatively correlated. One up revision and four down in the last 30 days. Mean target $398, 2.9% above the price. 185x forward earnings.
Short volume ratio peaked at 62.6% on September 25. It is now 48.3%, back inside the 45% to 50% band normal hedging produces.
$386.78 is the price. $28.25B is the street. $0.45 is the bar. 17.9% gross margin is the line that matters. Two red circles, one green, one yellow. The revenue beat is likely. The margin decides the stock, and options are not priced for it.
Not Investment Advice.
$TSLA $SPY
SPX at 7,767, just through the 7,764 flip. That’s the first time back in positive gamma since Thursday. From here dealers absorb instead of chase, so expect the move to slow. 7,800 is the magnet; 7,750 is the line that has to hold.
We told you it was going to run. Hopefully you cashed in.
$SPY ethereum:0xe0f63a424a4439cbe457d80e4f4b51ad25b2c56c
IBM reports tonight after the close.
3/6 on our quality signal. NEUTRAL on disclosure. NEUTRAL on risk, with calls and puts priced almost dead even. Down 17% this year, but up 19% since the July report. Last quarter it matched on EPS and missed on revenue after six straight beats.
Street EPS: $2.87
Street Revenue: $16.84B
Alphatica Estimates:
EPS: $2.97
Revenue: $16.98B
OUR CALL: BEAT ✅
Measured against the number the street actually grades, IBM has beaten EPS in 7 of the last 8 quarters by an average of 5.5%. We are sizing at $2.97, a 3.4% beat, and $16.98B on revenue, 0.8% above the street.
The case for revenue is specific. In July, software missed because tens of large deals, mostly mainframe software license agreements, slipped out of the quarter. Management said about a third of them closed in the first three weeks of Q3. That revenue lands in this print. The full-year guide was cut to 4% to 5% growth with the low end as the base case, and the street sits right at that low end. The bar is not high.
REVENUE IS THE TELL:
EPS barely moves this stock. Over 22 quarters, the correlation between the EPS surprise and the next-day move is slightly negative. IBM beat EPS in 7 of the last 8 quarters and fell the next day after 5 of those 7 beats. Revenue is what the market trades. After a revenue beat the stock has averaged +1.7% the next day. After a revenue miss, -3.6%. The beat line is $16.93B. The miss line is $16.76B.
OUR FOUR SIGNALS:
Earnings Quality: 3/6 NEUTRAL. The operating story is real. Revenue has grown every year, $60.5B to $67.5B, and gross margin expanded every year, 54.0% to 58.2%, as the mix shifted to software. Operating cash flow has held above $13B for four straight years and equity grew from $21.9B to $32.7B. What holds it back: reported net income has been lifted by tax benefits in 3 of the last 4 years, and management's internal accounting signals show no clear direction.
Disclosure Signal: NEUTRAL. IBM is one of the most stable filers in our universe. The annual filing is nearly identical year to year, risk factors are unchanged, and litigious language is zero. Annual tone is at a five-year best. The Q2 filing eased back slightly but stayed inside the range IBM has held for years. Healthy, but nothing directional.
Prediction Model: BEAT. 19 of the last 22 quarters beat on EPS. Revenue beat in 6 of the last 8. Lifetime EPS beat rate 83%.
Earnings Risk Signal: +/-5.3% NEUTRAL. IV spread at +0.49. Balanced call and put pricing. Expected move +/-5.3%, about $12.92. The average post-earnings move over three years is 6.25%, and 6.0% over the last eight reports. Options are pricing a smaller move than this stock usually delivers.
THE SETUP:
Zero estimate raises and three cuts in the last 30 days. Q3 EPS consensus down 2.2% in 90 days. The street-high target was cut from $350 to $297 within the last month. The mean target is $243, below where the stock trades now. 18.9x forward earnings.
Seasonality is not on its side. Of the four fiscal quarters, Q3 reports have produced the weakest five-day reaction, averaging -2.7% across 23 reports.
Short volume ratio averaged 46.3% over the last 20 days. Short interest is unusually high going into the print.
$245 is the price. $16.84B is the street. $2.87 is the bar. $16.93B is the line that matters. Three yellow circles and one green. The beat is likely. Revenue decides the stock.
Not Investment Advice.
$IBM $IGV $SPY
🚨 THE MOST-SHORTED SECTOR IN AMERICA IS ALSO THE ONLY ONE WHERE SHORTS ARE BACKING OFF.
Consumer discretionary short interest ended September at 7.5%.
That is the highest of any US equity sector and nearly double the S&P 500 average of 3.9%.
But the direction changed.
Consumer discretionary short interest fell from 8.1% to 7.5% during Q3, a 60-basis-point decline.
It was the only one of the 11 sectors to record a quarterly decrease.
Meanwhile:
Health care: 6.9% to 7.4%
Technology: 6.5% to 6.9%
Industrials: 5.1% to 5.8%
Nine sectors experienced an average increase of 30 basis points. Real estate was unchanged. This happened while inflation remained elevated and the Fed delivered its first rate hike since 2023.
In other words, the macro pressure did not disappear.
But short sellers still began reducing their most crowded consumer bet.
That does not mean the consumer is healthy. S&P 500 consumer discretionary short interest remains elevated at 5.2%, up from 3.7% one year ago.
It does suggest the peak in bearish positioning may have occurred earlier this year.
The most-shorted S&P 500 names:
FOX: 23.9%
NCLH: 21.1%
Consumer discretionary remains the market’s favorite short. But for the first time, the crowd is moving toward the exit.
$SPY $QQQ
META reports tonight after the close.
2/6 on our quality signal. NEUTRAL on our disclosure signal, downgraded from BULLISH in April. Puts priced over calls. Options pricing a 12% move. Up 23% in eight weeks going in. Last quarter it missed by 16.5% and fell 8%.
Street EPS: $7.09 (ex one-time item)
Street Revenue: $63.41B
Alphatica Estimates:
EPS: $7.35
Revenue: $64.6B
OUR CALL: BEAT ✅
Read the consensus carefully tonight. It is split. The mean is $6.80. The median is $7.09. The gap is a one-time item that some analysts model and most headline numbers will not separate. Truist is at $3.92 and raised its target to $1,000 the same day. That is not a bear call. That is a charge. Judge the quarter on the number ex the item. The beat line is $7.30. The miss line is $6.90.
Meta has beaten EPS in 7 of the last 8 quarters by an average of 10.8%, and beaten revenue in all 8 by an average of 2.5%. We are sizing at $7.35 ex-item, a 3.7% beat, and $64.6B on revenue, 1.9% above the street.
THE REAL NUMBER IS NOT EPS:
The street has cut Q3 operating income 14% in 90 days while leaving revenue untouched. Implied operating margin has fallen from 33.1% to 28.3%. FY2027 free cash flow consensus went from negative $4.4B to negative $29.0B in the same 90 days. The market already knows the spending is coming. The question is whether the capex guide goes higher again. The last two times it did, Q1 2024 and Q3 2025, the stock fell 10.6% and 11.3% the next day on beats.
OUR FOUR SIGNALS:
Earnings Quality: 2/6 BEARISH. The business is exceptional: $60.5B in net income, operating margin from 24.8% to 41.4% in three years, $115.8B in operating cash flow. But stock comp runs at $20.4B, 10.2% of revenue, one of the highest ratios in our database at this scale. And management's internal accounting signals posted the most severe single-year deterioration we have ever recorded. The most profitable ad business ever built, with weak accounting confidence.
Disclosure Signal: NEUTRAL. Downgraded from BULLISH. The April call rested on the first annual tone improvement in five years. It never confirmed. Quarterly tone slipped back into the range it has held since 2022. Litigious language in the annual filing has more than tripled since FY2022 and sits at a series high. The legal docket is growing inside the filings.
Prediction Model: BEAT. 7 of the last 8 quarters beat on EPS. 19 of the last 22 beat on revenue. Lifetime beat rate 84%.
Earnings Risk Signal: +/-12.2% BEARISH. IV spread at -5.27. Puts priced over calls. Expected move +/-12.2%, about $86.63. The average post-earnings move over three years is 8.23%. The options market is pricing a bigger move than history and paying up for downside.
THE SETUP:
Seven target raises and one cut in the last 30 days. Mean target $818, up 7.9% in a month. The stock ran 23% in eight weeks before giving back 4.8% in the last four. 20.9x forward earnings, the 35th percentile since 2019. Not cheap, not stretched.
Short volume ratio peaked at 59.7% on September 24. It is now 29.7%, well below the 45% to 50% that normal hedging produces. The shorts left before the print.
$708.64 is the price. $63.41B is the street. $7.09 is the bar ex-item. $7.30 is the beat line. Two red circles, one yellow, one green. The beat is likely. The capex guide decides the stock.
Not Investment Advice.
$SPY $META
SPX GEX Levels: Wednesday, October 21
SPX closed Tuesday at 7,712.57, up 22 points (+0.28%), inside our 7,630–7,765 range. It rallied into the 7,738 flip zone in the morning, got rejected, and held 7,720 twice into the afternoon. That's the setup we laid out.
The headline improved again. Net gamma went from -$326M to -$220M.
Underneath, the zone price rejected got heavier. Puts piled into it:
7,700: -$158M (spot, heaviest bucket)
7,725: -$99M (was -$49M)
7,750: -$128M (was -$50M)
7,700–7,750 went from -$209M to -$385M in one session. The flip moved up from 7,738 to 7,764, now 52 points away.
Volume put/call jumped from 1.53 to 1.75, back above 1.55. Put buying concentrated at 7,700, 7,650, 7,600 and 7,500. ATM IV is flat at 14.5%.
So net gamma is healing, but the part that matters most, right at and above spot, got worse. The improvement came from further out: 8,000 and 8,050 grew. That doesn't help price today.
Above the flip, 7,800 (+$87M) is the first magnet and 7,900 (+$98M) the next.
Reclaim 7,764 and dealers go back to absorbing, with 7,800 the pull. Lose 7,700 and the heaviest bucket on the board turns into fuel, with 7,650 (-$131M) next.
Predicted range: 7,640–7,775.
$SPY $QQQ $SPX
Based on the current structure 7800 would be the target into the close. Does not mean it will get there. After 7800 the market runs out of steam again based on today's data.
$SPY $SPX