If you think $CIFR has already priced in all its catalysts, you don't know what you own -> My take on what’s priced in (and what’s not) 👇
1️⃣ Black Pearl deal → Partially priced in.
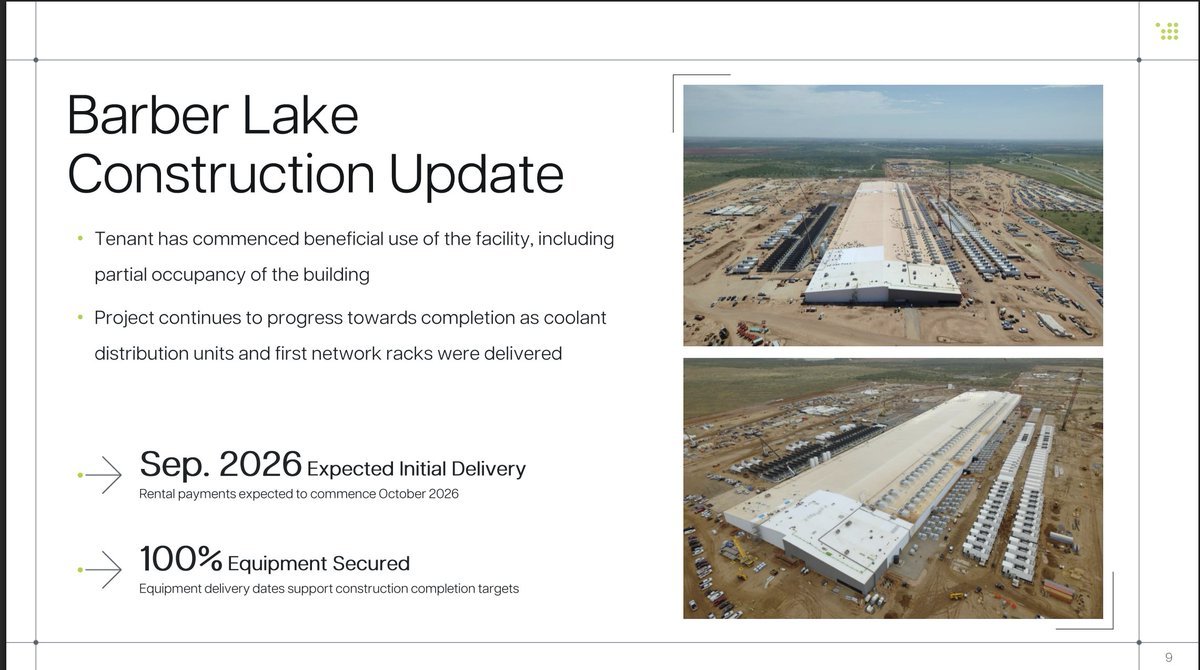
While some of it may already be priced in, no one knows if it’s a 150MW or 300MW deal - that’s a multi-billion-dollar difference. And if $CIFR lands another world-class tenant (like Google), it would be full market validation of their AI/HPC strategy.
2️⃣ $1.3B cash on hand → Partially priced in.
They’ll use a construction loan + Google-backed Fluidstack deal to fund Barber Lake - derisking the financials, which is already priced in.
However, that frees up $1.3B to go on offense - new deals, new sites (adding to the MASSIVE 2.6 GW pipeline), new catalysts!!! -> Not priced in.
As Tyler Page said: “We raised $1.3 billion dollars… we can go play offense.”
3️⃣ Earnings → Not priced in.
Hashrate now at full 23.5 EH/s and this quarter Bitcoin reached ATHs - this quarter should smash expectations.
4️⃣ 56 MW still open at Barber Lake → Not priced in.
Possible CSP pilot? Could mirror $IREN GPU strategy and test HPC capacity here.
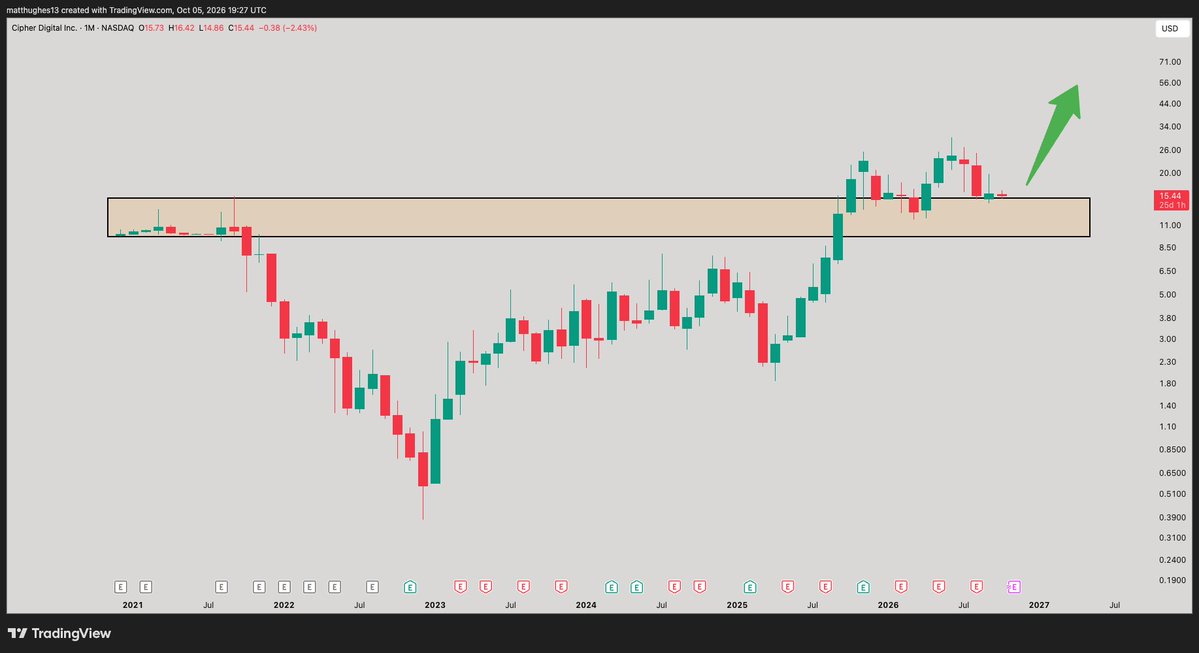
People saying $CIFR has topped or everything’s priced in couldn’t be more wrong. The most bullish phase for $CIFR is still ahead, and these are just the short- and mid-term catalysts. Way more to come -> BULLISH
Anything to add @accounting_ds @DollarCostAvg ?
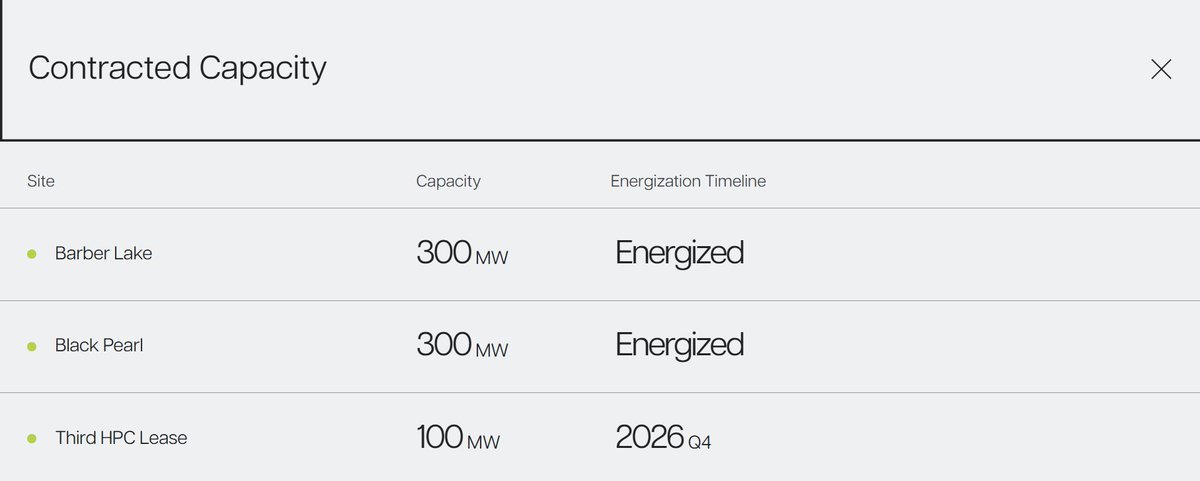
UBS believes $CIFR can double its contracted lease portfolio and become a scaled data center platform:
"We believe the company has demonstrated strong progression across its successive lease announcements with an estimated $12-14M per MW of equity value creation in recent deals."
• Remaining power pipeline is ~6x the current leased footprint, but Texas regulatory timing is the wild card.
• UBS estimates ~350 MW IT available across three sites in 2027 are likely for lease announcements as hyperscaler pre-leasing typically starts around 18 months before delivery.
• Batch Zero disclosures are a first step toward getting the market to underwrite expansion that gets little to no valuation credit as of today.
Source: UBS Initiation of Coverage AI Infrastructure (9/22/2026)
I think you are oversimplifying the concept of “spot” rates for leasing. Generally, tenants are very interested in powered shells available in the near-term and become less interested in ones available further into the future. This relative level of interest is reflected in what they are willing to pay in rent. Leases that are being signed and announced now are typically for sites available 12-18 months out, and they are being signed at the highest rates we have seen. But if you ask a hyperscaler about what they would commit to pay right now for a long-term lease for a site available in 2030+ (if they would even be interested now), they might offer to pay 7-8% YOC. At those levels, we would not commit to a lease and will wait if we have such a site available.
The binding commitment we received here is for a lease starting 10 years from now at a rate in-line with today’s elevated market rates for powered shells available in the near-term from a very large and successful leading AI lab. This is a big deal and evidence of a long-term sustained demand environment in my opinion.
I saw a few other questions along the lines of “Why sign now? Why not wait?” Presumably this logic is based on the idea that we should just wait 8.5 years until interest will be higher. My answer is that we have never seen interest at today’s elevated rates for a lease starting that far in the future and it provides an excellent projected IRR on our investment. Also, if we follow that advice, why should we ever sign a lease at all? Just keep waiting for infinitely higher lease rates. I don’t believe that is a winning strategy.
Lastly, keep in mind that headline lease rates don’t tell the full story in an inflationary environment with fast-changing design and engineering standards. You need to consider other elements that can control your costs and financing risks. We are focused on maximizing a return on our investment while managing risks. (Note that this is also why revenue comparisons with neoclouds are somewhat irrelevant—they have a completely different cost and risk structure)
@cantonmeow@cantonmeow I am thinking about taking your course on TA since I want to complement my fundamentals knwoledge. Do you recommend any books as conplementary knowledge?
$CIFR just doubled Barber Lake’s contracted life from 10 to 20 years taking total contracted revenue to more than $9B.
A binding 10 year follow on commitment from an AI lab adds ~$5.2B of incremental revenue as capacity comes online from Q4 2026 through Q1 2027.
🚨🚨🚨🚨🚨
$CIFR has extended Barber Lake from a 10-year lease to 20 years.
𝗖𝗼𝗻𝘁𝗿𝗮𝗰𝘁𝗲𝗱 𝗿𝗲𝘃𝗲𝗻𝘂𝗲 𝗴𝗼𝗲𝘀 𝗳𝗿𝗼𝗺 $3.8𝗕 𝘁𝗼 𝗼𝘃𝗲𝗿 $9𝗕.
1. ~$5.2B added by a leading AI lab
2. Binding 10-year commitment that starts after the Fluidstack lease ends
3. Separate lease, economics substantially consistent with the current one
The original Fluidstack deal was signed one year ago today. The second decade was two five-year options then. It is now contracted, with a second tenant lined up behind the first.
Tyler Page, CEO: "Barber Lake was designed as a long-lived, mission-critical asset."
The delivery schedule was revised with the amendment.
1. Data halls deliver in phases, Q4 2026 through Q1 2027
2. Rent starts hall by hall, first rent in Q4 2026
3. $CIFR says it is on track
Change orders pushed costs above the original budget.
1. $CIFR covers the first $359.3M
2. Above that, the tenant repays 50% over 20 years as rent, at a contracted return
3. The other 50% stays with $CIFR
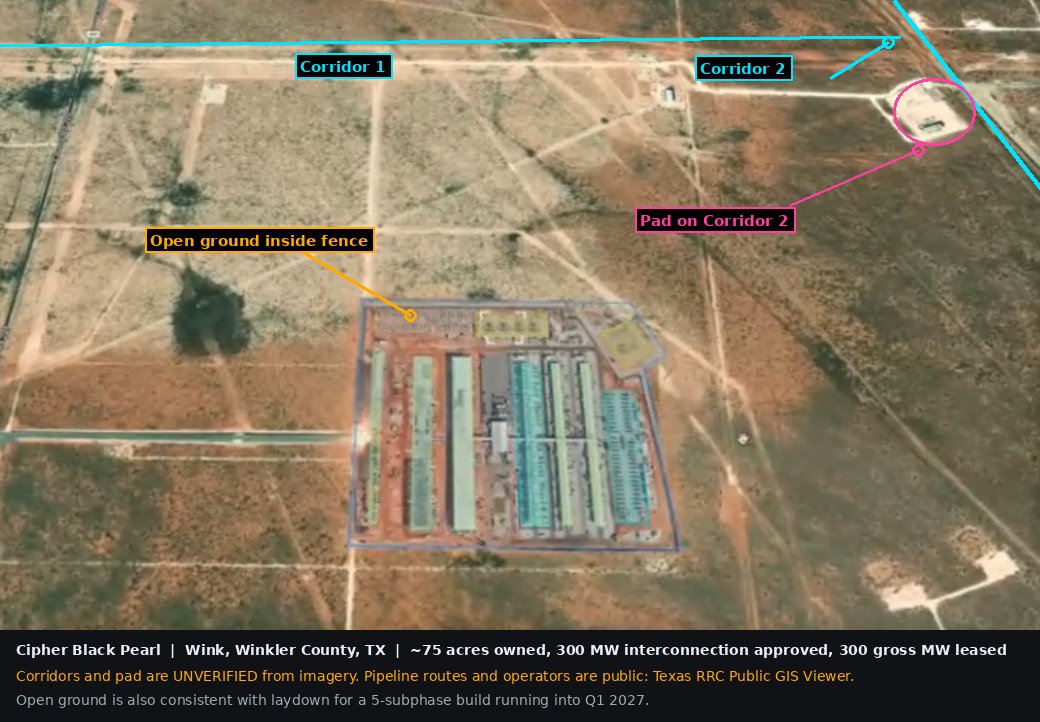
To be clear on the image: those two corridors are gas pipelines, with facilities sitting on the northeast one.
That's the point. $CIFR announced laterals for up to 2.5GW of on-site generation. Black Pearl already has the fuel at the fence line.
$CIFR Black Pearl expansion deal👀❗️
Energized, built, running. Beat the delivery date by 2 months. 300MW is fully taken. But look at the site: two corridors with facilities right off the northeast corner, open ground still inside the fence.
No new site. No new tenant. No queue
$CIFR is one of my favorite AI infrastructure stories right now: a former $BTC miner turning scarce power and land into long term data centre assets.
The opportunity here is large, but so are the execution and valuation questions. I went through the business model, contracted portfolio, financing structure, industry setup, risks, and what the current share price is already assuming.
Due to popular demand, I added the article on X.
Enjoy, it's free!
If you like it, please like/share.
@SylentTrade Watch $CIFR deliver again and again. Black pearl, barber lake, stingray, ulysses, reveille, odessa, COLCHIS, apollo, Mikeska, McLennan👀
@rftylerpage the captain