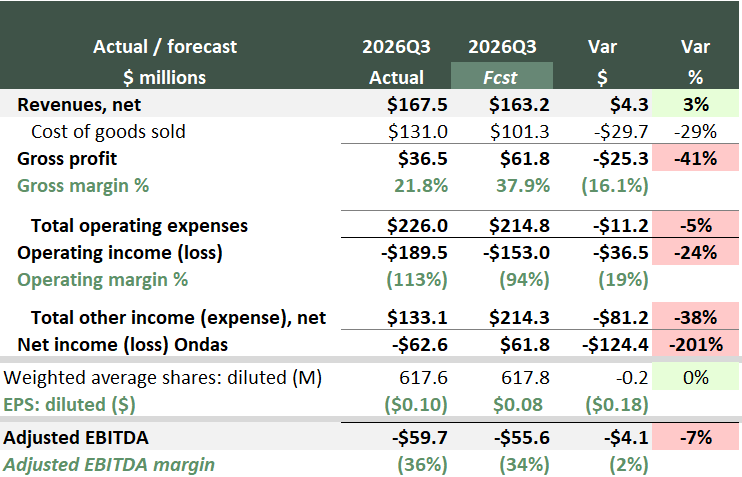
@konstibln Overall, really strong quarter that confirms a lot of what I wanted see in delivery execution, product advancement, and business development momentum. Acquisition and mfg scaling costs are a near term headwind but clear the path for 27 / 28 profit and scale
$ONDS Forecast Scorecard
✅Revenue ramp on track and executing: +2.7% vs my model
❌I was significantly off in COGs. Mix & acquisition impact. GAAP Opex: 5% above forecast, driven by R&D & stock comp
✅ Moved up EBITDA targets as I expected
Model updates over the coming days
@konstibln Gross margin impact will continue in q4. They are taking regna costs too that will impact expenses until they have revenue coming in or outside investment pushes them to non controlling interest. They pulled EBITDA profitability up to about the same point I have it.
@accurry0703 I think there’s a lot of noise when this many acquisitions close in a quarter, and when production need to scale this fast. For my financial model, it’s a fair take. I was off there. If it’s about ondas’ financial model, I don’t see anything now that makes me worried longer term
I've created a detailed multi-year financial model for $ONDS, outlining what I view as a base case for $1B+ in adjusted EBITDA by 2030, before any additional acquisitions.
Earnings this Thursday are the first test.
Ondas: Quantifying the thesis ($ONDS) https://t.co/smLMKRWWj6
@accurry0703 Yeah, it was hit harder than I expected. I had the Dzyne inventory fair market adjustment and a large mix impact. Let’s see what Neil says on the call
@Courage_wins They might adjust for it in how they present adjusted gross margin / EBITDA, but they had to fair value adjust dzyne’s inventory at acquisition. Between that and mistral / indo ramping up, we might see rates come down a bit the next couple quarters but Gm $ will still be way up
@john_doe1479 World view program of record, skylance, if iron arrow is similar to what ionstrike could be, recurring sustainment on 3-400 ultra, $5b by 2030 is on the table with the existing business, then add new products, future acquisitions, regna, and networks, it gets wild fast.
@john_doe1479 Thank you, much appreciated. I agree on all your points. There is no upside from Regna or networks in this model at all, but very real. Dzyne can pretty easily get to $2b in total rev with ionstrike and blitz if they have strong adoption.
@OutOfStockPod Awesome write up. I’m super interested in how this progresses, fleet size, service life, recurring sustainment. This was a really helpful read
$ONDS Today’s PR is a small confirmation of the model assumptions outlined; strategic intent of Aran, Airobotics digital bat progressing as a growth driver, and avoiding doubling counting revenues in both. Will continue to track which assumptions hold and which change the model
I've created a detailed multi-year financial model for $ONDS, outlining what I view as a base case for $1B+ in adjusted EBITDA by 2030, before any additional acquisitions.
Earnings this Thursday are the first test.
Ondas: Quantifying the thesis ($ONDS) https://t.co/smLMKRWWj6
@Bobdog1922 This is a great summary, thank you for putting it together. Even saying waiting on launch date from spcx is better than what we’ve had. I’m less concerned about pushed revenue from delays and just want them to start hitting literally any of the timelines they guide to.
@accurry0703 Also said expect corp growth opex to grow more slowly in the coming quarters. Almost certainly to be higher $ but on 3-4x the revenue as 1H, so far less in % of revenue. Keep in mind I showed GAAP opex, a big chunk of that is non cash and they often show and speak to adj opex
@accurry0703 Thank you. Execution risk is a fair call out and certainly real. On q3 opex, I went back through the last few earnings pres + transcripts in addition to the filings. “Expect to narrow losses in 2h on EBITDA basis as we continue to invest in the growth platform”.