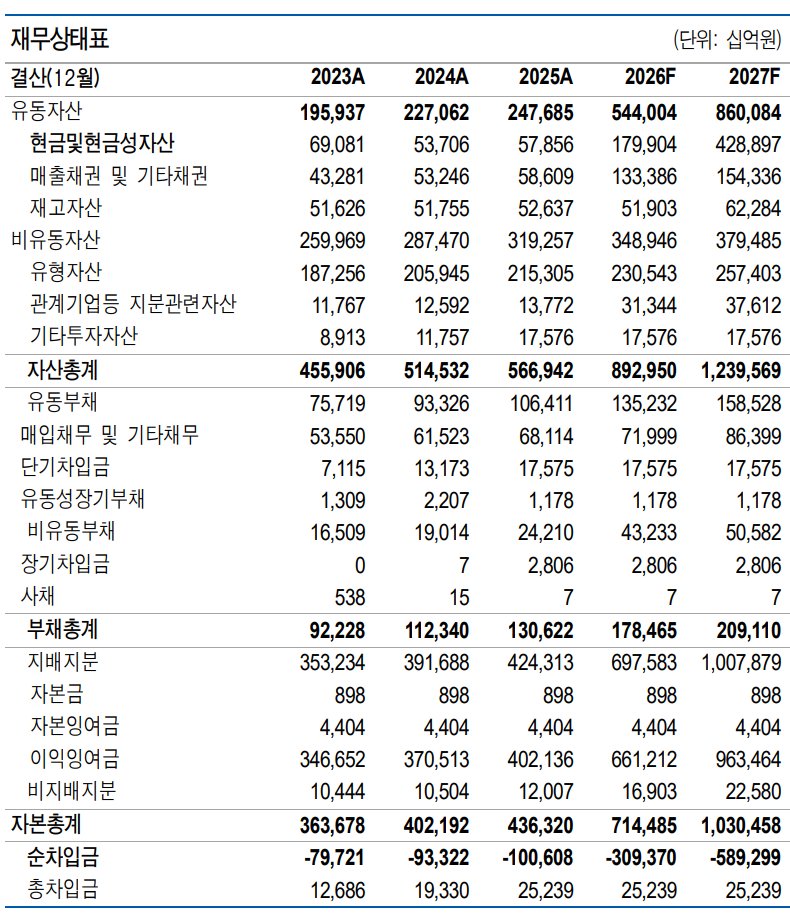
빅테크들의 높은 roe가 가벼운 자본구조와 소비자 락인 효과에서 기인했다라고 생각한다면,
지금의 AI시대의 빅테크의 BM은 자본집약적이고, 칩과 전기만 있으면 누구나 할 수 있는 BM인데
10년 뒤 반도체와 전력공급이 안정화된다면, 지금의 높은 벨류를 정당화할 수 있을까?
UBS, 마이크론 테크놀로지( $MU)에 대한 '매수(Buy)' 투자의견과 목표주가 1,625달러를 재확인
"최근 업계 점검 결과를 바탕으로 수익 모델을 소폭 조정했습니다. 연말부터 2027년 상반기(C1H27)까지 NAND 가격 변동 폭이 확대될 가능성에 따라 단기 실적 추정치를 소폭 하향 조정한 것이 핵심입니다... 당사는 현재 전체 NAND 산업 매출을 2026년 약 3,000억 달러, 2027년 약 4,950억 달러로 전망합니다.
결론적으로, 마이크론의 2026/2027/2028년 예상 주당순이익(EPS)을 각각 $74.13 / $184.89 / $265.65로 조정하였으며, 이는 모두 여전히 시장 컨센서스를 크게 웃도는 수준입니다. 여기서 더 중요한 포인트는 당사의 추정치가 2029년에도 마이크론의 EPS가 $160 이상을 유지하고, 2028년까지 누적 잉여현금흐름(FCF) $4,500억 이상을 창출할 것임을 반영하고 있다는 점입니다.
당사가 보기에 이는 이익 창출력의 구조적 재평가(structural reset)로 점차 가시화되고 있으며, 이러한 실적의 지속성과 가시성은 일반 반도체 업계 수준의 멀티플 부여로 이어져야 한다고 봅니다.
당사는 2029년 예상 EPS 약 $165(1년 할인 적용)에 12개월 선행(NTM) P/E 약 11배를 적용해 목표주가 $1,625를 유지하고 '매수' 의견을 재확인합니다."
$MU CEO, in effect:
"For > decade $AAPL has been buying our chips for $5, gluing it inside a metal box, & selling it to consumers for $99 upgrades & laughing at our attempts to get $7.
Now we're charging them $50 & they turned around & raised prices on their customers $250."
IT'S APPLE'S FAULT. They knee capped suppliers at the bottom (as Apple always does), so Micron couldn't invest.
WSJ: "In an interview Wednesday night, Micron Chief Business Officer Sumit Sadana said the company couldn’t make investments during the memory market’s last downturn, when Micron’s gross profits went negative, in part because certain customers took advantage to pay rock-bottom prices.
“We told a couple of the customers who were being very aggressive with pricing at that time that this is not constructive,” he said, without naming Apple, adding that low prices discouraged capital investments. “A lot of the industry investments got shut down in 2023 because of really poor pricing and really poor margins.”