This moment will be discussed in MBA classes and motivational speeches.
There was no added pressure in his mind because for him it was just about winning the next point and the next game.
Doesn't even bother keeping track of the score in his mind. Just win the next point.
TRUMP CALLED JENSEN DURING THE ALL IN SUMMIT AND THEY PUT HIM ON SPEAKER PHONE:
Trump: "I'm telling you it's all a hoax. The data centers are great. They make people wealthy. They make states wealthy. AI is bigger than the internet. These people are playing right into the hands of China. We're not going to let that happen."
Jensen: "You're right, we're not going to let that happen sir."
This is quite the timeline we are living in folks.
We recently released a new report, "Public to Private Equity in the United States: A Long-Term Look," which is an update to a report we published in 2020.
A lot has changed since we last wrote about this topic, including the end of the period of “easy money,” a worsening environment for exits, increased access to capital for private companies, and a surge in capital needs for companies involved in artificial intelligence.
Further, initiatives are in motion to potentially make private equity more broadly available to retail investors - with the pros and cons that might come with that.
One statistic that stood out to me is that there are 592 unicorns valued at $1-3 billion versus 722 public companies with that valuation. So 45% of companies of that size are private. This would not have been the case a generation or two ago.
This report should be of interest to allocators and to students who want to understand the context and evolution of equity markets in the U.S. There are a lot of data. https://t.co/tvigxL41tv
testosterone literally counteracts conformity
give men testosterone and they become less responsive to audience expectations and put more weight on their own judgment relative to other people’s
testosterone is the independent-thought hormone
this explains so much it’s not even funny
Warren Buffett was asked in 1995 what P/E multiple makes a stock expensive. He refused to give a number. Berkshire had started buying Coca-Cola in 1988 at roughly $11 a share, and the stock did not look obviously cheap on current earnings.
By 1995, Coke was expected to earn around $2.30–$2.40 per share. Against Berkshire’s original purchase price, that was less than 5 times earnings. The original valuation did not change. The business grew into it.
Buffett’s point was that a P/E ratio only tells you what a company earns today. It says very little about what the business can earn 10 years from now, how much capital it will need to get there, or what return it can earn on that capital.
Interest rates matter too. A stream of future earnings is worth much more when long-term rates are 5% than when they are 11%. That is why there is no single P/E multiple that automatically makes a stock cheap or expensive.
A company trading at 8x earnings can still be expensive if profits go nowhere. A company trading at 25x can turn out cheap if earnings compound for a decade.
Buffett was not buying a multiple. He was buying the future economics of the business.
Lou Gehrig discussed Babe Ruth's called shot on an NBC radio broadcast on October 6, 1932, only five days after the World Series game at Wrigley.
The recording then went unheard for roughly 88 years before author Dan Joseph surfaced it in 2020.
It is the only known audio of Gehrig discussing the called shot.
That combination of timing and rediscovery makes the recording unusually valuable evidence in one of baseball's oldest debates.
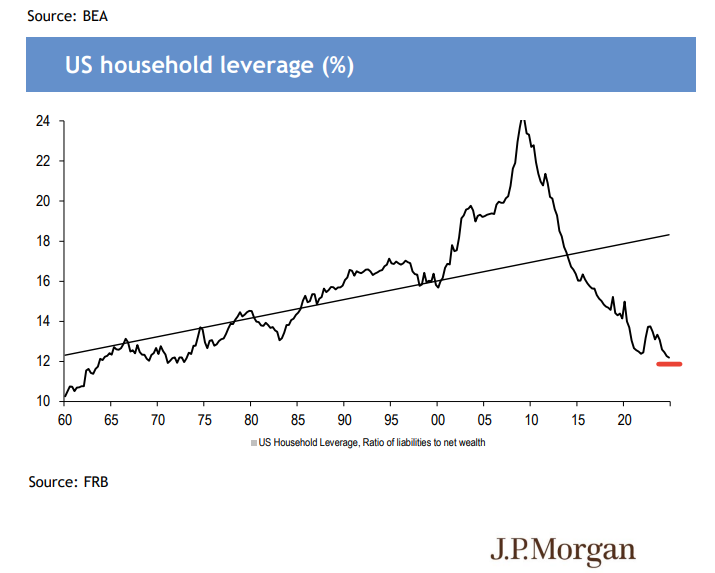
"The more I look at the AI cycle, the more I'm convinced it's less of a tech cycle and more of a real estate cycle," says J.P. Morgan Asset Management's Bill Eigen. https://t.co/Zwrt4mQFT7
Wow, seems like Google is buying Spirit Airlines' enterprise data for $10m (outbidding Mercor at $7.5m).
Basically includes every internal document, email, workflow, and codebase for a once $6B company.
Honestly, $10m for 34 years of operational data really seems like a steal.
In Loudoun Virginia home to more than 200 data centers, tax revenue from data centers has exploded. As a result, over the past 10years, they lowered the real property tax rate every year from $1.145 in tax year 2016 to $0.805 cents per $100 in assessed value for 2026.
@SouthernValue95 has been sharing some pretty killer analysis/takes on hyperscalers and SW. Not enough of it out there these days. He has inspired me to share some of my own sauce. About bioprocessing, of course.
Investors (understandably) became apathetic waiting for the bioP space to recover. I had the luxury of being a specialist tasked with watching the paint dry for a couple years. During this time, I noticed some developments that are likely to grow into meaningful industry tailwinds over the next 5+ years. Surprisingly, nobody is talking about them. I’ll share the biggest one today.
The TL;DR is that antibody drugs are increasingly being formulated as injectables (subQ) rather than IV. The tailwinds are just beginning to materialize, but subQ could add 1%-3% to bioprocess demand growth over the next 5-10 years. This is happening in real-time - a single drug that added a subQ formulation in 2025 is on track to add 150bps to total industry volume demand in 2027.
Monoclonal antibody drugs (mabs) are 85%+ of bioprocess sales for $DHR $TMO $SRT $DIM $RGEN etc. today. Commercial mab volume demand grows 6%-7% as 90% of the underlying drug sales are from cancer, I&I, cardio, or eye drugs, all of which enjoy secular aging tailwinds, expanding indications, and new drug launches. This + pricing - yield improvement is how one bridges to a floor for bioprocessing consumables growth of ~HSD%. 1/
Many of the loser children of my wealthy friends who see no way to emulate the success of their parents, have gravitated toward Mamdani-ism and found community and a sense of purpose by rejecting capitalism as a way to cope with their own failure. Please note they have nor however rejected their trust funds or living subsidies while pursuing their “passions” in NGOs, dabbling in the arts or trying to invest their parents money in “VC”.
Warren Buffett: “When people say, ‘I’m not buying stocks now because times are uncertain,’ I say to them:
‘Well, on September 10th, 2001, were times certain?’ Yeah, you thought they were certain, but you found out the next day they weren’t. On October 18th, 1987, the day before the Dow took that 22% hit…Things were always uncertain in the short term…The longer term is pretty darn certain.”