Iran's leverage over Hormuz contains a paradox:
The more effectively it demonstrates the world's vulnerability to the Strait, the more incentive everyone has to make that vulnerability disappear.
My latest: Building Around Hormuz
https://t.co/N9WA2GMc8G
Read/Share/Subscribe
NOTHING IN YOUR LIFE HAS BEEN RANDOM
Not the person who broke your heart. Not the job that ended. Not the door that closed without warning. Not even the moments you still don't fully understand. You think you were unlucky. You think you chose wrong. You think you should have seen it coming. But every encounter exposed something.
Every ending revealed something. Every disappointment stripped something back. Some people arrived to awaken you. Some arrived to test your boundaries. Some arrived to show you exactly what you will never tolerate again.
And yes, some came to hurt you. But even that pain carved clarity. Even that loss sharpened your self-worth. You weren't being punished. You were being refined.
Growth rarely feels graceful while it's happening.
It feels like confusion. It feels like loss. It feels like the ground shifting under your feet. But nothing was wasted.
Every lesson stretched your capacity. Every fracture widened your heart. Every time you chose to keep going, something stronger in you took shape.
Stop labeling your story as good or bad. It was necessary. It was forming you. Trust the unfolding. Trust the timing. Trust that the same force that dismantled what no longer fit is the one building what does.
Life is not happening against you. It is happening through you. And you are becoming exactly who you were meant to be.
✨🙌🏾💫
Now that climate change and los angeles has shifted to this unprecedented new tropical weather, im hoping we can get monkeys too. Howlers and white faced swinging all around griffith park contented with mangos and papayas
With yesterday's FDA approval of a new treatment for 2L pancreatic cancer, the priority shifts to the development of 1L treatments, like Immuneering’s atebimetinib, currently being evaluated in the global Phase 3 MAPKeeper 301 clinical study. Learn more: https://t.co/LWOCALXvgh
#energy#materials#agricultural all setting up for breakouts. As an Economist with my most basic 101 education I can see that this is inflationary. I'm not liking it. Rarely you can protect yourself against inflation, irrespective of your investment portfolio.
Day to day cost hits from all angles.
"Sounds of Seattle" 1991, festival gratuito pagado por el ayuntamiento para publicitar el talento local. Pearl Jam cierran el concierto a tres días de publicar su primer álbum "Ten" y a un mes de que saliera el "Nevermind" de Nirvana que cambiaría la industria musical de un día para otro.
"Ten" no cuajó en un primer momento tras su lanzamiento y tuvieron que pasar ocho meses hasta que la fuerza de arrastre de "Smells Like Teen Spirit" —y el repentino interés hacia otras bandas grunges por parte de la MTV—, alzaran al icónico álbum al número dos de las listas estadounidenses.
Este fue el último momento en que Pearl Jam no fueron nadie. Tocando en su ciudad, para una mezcla de fans tempraneros del grupo y paisanos que pasaban por ahí y no tenían nada mejor que hacer.
Documentazo.
The U.S. does not need a deal with Iran’s regime. Especially one the regime is unlikely to honor. It needs strategic patience.
The regime is economically isolated, its relevance in the energy world is vanishing, its currency has collapsed, inflation is out of control, and its survival is based on repression, fear, and violence against its own citizens, not popular support.
A dictatorship sustained by terror is not a reliable partner. It is a collapsing system trying to buy time.
Graphs via Bloomberg, Global Energy Monitor
My wife left me today. She said it was because I “never stop talking.” I said the yen carry trade is a $20 trillion leveraged bet that the Bank of Japan will never normalize rates and she said “I’m taking the dog.”
Let me explain to you what I was trying to explain to her.
For thirty years Japan ran rates at zero. Zero. Free money. So the entire planet borrowed yen for nothing and bought literally anything with yield. Treasuries, Mexican peso bonds, Nasdaq, your uncle’s crypto. That’s the carry trade. It’s not a strategy. It’s a short volatility position wearing a business casual outfit.
Then in August 2024 the BOJ raised rates 15 basis points. FIFTEEN. And the yen ripped, the Nikkei fell 12% in a day, and the VIX printed 65. That was the tremor. That was the trailer.
She said “you said this last year.” I said YES AND I WAS RIGHT, THE MARKET JUST FORGOT, and she started packing.
Japan’s debt-to-GDP is roughly 250%. The BOJ owns over half the JGB market. They are the market. There’s no price discovery, there’s a guy in Tokyo with a printer and a dream. Every basis point higher on the long end costs them real money on debt they can never actually repay in real terms. So what do you do when you can’t default and you can’t pay? You inflate. You always inflate. It’s the only tool that doesn’t require anyone to vote.
She said “our marriage counselor thinks you have anxiety.” I said your marriage counselor doesn’t know what the 30-year JGB is doing and she said “NOBODY KNOWS WHAT THE 30-YEAR JGB IS DOING, THAT’S THE POINT, PAUL.”
My name isn’t Paul. That’s how far gone we are.
Anyway I’ve got canned goods, a Kagoshima yield curve chart laminated above the bed, and nobody left to explain it to. So it’s you now. Buckle up.
The Fed’s Quiet Gift to Markets: Actual Price Discovery
After years of parsing every adjective (and some adverbs) in FOMC statements and hanging on the dot plot, many rates desks now face a central bank that refuses to preview its next move. Some traders are angry, which is pretty silly. That frustration is the clearest signal of regime change coming out of this week’s Federal Reserve meeting.
On Wednesday the Federal Open Market Committee kept the federal funds rate in a 3.5-3.75% range for the fifth straight meeting. Three members dissented in favor of a quarter-point hike. The statement itself was short and stripped of the usual language about the future path of policy. Chair Kevin Warsh made the point explicit in his press conference. Markets, he said, should learn to play the ball rather than the referee. The reduction in forward guidance may already be helping prices respond more cleanly to actual economic and market data. In Warsh’s view, this is a change for the better.
Forward guidance became standard practice after the 2008 crisis and returned with force during the pandemic. When interest rates sat at the effective lower bound, central banks used carefully worded promises about the future path of rates to influence longer-term yields and support demand. Under Jay Powell the practice grew elaborate. Statements lengthened, officials spoke often, and markets treated the guidance as a commitment. That approach carried costs and it made markets a little lazy. It sometimes delayed necessary policy shifts when inflation proved stickier than expected. It also trained a generation of traders to focus more on the Fed’s words than on the underlying data.
Warsh has reversed course. At the June meeting the statement shed much of its old language. The chair declined to submit his own projection for the dot plot. This week the same discipline held. Warsh repeatedly declined to forecast future decisions. He argued that financial markets work best when they react to incoming information rather than trying to decode the central bank’s reaction function in advance. When markets mainly reflect what the Fed has already said, the Fed itself loses a valuable independent signal. Better, in this view, for prices to incorporate real economic and geopolitical developments without the filter of constant central-bank commentary.
The immediate frustration on trading floors is (sort of) understandable. Forward guidance offered a form of free information. It reduced certain kinds of uncertainty and created opportunities for those “skilled” at reading the Fed’s tone. Removing it raises short-term volatility and forces desks to rebuild their analytical edge around data, energy markets, labor trends and geopolitical risks. That adjustment is uncomfortable in the short term, but it’s also healthy.
Markets that spend less time second-guessing the next FOMC statement spend more time pricing actual risks. Yields have already begun to move more noticeably between meetings in response to inflation readings and oil prices. That shift improves the quality of the information flowing back to policymakers. It also reduces the moral hazard that develops when investors assume the Fed will always telegraph its intentions and cushion the impact. Over time the result should be cleaner price discovery and a more resilient allocation of capital.
Critics worry that the new approach risks excessive opacity. A central bank that refuses to discuss even its broad reaction function can leave households, businesses and investors guessing in ways that raise risk premia unnecessarily. Some form of transparency about how the committee thinks about inflation and employment remains useful. The distinction between pure rate-path guidance and a clearer explanation of the framework is real and still under debate inside the Fed. Warsh has set up task forces on communications. The experiment is young.
Even so, the direction of travel looks sound. Forward guidance proved valuable in crisis conditions at the zero lower bound. Outside those conditions it often created more problems than it solved. By stepping back, the Fed is asking markets to do more of the work of assessing the economy. That’s a very adult transition.
Traders who adapt will find the new environment rewarding. Those who continue to wait for the next official hint will find themselves at a disadvantage. The anger of the moment is the sound of an old model adjusting. The longer-term gift is a market less dependent on the referee and more focused on the game itself.
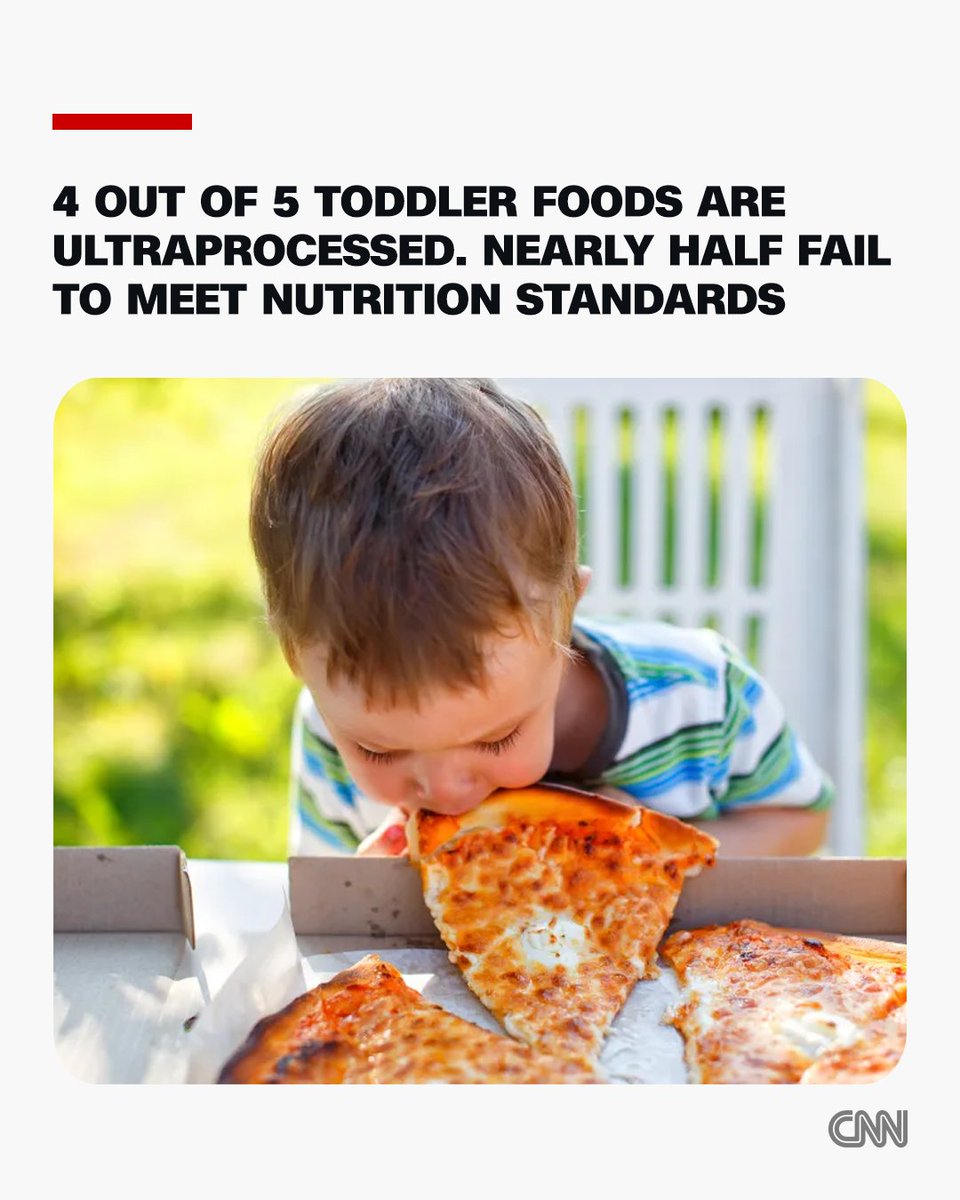
Four out of five foods sold for toddlers in the United States are ultraprocessed, according to research that analyzed more than 2,700 products on grocery store shelves.
Nearly half of those items also failed to meet at least one nutritional benchmark for children set by the World Health Organization. https://t.co/X0DQLi383y
Socialism doesn’t create wealth.
It confiscates it, the political leaders steal it, and it destroys the incentives that generated prosperity in the first place.
Once growth dies and dissent rises, socialism falls back on repression and censorship to stay in power.
⚡️The entire twentieth century may have been an anomaly.
For roughly a hundred years, humans believed wealth came primarily from labor.
Go to school.
Get credentials.
Get a job.
Climb the ladder.
Buy a house.
Retire.
That wasn’t an eternal law.
It was a temporary equilibrium created by industrial capitalism, cheap energy, expanding demographics, and human labor being the dominant source of cognition.
That equilibrium is ending.
Labor is losing its monopoly on intelligence.
Once intelligence itself becomes industrialized, the center of gravity shifts.
The scarce resource is no longer effort.
It is ownership.
Ownership of energy.
Ownership of compute.
Ownership of data.
Ownership of capital.
Ownership of networks.
Ownership of scarce physical assets.
Ownership compounds.
Labor increasingly rents.
That single inversion explains almost everything people think are separate crises.
Housing.
AI.
Political polarization.
Credential inflation.
Falling birthrates.
Loneliness.
Crypto.
Bond markets.
Private equity.
Even the culture wars.
They are all downstream of one structural transition.
Civilization is moving from an economy where people sold labor to one where people either own productive systems or live inside them.
That realization is why so many institutions suddenly feel unstable.
They were built for a world where human labor was the irreplaceable factor.
That world is disappearing.
The second thought is darker.
The greatest wealth transfer of the next fifty years will not happen because AI replaces jobs.
It will happen because AI increases the returns to owning capital while reducing the returns to selling labor.
That is a much bigger event.
The third thought is the one that almost nobody seems willing to confront.
History isn’t converging toward equality.
History keeps oscillating between concentration and diffusion.
Every great technology begins by concentrating power.
Printing concentrated literacy.
Steam concentrated industry.
Electricity concentrated manufacturing.
Computing concentrated information.
AI is concentrating cognition.
Only later does diffusion occur.
People assume the diffusion phase is automatic.
It isn’t.
It has to be fought for.
The final thought is the one that never leaves.
The question of this century isn’t whether AI becomes intelligent enough.
It almost certainly will.
The question is:
Who owns the intelligence after it arrives?
That feels like the real axis around which everything else quietly rotates.