Respected Smt. Nirmala Sitharaman Ji, @nsitharaman@PMOIndia
I wish to draw your urgent attention to genuine and serious difficulties being faced by Chartered Accountants and taxpayers across the country in completing Tax Audit Reports for AY 2026–27 within the present deadline of 30 September 2026.
The Income Tax Department confirms that the tax audit report for FY 2025–26 is governed by the Income-tax Act, 1961 and is required to be furnished one month before the applicable ITR due date.
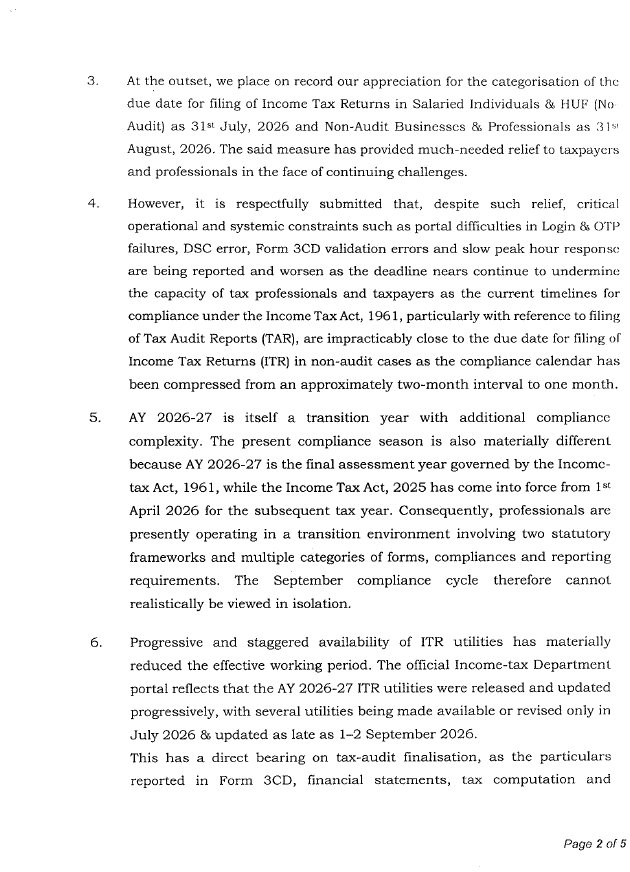
The CA fraternity is working under an exceptionally compressed timeframe due to return-filing assignments, evolving and updated income-tax utilities, extensive reconciliation and verification, finalisation of financial statements, GST, TDS/TCS and other statutory compliances.
This year, the workload has increased further with the implementation of the revised financial-statement framework for applicable non-corporate entities, including the requirement to present comparative figures in the prescribed format. This entails additional reconciliation, regrouping, documentation and professional review, requiring meaningful additional time. Section 44AB is not merely a form-filing exercise. It requires professional judgement, detailed examination of books and records, reconciliation, verification and responsible reporting through Forms 3CA/3CB and 3CD.
The Department itself describes tax audit as a statutory reporting requirement intended to facilitate proper reporting and discourage tax avoidance and evasion.
There is also a practical seasonal constraint. The last days of September coincides with major festivals and observances, including Ganesh Visarjan and Paryushan, resulting in reduced availability of clients, accounting personnel, audit staff and supporting professionals precisely when final clarifications, documents and reconciliations are required.
A tax audit should be an exercise of deep scrutiny—not a race against the clock. Adequate time enables Chartered Accountants to identify discrepancies, verify transactions and ensure that the information ultimately submitted to the Revenue is accurate, complete and meaningful.
Quality compliance requires time.
Responsible certification requires time.
Effective tax administration requires quality audits.
Section 119 of the Income-tax Act, 1961 provides the CBDT with powers to issue appropriate orders for proper and efficient administration of the Act and, in appropriate circumstances, to address genuine hardship.
I therefore request that the Ministry/CBDT may kindly extend the Tax Audit due date for AY 2026–27 from 30 September 2026 to 31 October 2026, along with consequential extension of the related return-filing and statutory compliance timelines, wherever necessary.
With the existing deadline only a few days away, I request that this matter be considered urgently and sympathetically.
An extension of time will enable deeper scrutiny, better professional diligence and more responsible tax compliance.
With regards,
Yours sincerely,
Shaktisinh Gohil
@CANITINCHAWLA@SumitRDas@CA_DHARMESH31@CA_NirmalMishra
Update on TAR
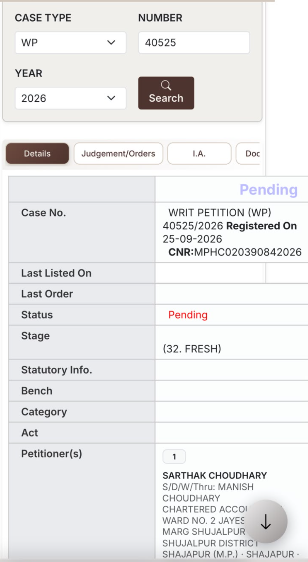
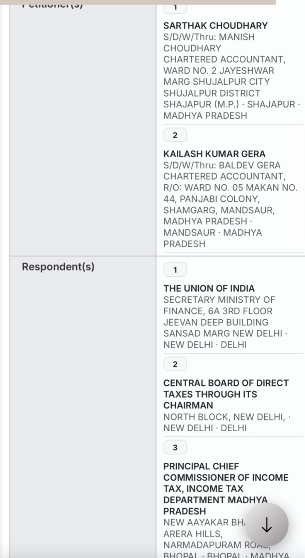
Discussion ongoing with Adv (Dr.) CA Avinash Poddar for filing a Writ Petition in the Gujarat High Court to challenge the Sept 30 deadline. Fighting for fair time, systemic accountability, and relief from portal issues. Stay tuned! #ExtendTaxAuditDueDateImmediately
Retweet For Support and Reach
ICAI has also stepped in on TAR extension issue.
The Rajasthan High Court matter, current tax audit filing statistics, and the heavy pressure caused by August deadlines were discussed with CBDT by the delegation
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/HxvjKGslYO
The genuine concerns of taxpayers and tax prof cant be overlooked.
We strongly req the CBDT to extend the TAR due date and provide adequate time for error-free compliance.
Extn is not a demand for convenienc it is a necessity for meaningful compliance.
#ExtendTaxAuditDueDate
Retweet For Support and Reach
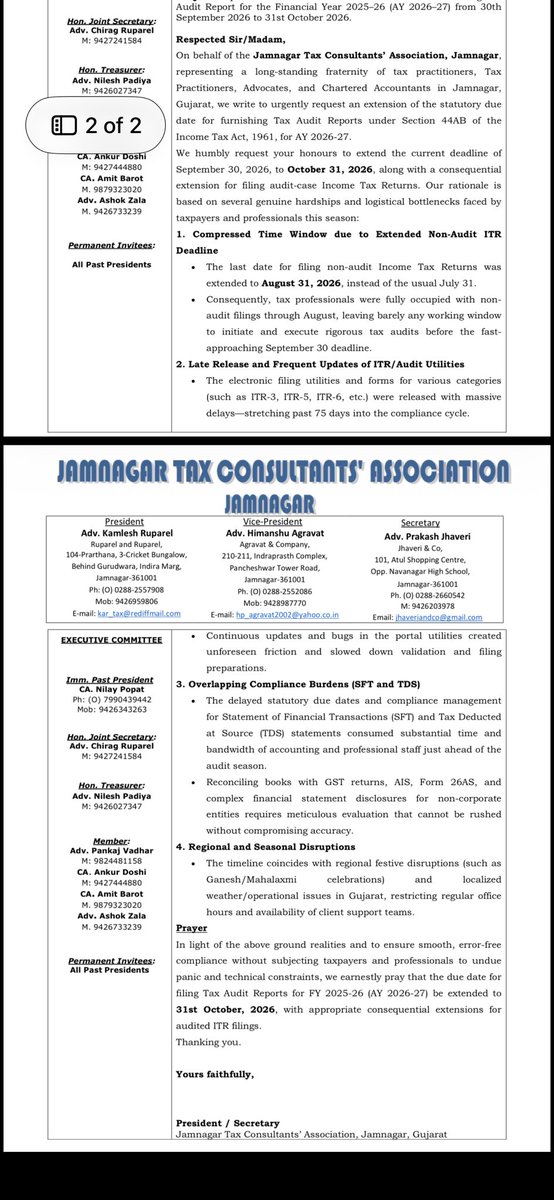
Jamnagar Tax Consultants’ Association, Jamnagar, Gujarat Represent @IncomeTaxIndia For #ExtendTaxAuditdate
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/SmMxCrTcJG
AIMTPA urges Govt to extend the Tax Audit Report deadline from 30 Sept to 31 Oct 2026 and audit-case ITR deadline from 31 Oct to 30 Nov 2026, citing workload pressure and need for adequate time for quality audit and reconciliation. https://t.co/ZUulUj9J3V
Jalandhar CA Association seeks extension of Tax Audit Report deadline for AY 2026-27 from 30 Sept to 31 Oct 2026, citing delayed ITR utilities, increased reporting requirements and compressed audit timelines. It also seeks relief for Forms 10B/10BB. https://t.co/NHf72Yx8tP
Retweet For Support and Reach
Tax Bar Association, Guwahati Assam Represent @IncomeTaxIndia For Tax Audit Due Date Extension upto 31st Oct, 2026
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/SmMxCrTcJG
Retweet For Support and Reach
Tax Bar Association Rajasamand (Rajasthan) Represent @IncomeTaxIndia For Tax Audit Due Date Extension
#ExtendTaxAuditDate
Ram Bajaj
8696424223
For Regular GST Updates, Join this Group
https://t.co/SmMxCrTcJG
Tax Audit Due Dates should be shifted from 30 Sep to 31 October!
The people making rules should consider practical ground realities. @IncomeTaxIndia
ICAI should support members & represent to FM @theicai
Request @nsitharamanoffc
Many CAs on X, Trend #ExtendTaxAuditdate
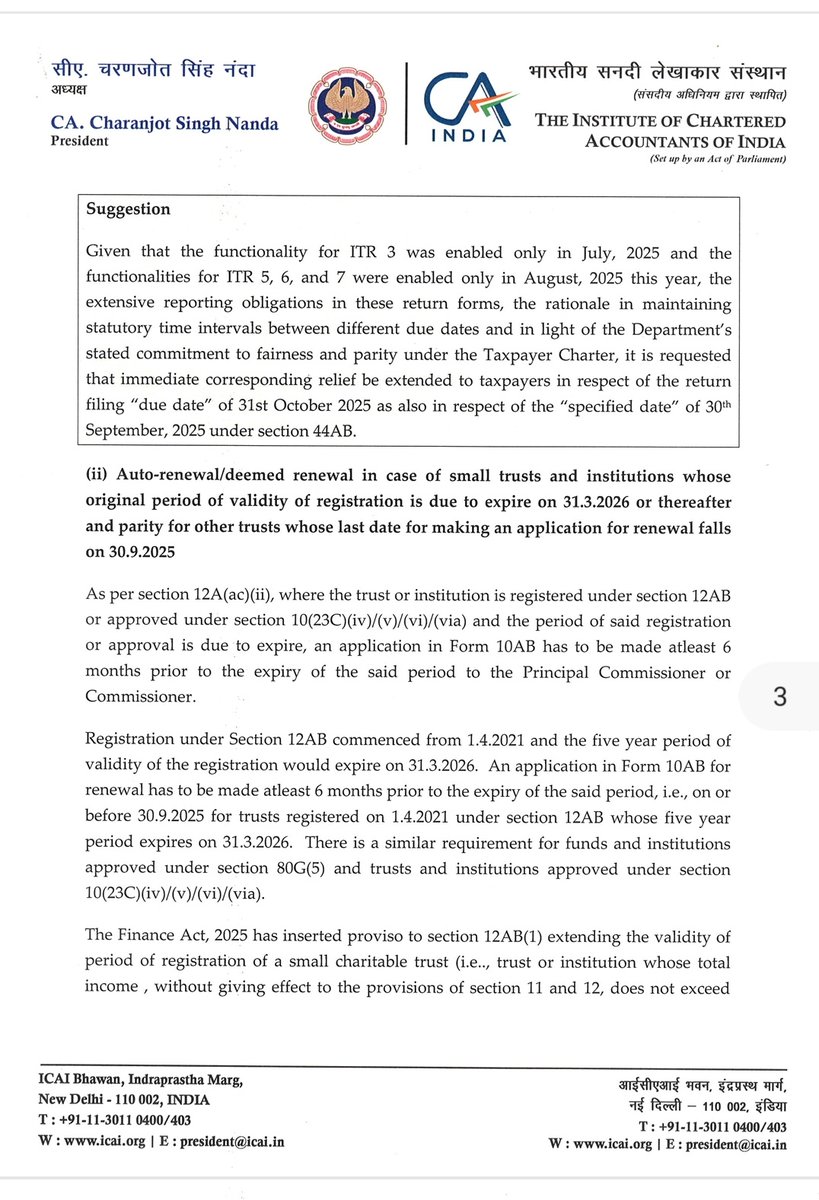
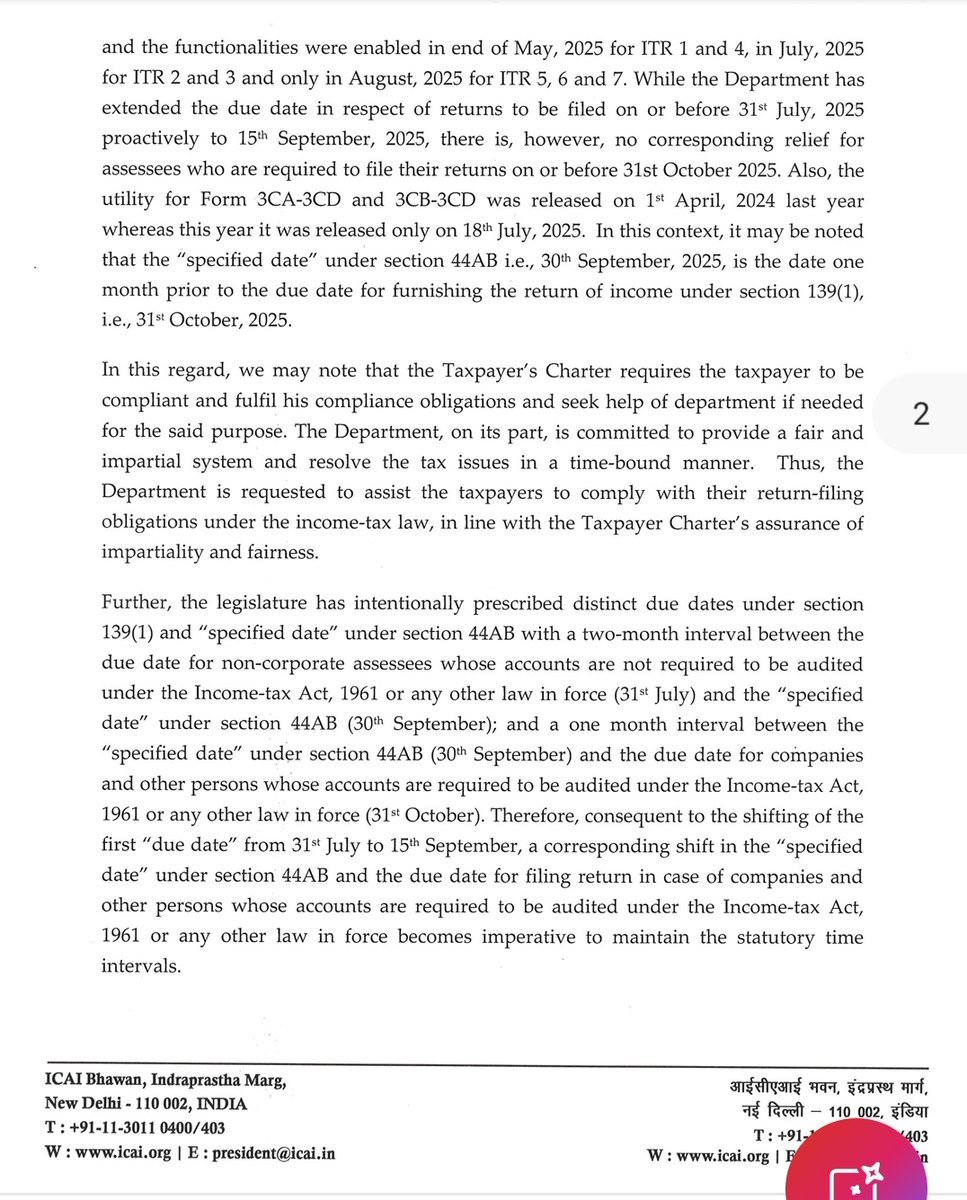
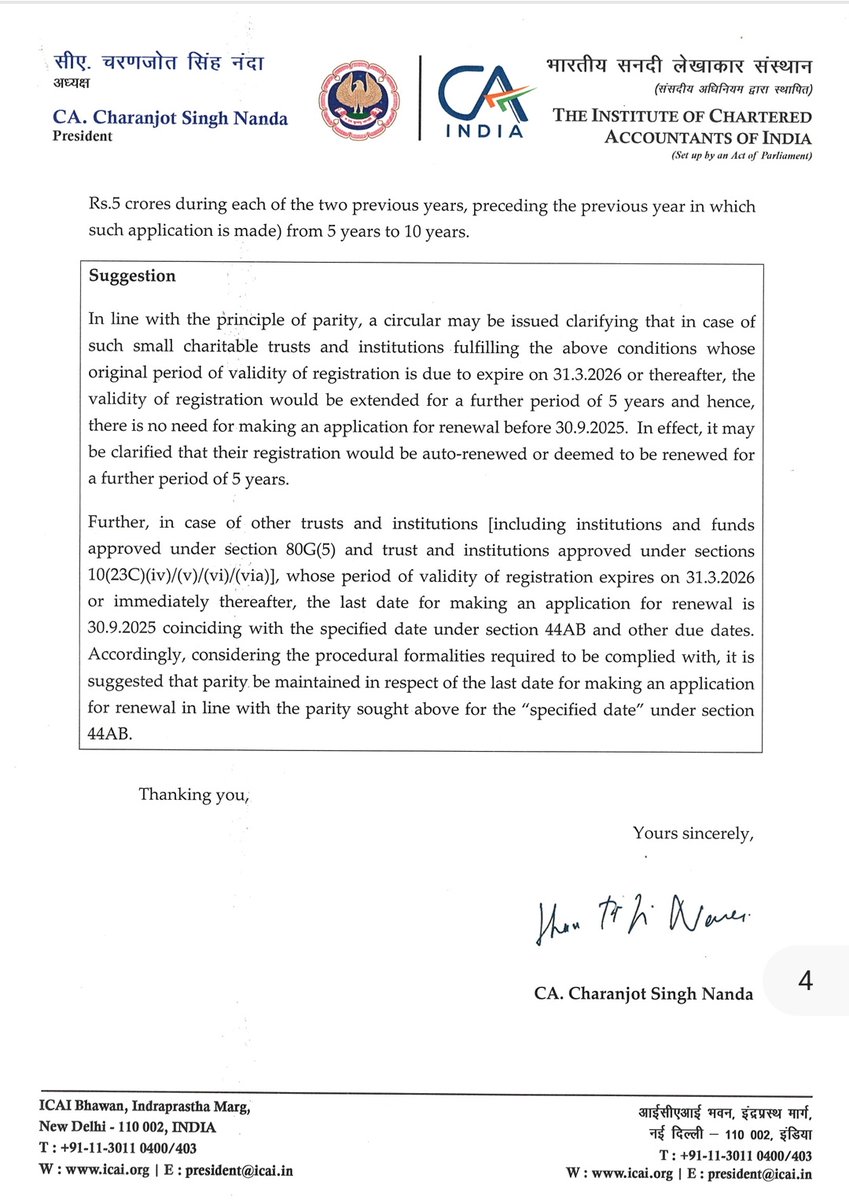
Attaching a copy of the letter by then ICAI President Nanda Sir to the CBDT Chairman from the previous year in Sep-2025.
Please refer to page 2 of the letter, which explains that the law requires a "two-month" gap between the ITR filing date for Non-Corporate and the Tax Audit Report date. ICAI therefore requested an extension, which was later granted, and the date was extended.
This year, a new date of 31-Aug was introduced; therefore, the mandatory gap of two months has been reduced to one month. This was never the expectation of the change. The result is that many members are feeling overburdened and under pressure.
If last year's view of ICAI is correct, then this year also ICAI should come forward and request an extension.
Based on the calls and messages received, I feel the common member is under pressure and is avoiding writing anything publicly, though vocal in person.
ICAI and the Council should open a dialogue and listen to members. After hearing members’ views, they should make the final decision.
रही बात मेरी, अगर मेरे एक भी member को stress feel हो रहा है और extension की ज़रूरत है, तो मैं अपने member के साथ खड़ा हूँ !! हालाँकि मुझे अपने लिए कोई extension नहीं चाहिए, क्योंकि मैं Income Tax और Compliance practice में नहीं हूं। पर अगर कोई member लड़ रहा है , तो मुझे अपने साथ ही समझे !!
और ये आखरी शायरी उनके लिए जो इस लड़ाई को कमज़ोर करने की कोशिश में लगे हुए हैं :
"तुम्हारी सोच के सांचे में ढल नहीं सकता,
ज़बान काट लो, लहजा बदल नहीं सकता।
मुझे भी मोम का पुतला समझ रहे हो क्या,
तुम्हारी लौ से ये लोहा पिघल नहीं सकता!"
~ महशर आफ़रीदी
Judge : Why this harassment to the citizens of this country and put them into stress and tension when you know that the technical glitches are there in the portal ?