Bookmark us at https://t.co/sXc9NSz1mg! We are an upstart anti-media org that uses a smart algorithm to present critical financial news videos daily on $TSLA and electric vehicles. Our mission is to counteract the fear, uncertainty, and doubt spread daily by traditional media.
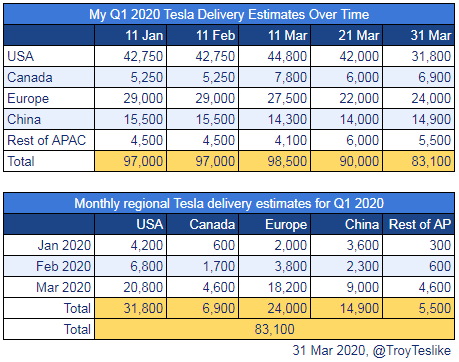
Hi everybody. My final Tesla delivery estimate for Q1 2020 is 83,100 units. First table shows how my est changed over time. Second table shows monthly and regional breakdown for 83,100. My production est is 86,500 Fremont + 15,900 Shanghai= 102,400 units. Be safe & #StayAtHome
@ElectrekCo@fredlambert Even if it’s just a prototype, who is going to buy a Model S today when Plaid is now getting center attention? Don’t understand the strategy here.
@bonnienorman@RobertFoster4MS Even though his thinking is flawed in many ways, if every man in the world practiced it, we’d essentially solve workplace sexual harassment overnight. Wouldn’t you say that’s worth it?
@ValueAnalyst1@Tesla How? They learn about the tech, charging, benefits, directly from the owner that speaks the same language. No one in the real world know who Russ Mitchell or Charley Grant are, nor do they care.
@ValueAnalyst1@Tesla Test drives/rides. Network effect is far more powerful than media, advertisements, etc. Example, Tesla now has approx 5% mkt share within the Indian-American community (2x national avg) even among lifelong Benz/BMW customers after seeing others within the community with a Tesla.
@ValueAnalyst1 “Structural unprofitability” is a fraudulent claim since it was achieved twice last year. Questioning demand is one thing, but this claim is flat out incorrect. It would mean gross margins are negative, in which case even $1 trillion in revenue would produce a net loss.
Energy storage remains the dark horse of the $TSLA cash flow situation in 2019.
Hitting this target would significantly ease the burden of carrying the fate of the company entirely on the Model 3 program’s shoulders.
$TSLA vs $AMZN EBITDA in their first decade post-IPO.
This doesn’t get covered nearly as thoroughly as it should, but TTM EBITDA is the best overall metric to track growth of any company with debt and depreciation. What happens “below the line” is meaningless for LT investors.
$TSLA will meet exceptional, multi-year support at $35 billion market cap. $35B / 172M shares = ~$204/sh. I believe that is where we are headed in the short term. Will back up the truck at that level. We should get there in the next 1-2 weeks.
The lack of visibility, updates, and execution with Tesla Energy has been frustrating. Lesson: don't unveil a product if it will remain vaporware for years. $TSLA shareholders have now sustained, what, $2 billion in operating losses since the $SCTY buyout? https://t.co/hLivqXfbuX
@BarkMSmeagol “Neoen is currently building a 20MW/34MWh battery – again using Tesla technology – at the Bulgana renewable energy hub in Victoria” — is this info publicly known? I don’t recall Tesla talking about this. If true, awesome!
@urdeep@Tesla@elonmusk I think you’ll be fine at these current prices. At $40B market cap, that’s a 1.3X P/Sales and 14X EV/EBITDA for a 30-40% revenue growth stock. To me, this means virtually nothing other than the existing S3X business is currently priced in. The entire pipeline + FSD is free.