So you’re telling me that…
- In App Ads Revenue has a steady 14.6% CAGR since 2019
- Percentage of total mobile gaming revenue coming from ads grew from 35% to 46.5% (2019-2025)
- Revenue to AD Exchanges growing at 16.5% CAGR
- Mobile gaming ad impressions have gone steadily grown 20% annually.
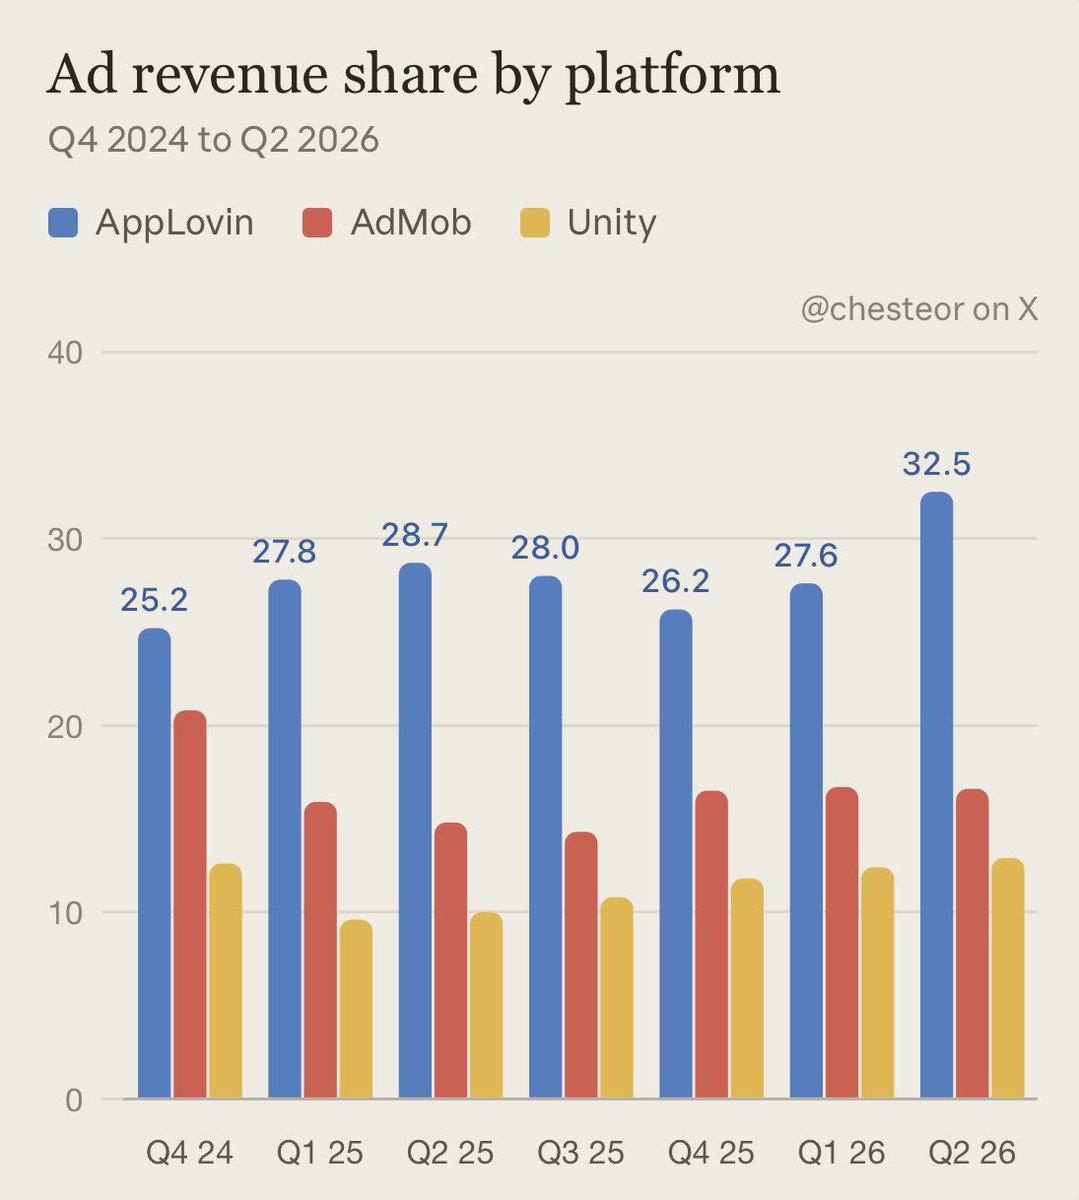
- $APP is growing their mobile gaming ad revenue share to over 32.5%!!!!!!
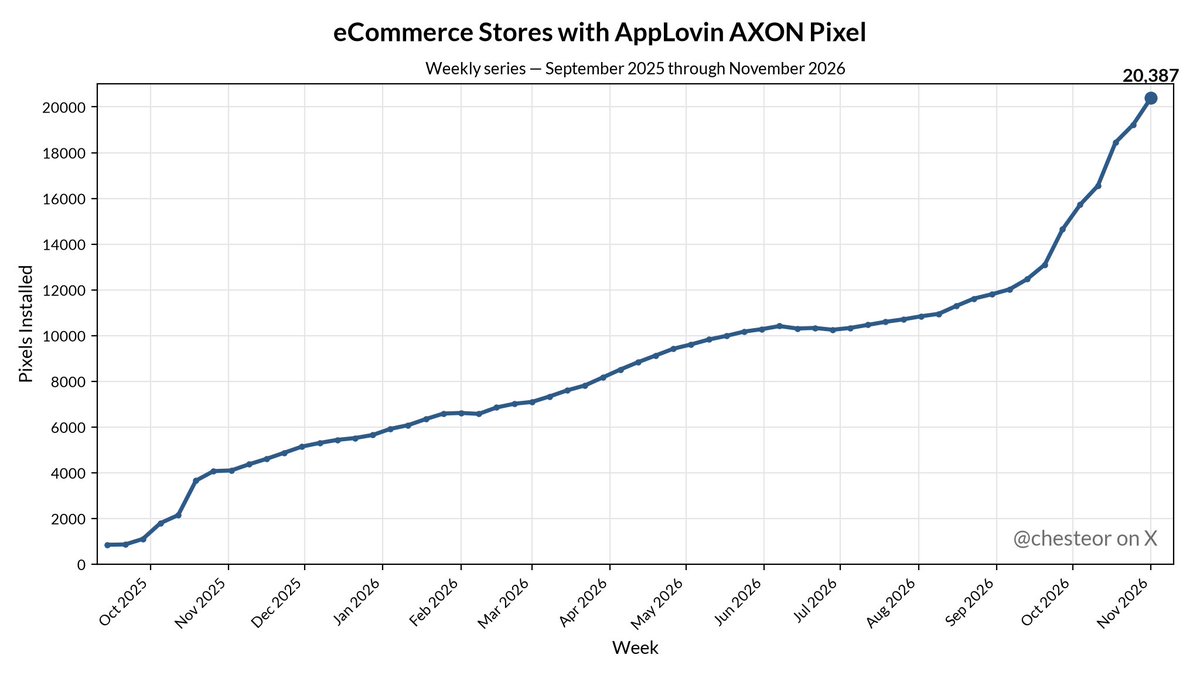
- E-Commerce pixel installations are accelerating
And you’re bearish at a 14x fwd pe??????
$APP Earnings Tomorrow… here are a few things I will be looking out for!
*Revenue Growth:*
> we saw some possible take rate compression last quarter, as is expected when a competitor like $U begins improving. Will be on the lookout for any clues pointing at this
*Buybacks:*
> with ~$1.8B remaining under its share repurchase authorization, I would want to see some confidence coming from management in the form of exercising a good chunk of this.
*FCF & Margin:*
>Adam had said on the call that FCF came in lower due to unfavorable timing of international cash tax and large interest payments, affirming that they are expecting FCF conversion to normalize around 75% of adj. EBITDA
*Cost of compute:*
>something i dont see many people talk about. Adam had mentioned that they are investing in architectural changes that let them build more complex models that benefit far more from additional training compute… *something that fundamentally helps their flywheel spin faster*. Although they are going by the 10% rule, Adam said that they will gladly trade higher compute costs if it drives better model performance and increased revenue. Good news is that he also said Q3 guidance explicitly has this baked into it. We can see ebitda margins come down slightly as a sacrifice for accelerated revenue growth.
*eCommerce discussion:*
> with all of us keeping an eye on ecom pixels, I would love it if we got more clarification on an actual dollar amount we can attribute to it, and what they expect for Q4.
*Growth Drivers:*
> for the past few quarters, pretty much the only driver of growth has been increases in net revenue per installation (58% increase in NRPI year over year in Q2). Although not necessary, i would like to see some growth in the installation volume as well, as its pretty much stayed flat/slightly declined over the past 4 quarters.
Anything im missing? Let me know!
$APP Earnings Tomorrow… here are a few things I will be looking out for!
*Revenue Growth:*
> we saw some possible take rate compression last quarter, as is expected when a competitor like $U begins improving. Will be on the lookout for any clues pointing at this
*Buybacks:*
> with ~$1.8B remaining under its share repurchase authorization, I would want to see some confidence coming from management in the form of exercising a good chunk of this.
*FCF & Margin:*
>Adam had said on the call that FCF came in lower due to unfavorable timing of international cash tax and large interest payments, affirming that they are expecting FCF conversion to normalize around 75% of adj. EBITDA
*Cost of compute:*
>something i dont see many people talk about. Adam had mentioned that they are investing in architectural changes that let them build more complex models that benefit far more from additional training compute… *something that fundamentally helps their flywheel spin faster*. Although they are going by the 10% rule, Adam said that they will gladly trade higher compute costs if it drives better model performance and increased revenue. Good news is that he also said Q3 guidance explicitly has this baked into it. We can see ebitda margins come down slightly as a sacrifice for accelerated revenue growth.
*eCommerce discussion:*
> with all of us keeping an eye on ecom pixels, I would love it if we got more clarification on an actual dollar amount we can attribute to it, and what they expect for Q4.
*Growth Drivers:*
> for the past few quarters, pretty much the only driver of growth has been increases in net revenue per installation (58% increase in NRPI year over year in Q2). Although not necessary, i would like to see some growth in the installation volume as well, as its pretty much stayed flat/slightly declined over the past 4 quarters.
Anything im missing? Let me know!
$APP falls -7% in solidarity to $RDDT
$RDDT’s ARPU increased by 35%+
$META’s ARPU increased 20%+
Meta drops because of dilution and capex
Reddit drops because of engagement and user issues
What will happen with $APP ?