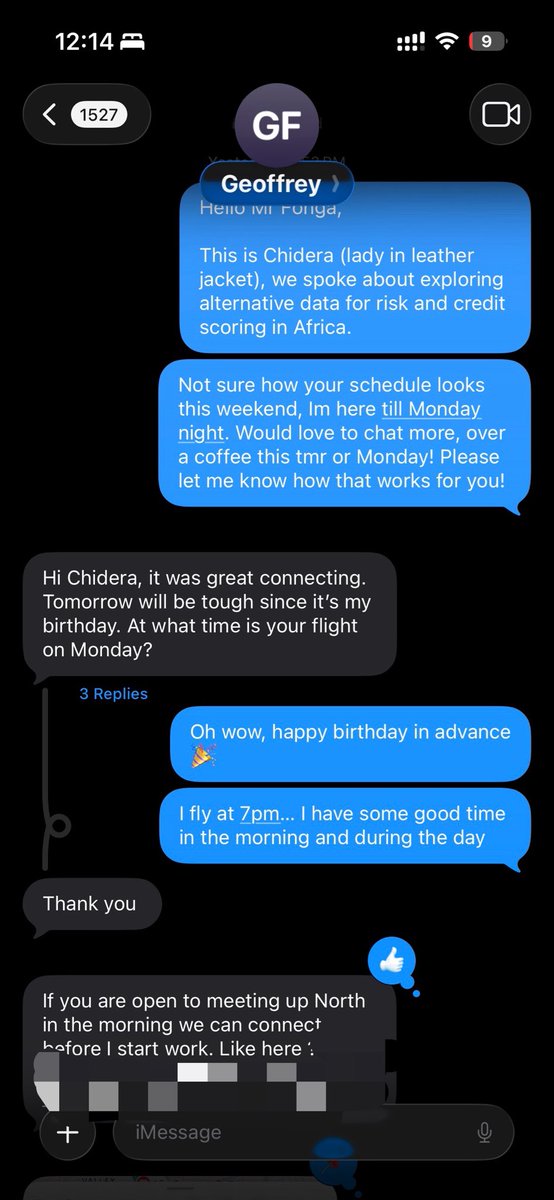
@beyondafricaorg was super fun! Great weekend in Austin (running on like 8 hours of sleep total 💔).
Had to find Mr. Fonga after he got off stage and convince him to grab coffee with me 😂
We talked about a lot, but particularly alternative approaches to credit risk scoring for small businesses in Africa.
@cyberomin A borrower who takes loans from several lenders in the same week looks clean to each of them. If every lender could see the others' open loans at the moment of decision, that stacking would show up before the second and third loan go out.
Whether three months works depends on the sector cycle. On that 0% figure, is repayment taken from the buyer's payment at harvest, or does the farmer have to find the cash afterwards? The default risk looks very different in each case. interesting interview.
Would you lend money to a farmer and expect them to pay it back in three months?
Agriculture has long been treated as a risky business by banks. But Henry C. Onwuzurigbo, CEO of @ZenithBank_Gh says his bank has grown its agricultural lending portfolio while maintaining 0% non-performing loans in the sector. So what's different?
At the Africa Financial Summit in Luanda, Angola, he explains why lending to a livestock farmer, a poultry farmer and a cocoa farmer cannot follow the same repayment structure.
@BarrackPB gets into the details with Henry raising a bigger question: have banks misunderstood the business of financing agriculture?
#AFIS2026
Borrowing against the coins swaps a sale for liquidation risk. If the price falls far enough, the lender sells the collateral for you, so the useful question is where that trigger sits and how long a borrower gets to top up.
More marketing. More partnerships. More features. More expansion.
But are all these activities actually moving your Web3 project forward? 🤔
Growth without a clear direction can leave teams spending resources on things that don't address their biggest challenges.
A good strategy starts with understanding where the project stands, identifying what needs attention, and deciding which opportunities deserve priority.
Sometimes, progress doesn't come from doing more.
It comes from making better decisions about what to do next.
That's where strategic advisory can make a difference.
A bureau only helps a lender if other lenders report into it and it covers people who never held a bank loan. Does it pick up small merchants whose history sits in mobile money or cash, or only formal bank borrowers?
A repayment rate depends on what gets counted: loans or money value, on the due date or by season end, and whether group members cover each other's shortfall. Which of those is the 98% measuring?
One Acre Fund and the Western Donor World: The Moral Hazard of Subsidized Wage Inequality
In global development circles, One Acre Fund is celebrated as a model social enterprise with a 98% loan repayment rate.
Our forensic analysis of 15 years of IRS Form 990 filings (2011–2025) reveals a different reality: a $365M subsidized institution built on zero-cost capital, deep labor disparities, and coercive micro-debt.
Key Findings:
-The Zero-Cost Moat: Scaled on 0% WACC philanthropic grants from Gates, MasterCard, and Pershing Square, creating a subsidized monopoly that undercuts domestic agro-dealers and African agtech startups.
-The 100x Wage Divide: C-suite and US leads command $186,000–$281,000+ USD packages, while 9,200+ frontline African field officers earn ~$1,850–$3,200 annually with near-zero benefits.
-The SROI Collapse: While reporting a 5.7x SROI, net donor subsidies in Kenya hit $91 per farmer to yield just $116 in impact—a meager 1.7x return when competing against state-subsidized fertilizer.
-Expatriate Enclaves: Despite PR claims of a "99% African" workforce, non-African expatriates hold 70% of top Job Level 14 roles and lead 60% of sovereign country programs.
-The 98% Myth: Near-perfect coercive loan recoveries are driven by 16-peer joint-liability groups, forcing neighbors to liquidate household assets and sell grain into post-harvest price gluts to clear collective debt.
Read the full investigation on Boardlot Africa:
https://t.co/5EVhcjrSui
#GlobalDevelopment #SocialImpact #NonProfitGovernance #SiliconSavannah #AgTech #CorporateGovernance #BoardlotAfrica
Telco and retail data can show income rhythm for someone with no bank history, like regular airtime top-ups. The open question is whether a borrower can see which signal hurt their score and dispute it when it's wrong.
According to FirstRand's privacy policy document, FNB collects personal information for credit risk assessment from social media profiles, telecommunication providers, online shopping retailers and website cookies.
https://t.co/g1zeUtO3Uk
One thing I keep learning as I build is that there’s no end to better ideas. You don’t need to have everything figured out. You just need to be clear on what you’re doing right now and what your next immediate step is. Not the next 10 steps. Just the next one.
It’s been months of building this with one of the most amazing teams, and I’m so glad to see how far we’ve come.
We initially started BOX as a B2B2C model, selling to banks and fintechs so they could offer it to the businesses they already serve. BOX gives those businesses the tools to manage their sales, payments, inventory, bookings and day-to-day operations in one place.
For the bank or fintech, that means becoming much more embedded in how their business customers operate, which creates opportunities for deeper customer relationships, stronger retention, new revenue lines and, with better visibility into business cash flow, products like cash-flow-based lending.
Since then, we’ve sold to our first pilot bank, have more in the pipeline, got into Antler, and now we’re opening BOX up for business owners to use directly.
Because we believe everyone deserves to experience what running a business feels like when you don’t have to spend your day reconciling payments, updating spreadsheets, checking screenshots, or jumping between five different tools.
Say you run a retail store and also take orders through Instagram and WhatsApp.
With BOX, you can generate secure payment links right from the conversation. Your customer gets an invoice and can pay by card or transfer. Once they pay, the transaction is recorded and your inventory is updated automatically, even if you have multiple locations.
No more wondering what a payment screenshot was for. No more trying to figure out whether an alert is real. And with the right controls in place, you have a much clearer view of what your staff are selling and collecting.
For in-person sales, BOX turns your existing phone or tablet into a softPOS. Accept payments, scan inventory, and fulfil orders directly from the app.
And because everything is connected, you can see your revenue, best-selling products, most loyal customers and business performance across channels and locations from one place.
And retail is only one part of it.
Whether your business model involves selling a physical product, selling a digital product, selling a ticket, selling a service, taking a booking, taking a reservation, selling a membership, selling an experience, or some combination of these, BOX was built for you.
Box is a unified commerce platform for multi-vertical and multi channel businesses.
- Services: Multi-chair salons, barbershops and spas
- Food & Beverage: Restaurants, cloud kitchens and cafés
- Stays: Hotels, shortlets and guesthouses
Fitness: Gyms, studios, padel and racquet clubs
- Events: Concerts, conferences and parties
- Consultants: Scheduling, invoicing and digital products
Different businesses. Different ways of selling. One BOX.
We’re looking to onboard our first 50 users, and because you’ll be among the first, we’ll work with you to set up your operations end to end. We’ll also be on call to help you figure things out as you go.
So if you know a business owner who is tired of juggling different tools, spreadsheets, payment screenshots and WhatsApp orders, tell a friend to tell a friend.
Come open the BOX with us. ❤️
Every good relationship starts with a proper introduction, so here's ours.
We're Box. We help businesses run everything they sell from ONE place: build a website, sell products, take orders, sell tickets, run a restaurant, offer subscriptions, send invoices, capture leads, etc.
Every good relationship starts with a proper introduction, so here's ours.
We're Box. We help businesses run everything they sell from ONE place: build a website, sell products, take orders, sell tickets, run a restaurant, offer subscriptions, send invoices, capture leads, etc.