My Free Substack subscription offer:
* Full valuation workings with traceable assumptions and the math behind every figure
* Access to my own portfolio performance and holdings
* Discuss my thoughts on the market
* Share my knowledge with subscribers who wish to learn investment analysis
* Daily undervalued stock charts with analysts' consensus
Link: https://t.co/VDnlGkQdn2
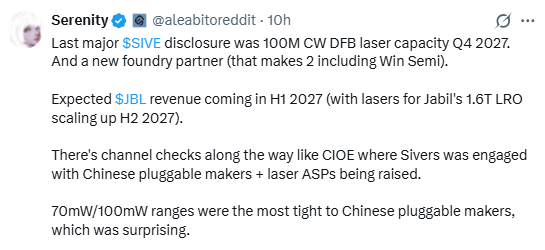
$SIVE chart is an utter abortion. Looks like 10-12 is in the cards after today. ATH was 110, so this would he a 90%+ decline from ATH. Great job Serenity! 🥳
@Nostre_damus Kremlin is playing with a carrot puppet like a baby. Will not happen. There is no deal and there will be no deal until Trump is out. Zelensky is more popular in the US than Trump. What the hell are you talking about, kid? 😄 All your pedo can do is lick Putin's ass.
@commonsenseplay There will be no peace deal. Neither before midterms, nor 31 dec or next year. Kremlin already described European/Ukr recent proposal as useless.
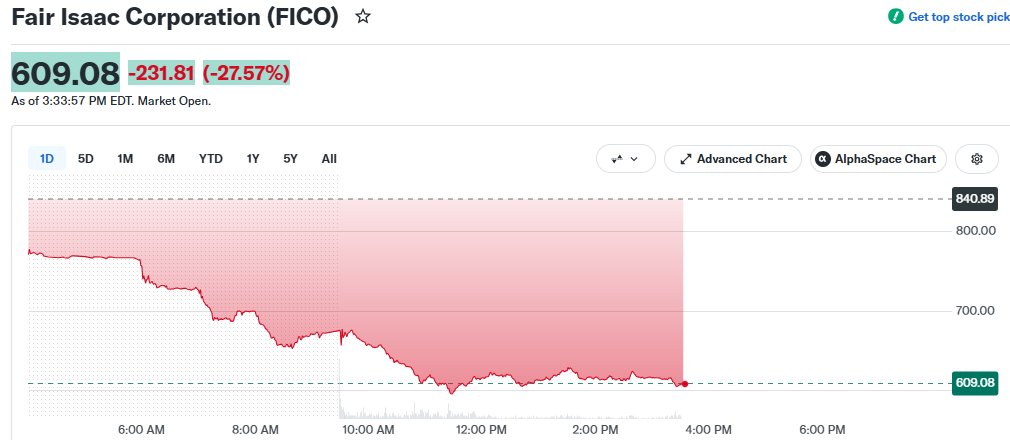
A permanent price war is not the outcome I would expect for $FICO. The more common pattern when a monopoly becomes a durable duopoly is:
monopoly pricing → aggressive entrant discounting → incumbent response → market-share rebalancing → eventually more rational oligopoly pricing.
FICO already appears to be in the first two stages.
What is happening right now is genuine price competition. TransUnion announced $0.99 per VantageScore 4.0 mortgage score in March 2026. Equifax separately offered VantageScore 4.0 at $4.50 through 2027 and even offered it free to some customers buying FICO scores. FICO, meanwhile, introduced its direct licensing program, offering either $10 per score, or a performance model of $4.95 per score + $33 when the loan funds. They explicitly said the $4.95 price represented roughly a 50% reduction in the average per-score charge going into resellers.
So this isn't theoretical. The arrival of VantageScore has already forced a change in FICO's pricing architecture.
And FHFA now lets approved lenders choose between Classic FICO and VantageScore 4.0, even on a loan-by-loan basis, which makes competition more meaningful than if lenders had to commit permanently to one system.
Historical analogies
$T vs MCI/Sprint. Initial competition produced dramatic price reductions; later competitors often moved headline prices together while fighting through discounts.
$Visa/ $Mastercard. Two dominant networks coexist with enormous margins; fees did not collapse because network effects and switching constraints protect economics.
$SPGI / $MCO / Fitch. Competition emerged, but incumbents remained deeply embedded and highly profitable because customers need recognized standards
$KO / $PEP. Strong brands allow both firms to raise prices while competing heavily elsewhere.
The AT&T example is particularly interesting. After AT&T's virtual monopoly weakened, the FCC reported that interstate long-distance rates fell more than 40% after 1984. But competition didn't remain a simple price war forever. By the 1990s, the FCC observed that AT&T basic-rate increases were frequently matched almost immediately by MCI and Sprint. At the same time, the companies fought much harder over attractive high-volume customers through discounts: effective rates for heavier users fell roughly 15–28% between 1991 and 1995.
That is exactly the kind of equilibrium I could eventually imagine in credit scores:
FICO raises list price 4%.
Vantage raises 3%.
But Rocket Mortgage gets a huge volume rebate from Vantage.
FICO responds with a negotiated contract.
Small lenders pay something closer to list price.
In other words, headline pricing can rise while effective pricing remains competitive.
Visa/Mastercard shows why two players don't necessarily destroy pricing power
Payment networks are another useful comparison because the product is a very small cost relative to the economic transaction, while network acceptance and installed infrastructure matter enormously. Despite substantial competition between networks, Federal Reserve data show average network fees per transaction rose approximately +32% in 12 years. So Visa and Mastercard didn't spend decades continuously undercutting each other toward marginal cost. Why? Because customers don't choose exclusively on price. They care about acceptance + reliability + infrastructure + historical data + integration + risk + brand recognition.
That's also true for FICO. A lender probably isn't going to change its credit-risk ecosystem to save $0.50 on a score unless the total economic benefit is meaningful.
Moody's/S&P may actually be the best analogy
Credit ratings are particularly similar to credit scores because you're buying a trusted standardized opinion of credit risk that is embedded in regulation, contracts, models and financial infrastructure. There are ten SEC-recognized NRSRO rating organizations today, yet as of the end of 2025 S&P had about 1.078 million outstanding ratings and Moody's about 684,000, versus roughly 2.193 million across all NRSROs. Together that's around 80% of the outstanding ratings count.
New competition didn't commoditize the product.
An old SEC submission from Fitch is revealing: "Fitch argued that its emergence as a third serious competitor to Moody's/S&P introduced price competition and innovation."
Yet decades later Moody's and S&P remain enormously important because recognition and embeddedness matter.
What could happen to FICO from now:
100% FICO → 70% FICO / 30% Vantage might be much more realistic than:
100% FICO → 50/50 → prices collapse toward zero.
But FICO has one important disadvantage
VantageScore is jointly owned by Equifax, Experian and TransUnion. That changes the economics considerably. The bureaus don't necessarily need to maximize the standalone royalty on VantageScore.
They can make money from: credit-report data → mortgage reports → related products → lender relationships → other analytics.
Consequently, they potentially have an incentive to price VantageScore very aggressively to weaken FICO's royalty extraction. TransUnion's $0.99 offer illustrates exactly this possibility. That's more dangerous for FICO than competing against another standalone scoring company that needed to generate a 70% operating margin from the score itself.
I therefore expect two different periods
2026-2029: unusually intense competition
This is when Vantage has the strongest incentive to sacrifice price for market share. Imagine Vantage currently has 10% and wants 30%. An extra dollar of price today is much less important than convincing Rocket, UWM, Wells Fargo, JPMorgan and large resellers to redesign processes around Vantage.
Once those systems are built, Vantage becomes much harder to remove.
So during this period I would expect Vantage price << FICO price and FICO responding through discounts, direct licensing, contract changes and potentially lower net pricing.
That is probably the greatest risk to FICO's historical pricing-power story.
But at 60/40 or 70/30, the incentives change
Suppose eventually FICO = 65–70%
Vantage = 30–35%.
At that stage, Vantage no longer has as much incentive to destroy industry pricing. Consider the game theory. If FICO charges $5 and Vantage charges $4 both earn attractive economics. If Vantage cuts to $2 and FICO responds with $2.50; Vantage captures some share but destroys the value of the entire market. Then FICO cuts again. Both become worse off. There is therefore a natural incentive in many mature duopolies for price competition to become less aggressive once market shares stabilize.
This does not require collusion. Competitors can independently observe one another's pricing and realize that constantly undercutting is economically unattractive.
Visa/Mastercard, Coke/Pepsi, Moody's/S&P and many airline markets exhibit versions of that behavior.
There is one reason FICO/Vantage may remain more competitive than those examples
FHFA explicitly wants competition. Its stated rationale for introducing multiple credit scores includes promoting competition and lowering costs. And crucially lenders can currently choose the scoring model loan by loan.
That's different from Visa/Mastercard. A mortgage lender doesn't necessarily have to abandon FICO completely. It could say:
FICO gives us the better economics for this borrower → FICO.
and:
Vantage gives us better economics here → Vantage.
That creates ongoing price elasticity.
So I wouldn't assume FICO eventually returns to its previous monopoly pricing behavior.
What I think the most likely equilibrium looks like
It is not FICO $10 → Vantage $1 → FICO $1 → permanent commodity pricing. And probably not FICO $10 → Vantage $9 → both increase 10% every year forever.
More likely:
Phase 1
FICO monopoly price
↓
Vantage enters very cheaply
↓
FICO discounts/restructures pricing
↓
Vantage gains meaningful share
Phase 2
FICO remains premium incumbent
Vantage remains cheaper challenger
↓
both gradually raise prices
↓
large lenders negotiate substantial rebates
The result could therefore be:
lower price level + lower pricing growth than monopoly FICO, but still excellent economics.
And there's an important upside to this thesis: FICO doesn't need to retain a monopoly for the Scores business to remain an extraordinary business.
If FICO ultimately holds, say, 70% of a two-player market, with high switching costs, regulatory acceptance, decades of historical performance data and pricing increasing roughly GDP+ instead of 10–20% annually, it can still generate extremely attractive returns.
The part of the FICO thesis that I think has genuinely changed is therefore not "FICO pricing power disappears", but "The era in which FICO could repeatedly raise mortgage-score prices almost irrespective of competitive response may be ending."
Historically, the AT&T example suggests the first few years after monopoly can be painful for price; the Visa/Mastercard and Moody's/S&P examples suggest that once the oligopoly settles, rational pricing can return-but probably from a lower base and at a slower rate.
Dude still can't settle with $SIVE after squeezing subscribers with this hype nonsense at 100. Yes, still 4x on 1Y, but those who bought at 100? Minus 75%, close to complete wipeout.
@Gurberot1@DissentOpinon А где здесь Мальта? И почему Россия воздержалась от голосования за эту резолюцию? Должна же была против голосовать по твоей логике. А вообще твой комментарий это манипуляция. От ответственности не уйдешь 😉. Вернемся к теме, умылся кровью сегодня или пока нет, сочинец?
@Gurberot1@DissentOpinon Не смеши меня. Это базовый набор, для нормальной жизни нужно много чего другого. Хотя бы знать что твоих детей не отправят на убой в Украину! А если такой уверенности нет, то коттедж не спасет.
Kremlin will not stop any time soon. It is also not ready for negotiations. Their army is losing 30k per month in wounded/killed, roughly 5x more than Ukrainians. But they still have the capacity to continue. Here is why.
They are recruiting new men at a rate of 30k per month.
At this recruitment rate, Russia is not in a situation where its army is likely to simply “run out” within a few months. But the margin of safety has narrowed considerably.
The key constraint is not Russia’s total male population. It is its ability to keep finding tens of thousands of people every month who are willing to sign military contracts, and then turn those recruits into effective combat replacements.
In September 2026, according to Janis Kluge’s calculations based on Russian regional budget payments, roughly 29,900 people were recruited. Total recruitment for January–September was around 263,000, versus approximately 292,000 during the same period in 2025.
That implies recruitment is down by roughly 10% year over year, despite substantially higher financial incentives. The average regional cost of attracting one contract soldier has risen to approximately RUB 1.9 million, around 30% higher year over year.
At the same time, estimates of Russian battlefield casualties are of roughly the same magnitude or higher.
CSIS estimated Russian casualties during the first half of 2026 at approximately 30,000-34,000 per month, compared with recruitment of around 27,000 per month.
However, this comparison needs an important qualification: casualties include killed, wounded and missing personnel. Some wounded soldiers eventually return to service, so you cannot simply subtract total casualties from recruitment.
A potentially more useful estimate comes from Kluge’s analysis of Russian military compensation payments. He estimated roughly 21,000 permanent departures from the contract force per month between mid-2024 and mid-2025, including soldiers killed, seriously wounded or otherwise no longer receiving combat-related payments.
His estimate implied that Russia was replacing almost 45% of its contract-force personnel every year, although Kluge himself stresses that there is substantial uncertainty around this calculation.
The basic arithmetic therefore looks approximately like this:
Result
* 20–25k/month permanent losses -> Recruitment of ~30k/month -> Force size still grows
* 30k/month permanent losses -> Recruitment of ~30k/month -> Roughly stable manpower
* 35k/month permanent losses -> Recruitment of ~30k/month -> About −60k personnel/year
* 40k/month permanent losses -> Recruitment of ~30k/month -> About −120k personnel/year
These figures are not forecasts. They simply illustrate how close Russia may be getting to the point where recruitment only replaces permanent losses rather than expanding the force.
Will the Russian army be “ground down”?
In purely numerical terms, probably only slowly. In qualitative terms, potentially much faster.
Russia's force deployed against Ukraine remains very large. Budget-based estimates have suggested roughly 550,000 contract personnel plus fewer than 170,000 remaining mobilized soldiers, implying a total force of around 700,000.
Therefore, even if the force were shrinking by 5,000-10,000 personnel per month, that would not produce a sudden collapse.
The more serious issue is quality.
Replacing hundreds of thousands of soldiers every year means continuously losing experienced infantrymen, junior officers, NCOs, specialists and accumulated battlefield experience. Newly recruited soldiers may replace the headcount, but they do not immediately replace the experience of soldiers who have already spent one or two years fighting.
There have also been signs that maintaining recruitment is becoming increasingly difficult. Russian authorities have repeatedly increased signing bonuses and expanded the categories of people eligible for military service.
That matters because roughly the same recruitment rate is now costing the state considerably more money.
A recruitment pace of around 1,000 men per day in 2026 therefore appears harder and more expensive to sustain than the same pace was several years earlier.
How long can this continue?
The current voluntary-contract recruitment system appears capable of supporting the war for many more months, and the available evidence does not point to an imminent manpower collapse.
But extrapolating the same system unchanged for another 3–5 years is much more uncertain.
The most important indicator I am watching going into 2027 is therefore not simply headline casualty numbers. It is the relationship between:
Recruitment ÷ permanent manpower losses
If Russia continues recruiting around 30,000 people per month while permanent losses remain below that figure, it can broadly maintain or even expand its force.
If recruitment begins falling while permanent losses stay high, the situation changes.
For example, if monthly recruitment were to fall:
30k → 25k → 20k
while battlefield intensity remained broadly unchanged, that would be a much stronger indication of manpower exhaustion than another large headline casualty estimate.
At that point, Russia would increasingly face three broad options:
* Reduce the intensity of military operations, lowering manpower losses.
* Increase financial incentives and recruitment pressure further to attract enough contract soldiers.
* Expand compulsory mobilization again to compensate for insufficient voluntary recruitment.
So the Russian army is unlikely to suddenly “run out” of soldiers. The more realistic risk is a gradual deterioration: recruitment becomes increasingly expensive and difficult, troop quality declines, and eventually the government has to choose between lower military intensity, much stronger recruitment measures, or additional mobilization.
That is why I am tracking monthly recruitment. A sustained decline from around 30,000 recruits per month toward 20,000-25,000, combined with unchanged battlefield losses, would be one of the clearest indicators that the current manpower model is starting to come under serious strain.
https://t.co/IBsBxbyh1k
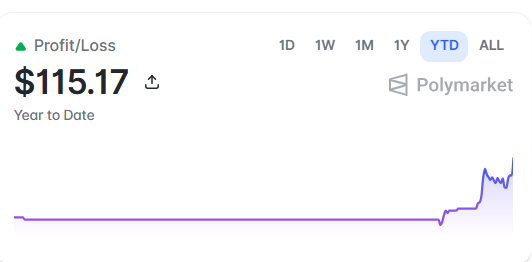
First 100 USD made. That's 10% in less than 2 months. This war will only stop if one of the parties falls. Ukraine will not fall any time soon, because they have Western support. Russia will not fall because, in a war of exhaustion, they still have capacity.
I look at it as high risk / high reward bet. Very similar to the stock market, where we are placing bets on companies. Will bring it to 10% of the portfolio by the end of the year.