I've long been of the view that this is the right approach to take.
Firstly, because it's a much larger TAM, than a “tech-stock” that requires revenues, which are likely to dwindle in the future as Ethereum scales.
Secondly, Ethereum, at its core, is a financialised digital commodity with an architecture and roadmap that suits this classification and valuation approach.
Decompose Ethereum’s value into different parts: security value (~$100bn) and market premium, which composes the “risk asset” beta that Ethereum has.
Expanding on why I believe "ETH as store of value (SoV)" makes much more sense to focus on than "ETH as fee-burning token".
Three primary reasons:
1. ETH as fee-burning token never was as strong as it seemed
2. Optimizing for ETH as fee-burning token would demand Ethereum and ETH function in ways that are very hard to make compatible with decentralization and capture resistance.
3. Meanwhile, optimizing for ETH as SoV is aligned with Ethereum focusing on its unique strengths (decentralization and CROPS)
EIP-1559 (including its burn) is fine and good, we should keep them. But we should not feel sad if fee burn is < 10% of breakeven indefinitely; the value of ETH comes from elsewhere.
The core idea: the big thing that people appreciate about Ethereum is decentralization and CROPS. The main pragmatic benefit that these things translate into is stability. SoV is the category where that is not an unneeded extra we merely put effort into for ideological reasons, but rather a pragmatic strength from the perspective of people putting in their assets. And in the era of AI disruption, stability will be highly valued.
Ethereum is a financialised digital commodity with the best-in-class security, decentralisation, liquidity, institutional mindshare, lindy, strong consensus behind its CROPS roadmap.
A SoV fits this architecture, outlook and valuation approach.
Really well written ethereum:native thesis that once again fails to explain ANY reasons why the token is valuable. 10 years into this experiment and the most well thought out investment theses for owning an L1 token are still just a bunch of gobbledygook rationales for why the protocol is cool, and then a relative value argument vs some other asset that has no way of being valued.
An L1 token by itself has almost no value. The value comes from the DEX and the stablecoin revenues built upon it. Unfortunately for ETH and solana:So11111111111111111111111111111111111111112 and most others, they don’t capture any of those fees. Even Multicoin is giving up on SOL in favor of hyperliquid:native for this very reason. They call it “distribution, capital and data” rather than “DEX and Stablecoin fees”, but it’s the same argument. The only way to capture the value of your chain, or your DEX or your stablecoin is to have all 3 working together.
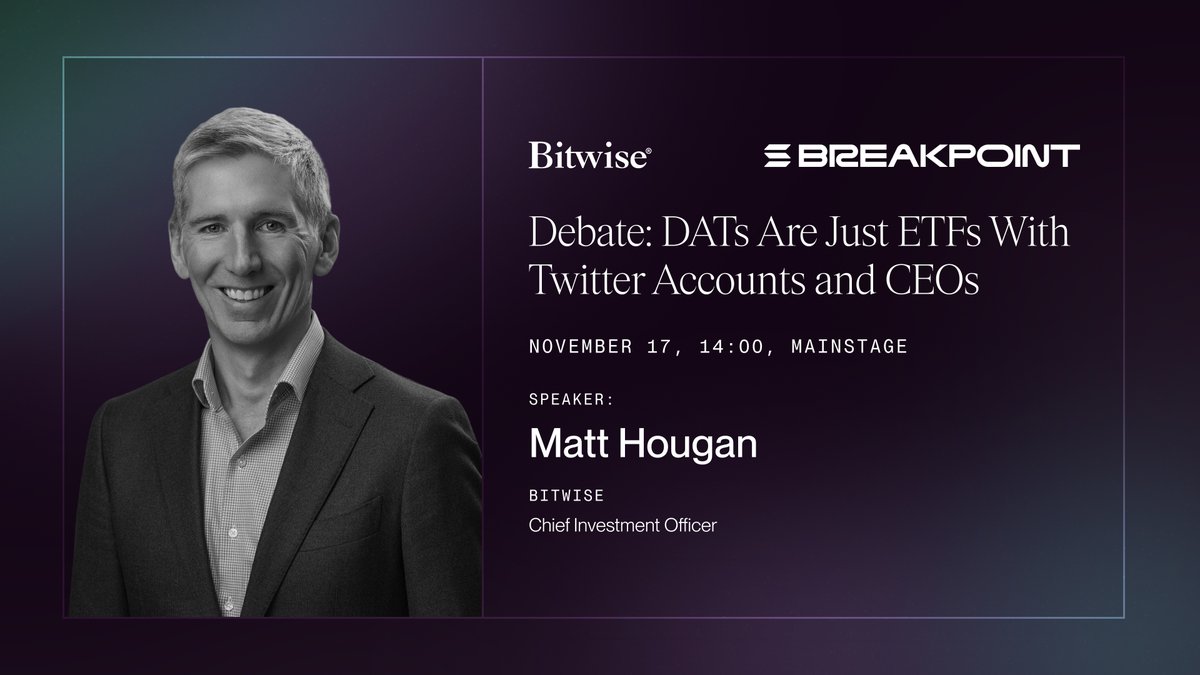
Excited to have Bitwise CIO @Matt_Hougan on stage with @KyleSamani for their session debating DATs vs ETFs at Solana Breakpoint next week.
Catch them on stage on day 2 of the conference for their session, “Debate: DATs Are Just ETFs With Twitter Accounts and CEOs.”
14:00, Mainstage
Ethereum underperformance versus Bitcoin is driven largely by some needed consolidation after three months of consecutive outperformance, the first time since early 2021. This came amongst an unwinding AI trade and a broader de-risking of the crypto markets. ETH ETF net outflows recorded $2.1bn since the beginning of October.
To me, the languishing of $ETH price, while disappointing
is arguably more a reflection of the impatience of markets
- in 2026
- steady and visible progress is made on the tokenization supercycle
- vast majority on Ethereum $ETH
- founder of ethereum @VitalikButerin affirms $ETH is a store of value
- crypto bull market just started
- AI narrative is not consuming all incremental capital
Adds up to a bullish outlook for crypto next 24-36 months
Pls buckle up 🆙