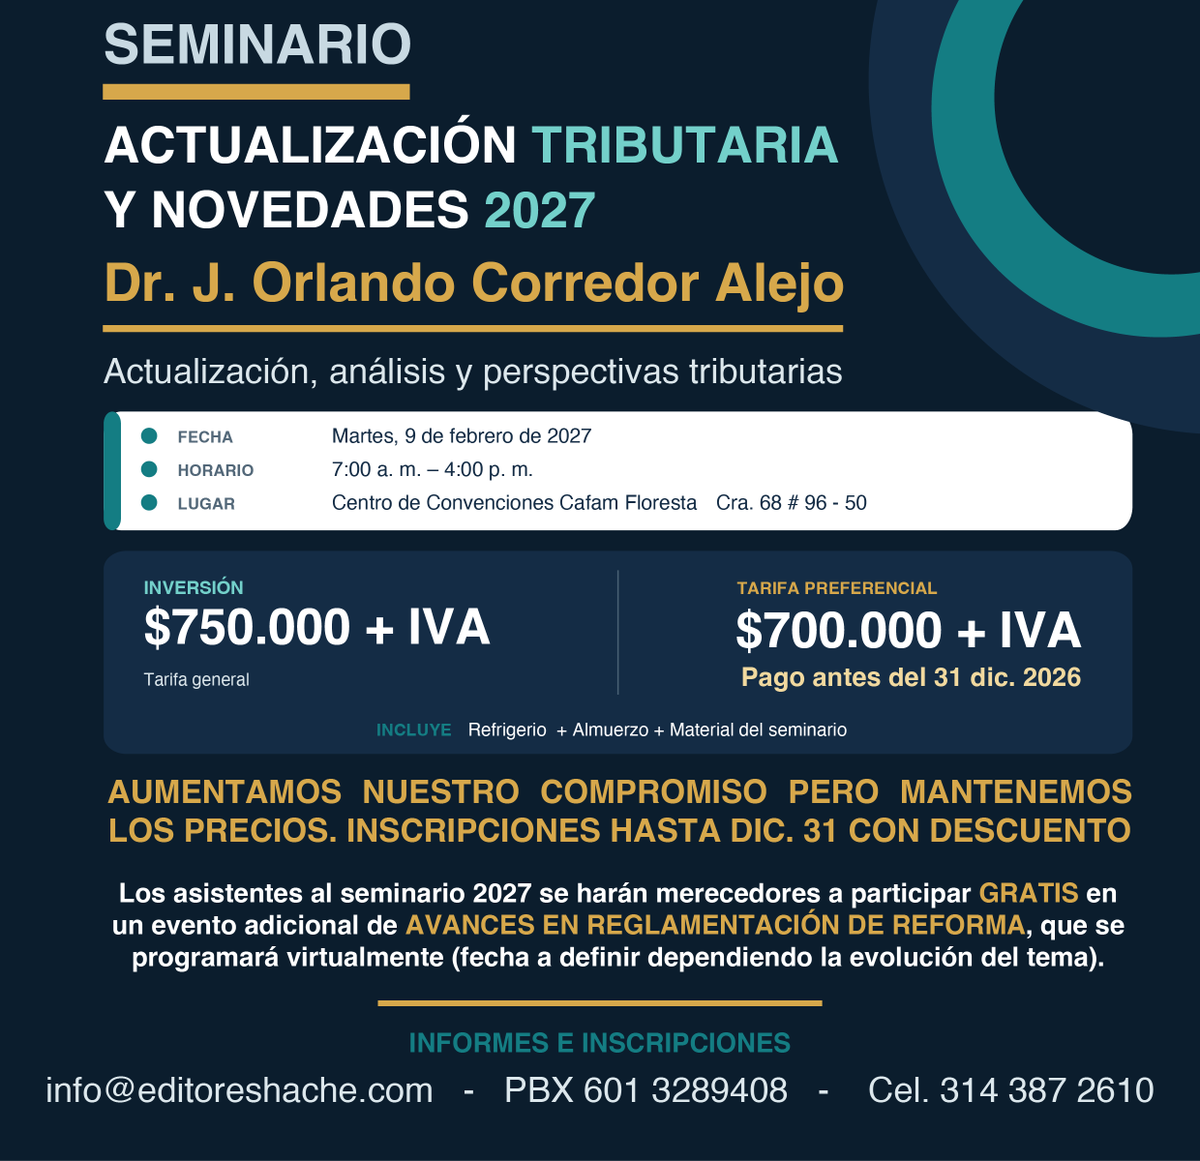
Actualización tributaria y novedades 2027 @OCorredorAlejo . Separe su cupo YA con descuento! Formas de pago: Llave,transferencia bancaria, PSE, tarjeta de crédito.
Cualquier inquietud, por favor comuníquese con nosotros al Cel 314 387 2610 o a [email protected]
Tributar Asesores SAS está buscando un CPT asistente para la firma, cargo: junior III. Experiencia de 2 o más años en impuestos y con especialización en la materia. Info en [email protected]
Derecho tributario casual y breve 2025 @OCorredorAlejo
Con precio de preventa HASTA EL VIERNES! Asegure su ejemplar YA, envío inmediato https://t.co/MzqiYLQnw1
HOY ÚLTIMO DÍA DE PREVENTA! Derecho tributario casual y breve 2025 @OCorredorAlejo con precio de especial de lanzamiento! Asegure su ejemplar YA, envío inmediato
https://t.co/MzqiYLQnw1
BREAKING:
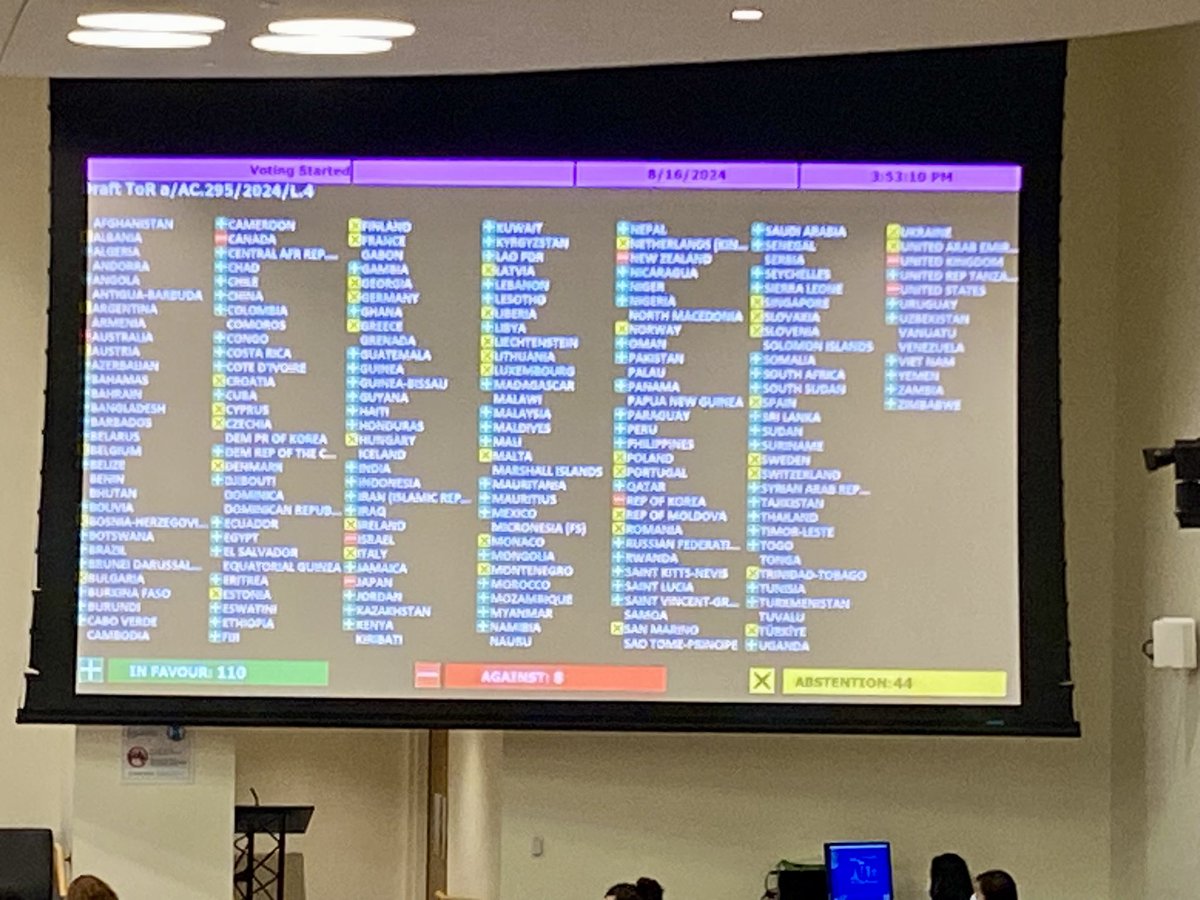
110 countries voted in favor of the final draft terms of reference for the #UNTaxConvention.
The only countries to vote against it were the U.S., U.K., South Korea, New Zealand, Japan, Israel, Canada and Australia.
44 countries abstained.
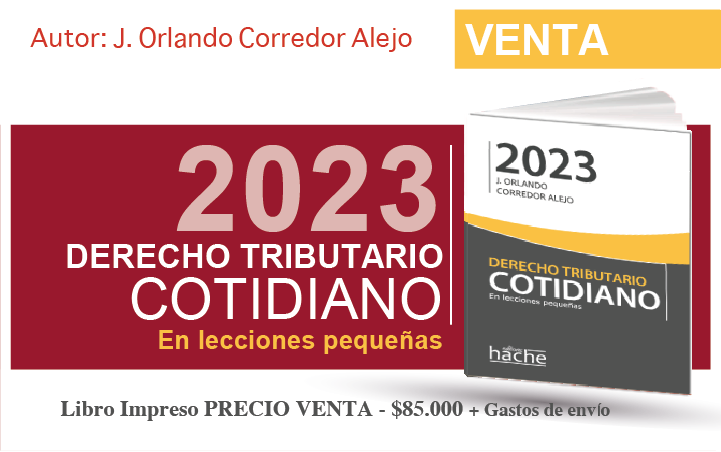
Derecho tributario cotidiano en lecciones pequeñas @OCorredorAlejo
Consulte el índice y adquiéralo con cualquier medio de pago y envío a nivel nacional en
https://t.co/Svkc7sQ86u
@dian@ICDTColombia@AsociacionCETA@incpcol señor @luiscrh comparto preocupaciones de gestión a su cargo. Importante avanzar con prontitud o generar aplazamiento de plazos de cumplimiento legal Aló?
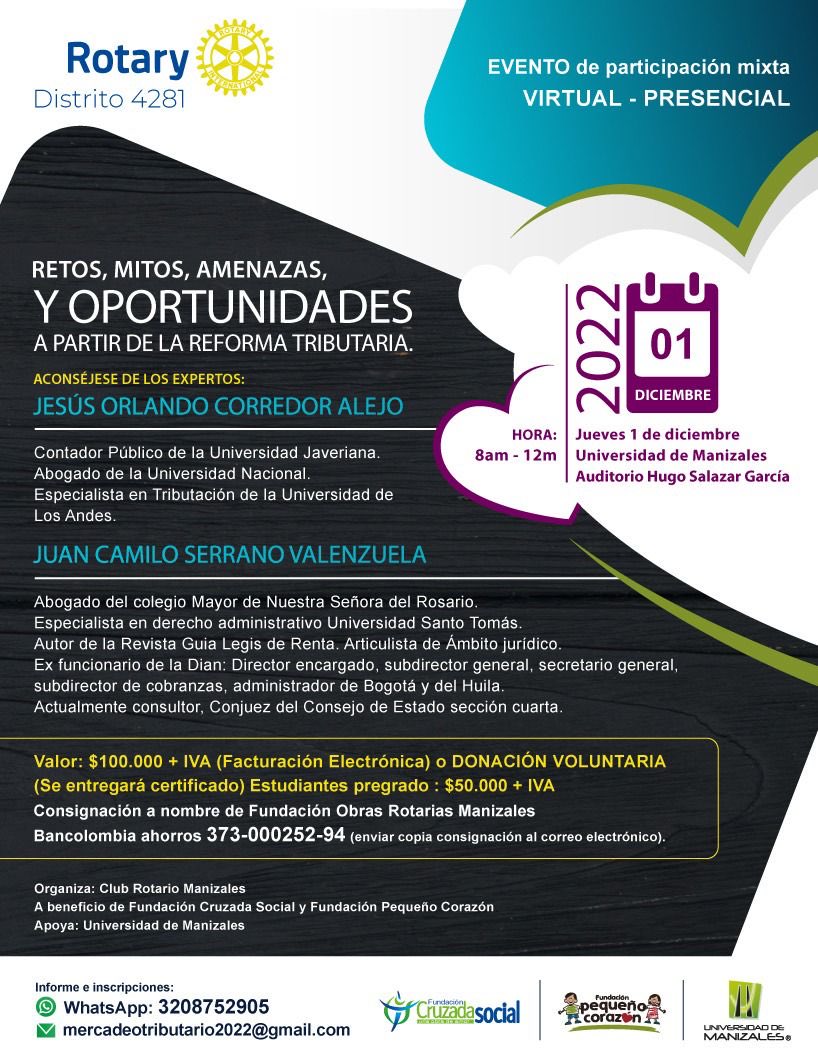
Bueno es ayudar cuando se puede. Invitación especial para mis amigos del eje cafetero y oriente colombiano. Asista, apoye y/o done que su apoyo ayuda a los niños de fundación pequeño corazón ♥️
@Heydonwb@taxleonard@InternationlTax@IFAUSA A “non-qualifying” DMT would also be taken into account as a covered tax so IMO the design on this respect is not optimal. Hopefully this will be somehow addressed in the implementation framework.
@Heydonwb@taxleonard@InternationlTax@IFAUSA Irrespective of whether the QDMT is sufficient, the IIR calculations would need to be done in full. Such a safe harbor could actually create an incentive for countries to have a QDMT.
@Heydonwb@InternationlTax@IFAUSA Not necessarily. The policy mechanism will likely be a peer review process akin to that for the BEPS minimum standards. IMO the issue is the lack of clear incentives for jurisdictions to have a “qualifying” DMT instead of a much simpler “non-qualifying” DMT.
The #Netherlands government released a draft legislative proposal for domestic implementation of the #OECD#BEPS 2.0 Pillar Two agreement; consultation launched.