Clearpool, Cicada and Ripple are building institutional credit infrastructure on the XRP Ledger.
I wanted to know how do loans on the XRPL differ with the upcoming XLS-66 and XLS-65 amendment?
Lending comes without smart contracts, how is the security seen by institutions?
Favorite use of off-chain collateral: turning high-quality receivables into liquidity on XRPL.
@ClearpoolFin Thesis simplified.
DeFi lending is a pawn shop: lock $200 to borrow $100.
Real companies don’t work like that. They need working capital, not frozen collateral.
Clearpool puts that credit on-chain. Vetted institutions borrow stables. Lenders earn the interest.
~ $1B originated since 2021. Names like Wintermute, Jane Street, Flow Traders, plus fintechs that need short-term cash.
$CPOOL is the governance + incentive layer: who can borrow, skin in the game, lender rewards.
Simple idea: move credit onto crypto rails, not just extra collateral.
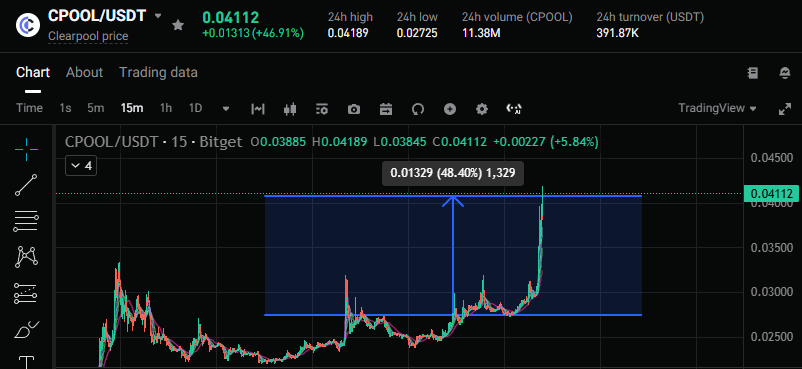
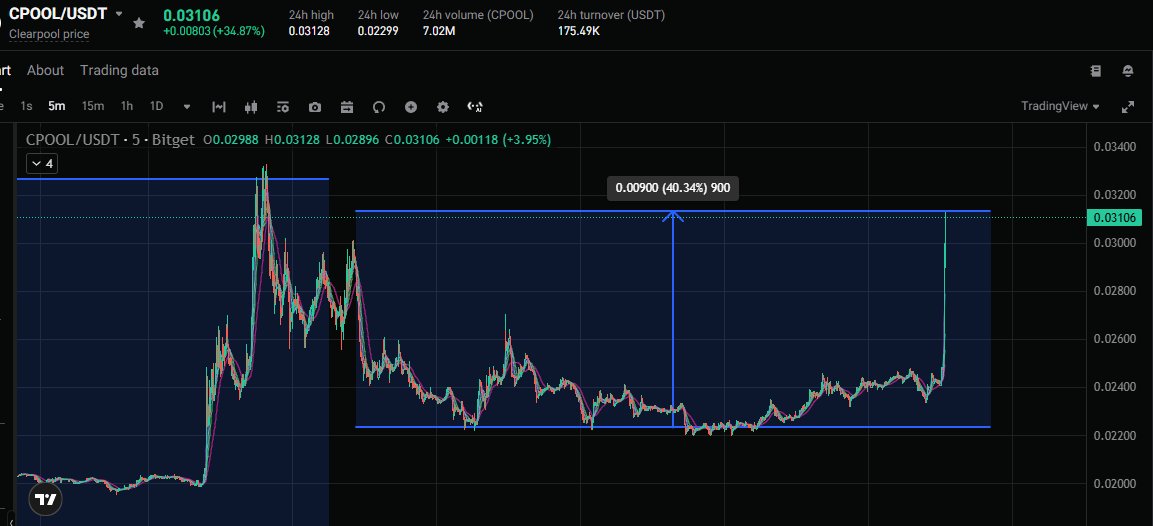
Sometimes conviction is all it takes - put in the research, verify the users and map the trajectory. You don't have to be a rocket scientist.
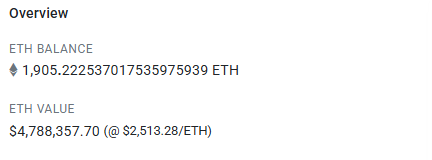
ethereum:0x808507121b80c02388fad14726482e061b8da827
Just because we are quiet doesn't mean we're out. Stack the dips, sit still - the hodl always wins.